 Ghana
Feedback welcome
Our aim is to use the best data to inform our analysis. See our Technical page for information on the IFs forecasting platform. We appreciate your help and references for improvements via our feedback form.
This page provides a comprehensive macroeconomic and development analysis of Ghana, assessing the country’s structural socio-economic constraints and growth prospects through 2043. The study evaluates alternative development trajectories, highlighting the potential for sustained economic expansion driven by Ghana’s abundant natural resource endowment, while also addressing persistent challenges related to poverty, income inequality, institutional governance, and dependence on primary commodity exports. The scenarios examine the potential effects of productivity and structural transformation across key sectors, including agriculture, education, and manufacturing. The analysis seeks to inform policymakers and researchers by offering evidence-based insights to support inclusive growth, economic diversification, and long-term development planning in Ghana.
For more information about the International Futures modelling platform we use to develop the various scenarios, please see the Technical page.
The Tableau workbook is available here.
Executive Summary
We begin this page with an introductory assessment of the country’s context by looking at current population distribution, social structure, climate and topography.
Ghana is a lower-middle-income country located on the Gulf of Guinea in West Africa. It shares borders with Burkina Faso to the north, Côte d’Ivoire to the west, and Togo to the east, all of which are fellow members of the Economic Community of West African States (ECOWAS). The capital city, Accra, is situated in the Greater Accra Region along the country’s southern coast. Covering an area of approximately 238,535 km², Ghana experiences a tropical climate characterised by distinct rainy and dry seasons. The country’s diverse physical geography is reflected in its six major ecological zones: the Sudan Savannah, Guinea Savannah, Coastal Savannah, Forest–Savannah Transition Zone, Deciduous Forest Zone, and Tropical Rainforest Zone. These ecological regions support a wide range of agricultural, forestry, and biodiversity resources that are important to the country’s economy and livelihoods.
This section is followed by an analysis of the Current Path for [Ghana] which informs the country’s likely current development trajectory to 2043. It is based on current geopolitical trends and assumes that no major shocks would occur in a ‘business-as-usual’ future.
- Ghana is the second-most populous country in West Africa, after Nigeria, and the 14th most populous on the African continent. The country’s population grew from approximately 15.4 million in 1990 to an estimated 35 million in 2025 and is projected to reach 46.5 million by 2043. This sustained demographic growth is expected to expand both the labour force and domestic consumer market, creating opportunities for economic development while increasing demand for public services and infrastructure. In 2025, an estimated 35.4% of the population was under the age of 15, 60.7% was of working age (15–64 years), and 3.9% was aged 65 years and above.
- Ghana’s economy, measured in market exchange rates (MER), expanded from US$15.9 billion in 1990 to an estimated US$95.2 billion in 2025, making it the second-largest economy in West Africa. Over this period, the country recorded an average annual growth rate of 5.2%, outpacing the 3.9% average among Africa’s lower-middle-income countries (LMICs). Looking ahead, Ghana’s GDP is projected to more than triple to US$298.5 billion by 2043.
- In 2025, Ghana’s GDP per capita, measured at 2021 purchasing power parity (PPP), reached approximately US$6 949, more than doubling from US$2 786 in 1990. This substantial improvement reflects decades of sustained economic growth, rising productivity, and upward revisions from GDP rebasing. As a result, Ghana has consolidated its position among Africa’s seven leading LMICs in terms of per capita income.
- Using the international extreme poverty line of US$3 per person per day (2021 PPP), an estimated 32.3% of Ghanaians were living in extreme poverty in 2025, down sharply from 79.1% in 1990. Under the Current Path, extreme poverty is projected to decline further to 6% by 2043.
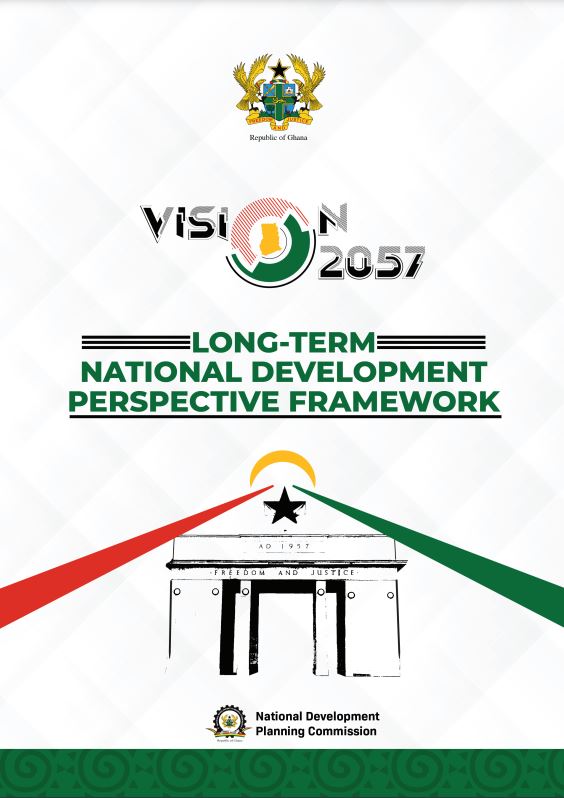
- Ghana’s Vision 2057 is the country’s Long-Term National Development Perspective Framework which reflects the development aspirations of the Ghanaian people. Its Vision is to aspire to “A free, just, prosperous, and self-reliant nation which secures the welfare and happiness of its citizens, while playing a leading role in international affairs”. The overall goal is to improve the living standards of Ghanaians and attain an upper-middle-income country status.
The next section compares progress on the Current Path with eight sectoral scenarios. These are Demographics and Health; Agriculture; Education; Manufacturing; the African Continental Free Trade Area (AfCFTA); Large Infrastructure and Leapfrogging; Financial Flows; and Governance. Each scenario is benchmarked to present an ambitious but reasonable aspiration in that sector.
- The Demographics and Health scenario will reduce the infant mortality rate from an estimated 29.8 deaths per 1 000 births in 2025 to 15.3 deaths by 2043, about 1.9 fewer deaths than under the Current Path. The scenario pushes the ratio of the working-age population to dependants to 2.0:1 by 2043, far above the 1.7:1 required to enter a potential demographic window of opportunity.
- In the Agriculture Scenario, crop yields are projected to reach 16.2 metric tonnes per hectare by 2043, which will be 44.1% higher than under the Current Path scenario. At this level, Ghana’s agricultural productivity would be nearly three times the projected average yield of 6.3 metric tonnes per hectare for LMICs in Africa.
- In the Education Scenario, educational attainment and learning outcomes improve substantially. By 2043, the average years of schooling among young adults aged 15–24 is projected to reach 12.2 years, which will be 0.5 years higher than under the Current Path scenario and above the projected average of 9 years for lower-middle-income countries in Africa. The scenario also delivers significant improvements in educational quality, with average test scores rising to 44.8% for primary school students and 42.9% for secondary school students by 2043, representing gains of 7.3 and 5.2 percentage points, respectively, compared with the Current Path.
- In the Manufacturing scenario, Ghana makes substantial progress in industrialisation, such that by 2043 the share of the manufacturing sector in GDP will be about 21.8%, about 2.6 percentage points above the Current Path forecast.
- In the African Continental Free Trade Area (AfCFTA) Scenario, Ghana’s integration into regional and continental markets is expected to deepen significantly. As trade barriers decline and cross-border commerce expands, total trade is projected to reach 95.7% of GDP by 2043, 15.5 percentage points above the Current Path. This increase in trade openness is accompanied by a shift in the country’s trade balance from a surplus of 0.82% of GDP to a deficit of 0.38% of GDP by 2043. While the emerging trade deficit reflects faster growth in imports relative to exports, it also indicates a more dynamic economy with stronger participation in regional value chains, increased access to intermediate goods and capital equipment, and greater opportunities for productivity growth and economic diversification.
- In the Large Infrastructure and Leapfrogging Scenario, Ghana is projected to achieve universal electricity access by 2042. This expansion in electricity access is expected to support a wider transition to cleaner household energy, with 76.1% of households using modern fuels for cooking. The scenario also accelerates digital connectivity, raising fixed broadband subscriptions to 22.6 per 100 people by 2043, compared with 17.1 subscriptions under the Current Path.
- Under the Financial Flows scenario, average income per capita (PPP) in Ghana is projected to be US$730 higher than under the Current Path by 2043. This is accompanied by a reduction in poverty, with extreme poverty rate declining by 1.2 percentage points, equivalent to about 553 230 fewer people living in extreme poverty relative to the Current Path.
- Generally, Ghana performs better on governance indices than most African countries. Ghana’s composite governance index score of 0.58 in 2025 was 22.5% higher than the estimated average for the continent. In the Governance scenario, Ghana's composite governance index score will improve to 0.71, about 9.5% above the Current Path by 2043.
In the fourth section, we compare the impact of each of these eight sectoral scenarios with one another and subsequently with a Combined scenario (the integrated effect of all eight scenarios). In our forecasts, we measure progress on various dimensions such as economic size (in market exchange rates), gross domestic product per capita (in purchasing power parity), extreme poverty, carbon emissions, the changes in the structure of the economy, and selected sectoral dimensions such as progress with mean years of education, life expectancy, the Gini coefficient or reductions in mortality rates.
- In the Combined Scenario, Ghana’s GDP per capita is projected to be US$6 670 higher than under the Current Path by 2043, reflecting the cumulative benefits of simultaneous progress across multiple development sectors. Among the individual interventions, the Governance Scenario delivers the largest increase in GDP per capita, raising it by approximately US$860 relative to the Current Path. This is followed by the AfCFTA, Financial Flows scenarios and the Infrastructure and Leapfrogging scenario, which also generate substantial income gains through improved economic efficiency, trade integration, and investment. In contrast, the Education Scenario has the smallest direct impact on GDP per capita by 2043, increasing it by US$250 above the Current Path. This relatively modest effect reflects the longer time horizon typically required for investments in human capital to translate into higher productivity and income growth.
- The Combined Scenario is projected to reduce Ghana’s extreme poverty rate to 3.4% by 2043, compared with 12.6% under the Current Path. This 9.2 percentage points reduction would enable approximately 4.3 million Ghanaians to escape extreme poverty by 2043. Among the individual interventions, the Governance Scenario has the greatest potential to reduce poverty, lowering the extreme poverty rate to 10.5% by 2043 and lifting approximately one million people out of extreme poverty relative to the Current Path. This is followed by the Infrastructure and Leapfrogging and Agriculture scenarios, which are projected to lift about 891 140 and 720 450 people out of extreme poverty, respectively. In contrast, the Demographics and Health Scenario has the smallest impact on poverty reduction, although it would still enable approximately 479 360 people to move above the extreme poverty threshold by 2043.
- In the Combined Scenario, Ghana’s economy, measured as GDP at market exchange rates (MER), is projected to reach US$489 billion by 2043—approximately US$190.5 billion larger than under the Current Path. This represents a 63.8% increase, highlighting the substantial economic gains that could be achieved through coordinated policy interventions across multiple sectors. While the services sector is expected to remain the largest contributor to economic output, its share of GDP is projected to decline by 4.4 percentage points relative to the Current Path, to 52.5% by 2043.
We end this page with a summarising conclusion offering key recommendations for decision-making.
Ghana has made notable progress in improving human development outcomes and possesses stronger long-term growth prospects than many of its African peers in the lower-middle-income category. However, on its current trajectory, the country is unlikely to achieve its development aspirations and targets fully. Realising its full development potential will require Ghana to accelerate structural transformation and better harness the diverse economic opportunities available to it. This calls for a comprehensive and coordinated package of policy reforms and investments across key sectors, including demographics and health, education, agriculture, infrastructure, manufacturing, trade, financial flows, and governance. Such interventions would help place the country on a more inclusive, resilient, and sustainable development path while accelerating economic growth, reducing poverty, and improving living standards.
All charts for Ghana Development Futures
- Chart 1: Political map of Ghana
- Chart 2: Population structure in the Current Path, 1990–2043
- Chart 3: Population distribution map, 2023
- Chart 4: Urban and rural population in the Current Path, 1990-2043
- Chart 5: GDP (MER) and growth rate in the Current Path, 1990–2043
- Chart 6: Size of the informal economy in the Current Path, 2020-2043
- Chart 7: GDP per capita in Current Path, 1990–2043
- Chart 8: Extreme poverty in the Current Path, 2020–2043
- Chart 9: National Development Plan of Ghana
- Chart 10: Relationship between Current Path and scenario
- Chart 11: Mortality distribution in the Current Path, 2023 and 2043
- Chart 12: Infant mortality rate in Current Path and Demographics and Health scenario, 2020–2043
- Chart 13: Demographic dividend in the Current Path and the Demographics and Health scenario, 2020–2043
- Chart 14: Crop production and demand in the Current Path, 1990-2043
- Chart 15: Import dependence in the Current Path and Agriculture scenario, 2020–2043
- Chart 16: Progress through the education funnel in the Current Path, 2023 and 2043
- Chart 17: Mean years of education in the Current Path and Education scenario, 2020–2043
- Chart 18: Value-add by sector as % of GDP in the Current Path, 2023 and 2043
- Chart 19: Value-add by the manufacturing sector in the Current Path and Manufacturing scenario, 2020–2043
- Chart 20: Exports and imports as % of GDP in the Current Path, 2000-2043
- Chart 21: Trade balance in the Current Path and AfCFTA scenario, 2020–2043
- Chart 22: Electricity access: urban, rural and total in the Current Path, 2000-2043
- Chart 23: Cookstove usage in the Current Path and Large Infra/Leapfrogging scenario, 2020–2043
- Chart 24: Access to mobile and fixed broadband in the Current Path and the Large Infra/Leapfrogging scenario, 2020–2043
- Chart 25: FDI, foreign aid and remittances as % of GDP in the Current Path and in the Financial Flows scenario, 1990-2043
- Chart 26: Government revenue in the Current Path and Financial Flows scenario, 2020–2043
- Chart 27: Government effectiveness score in the Current Path, 2002-2043
- Chart 28: Composite governance index in the Current Path and Governance scenario, 2023 and 2043
- Chart 29: GDP per capita in the Current Path and scenarios, 2020–2043
- Chart 30: Poverty in the Current Path and scenarios, 2020–2043
- Chart 31: GDP (MER) in the Current Path and Combined scenario, 2020–2043
- Chart 32: GDP per capita in the Current Path and Combined scenario, 2023-2043
- Chart 33: Value-add by sector in the Current Path and Combined scenario, 2023 and 2043
- Chart 34: Informal sector in the Current Path and Combined scenario, 2020–2043
- Chart 35: Poverty in the Current Path and Combined scenario, 2023 and 2043
- Chart 36: Life expectancy in the Current Path and Combined scenario, 2020–2043
- Chart 37: Carbon dioxide emissions in the Current Path and Combined scenario, 2022–2043
- Chart 38: Energy demand and production by type in the Current Path and Combined scenario, 2020-2043
- Chart 39: Policy recommendations
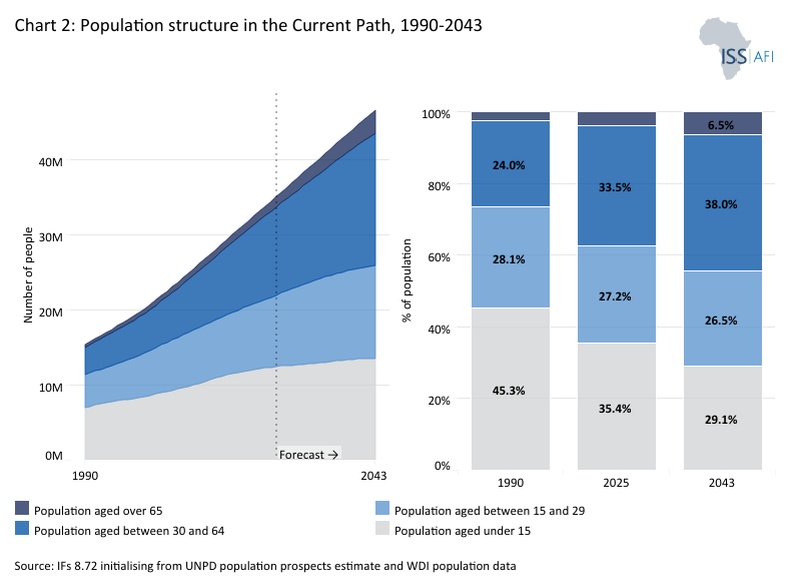
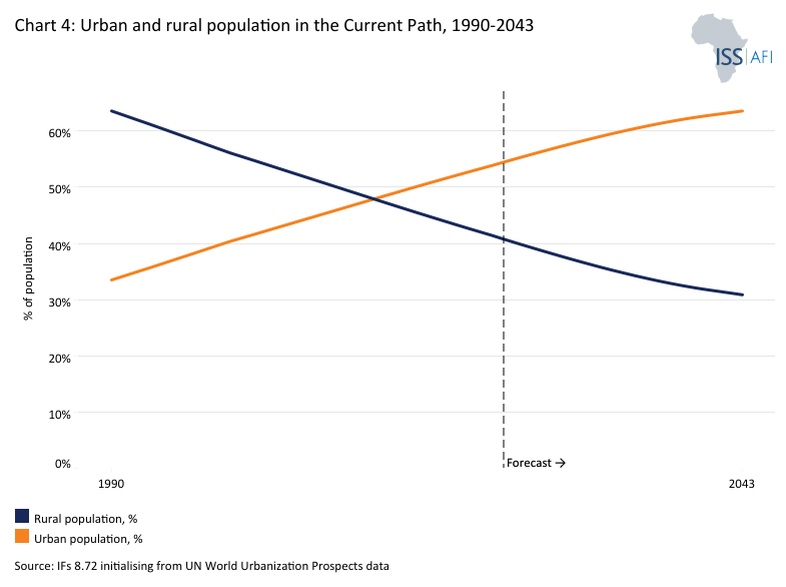
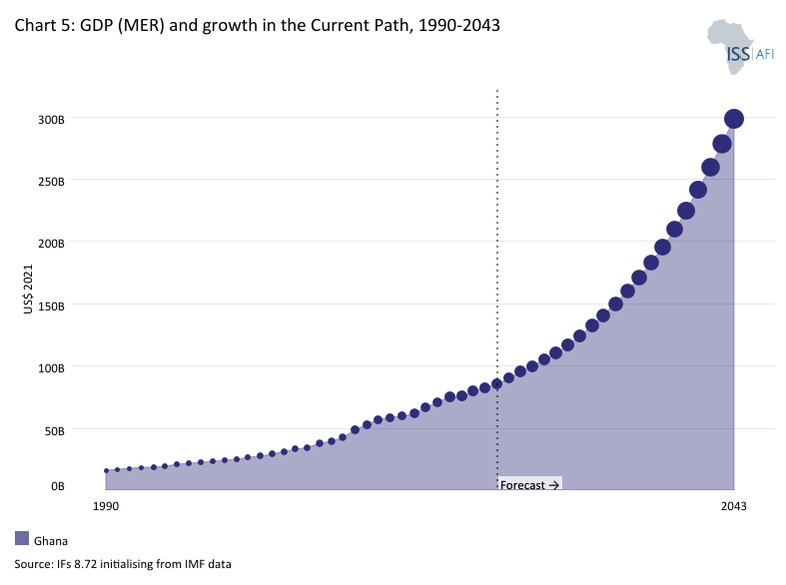
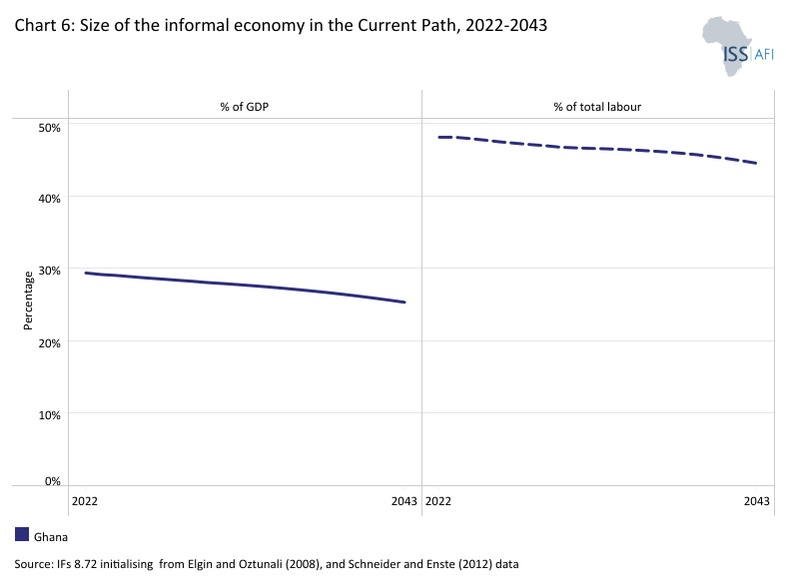
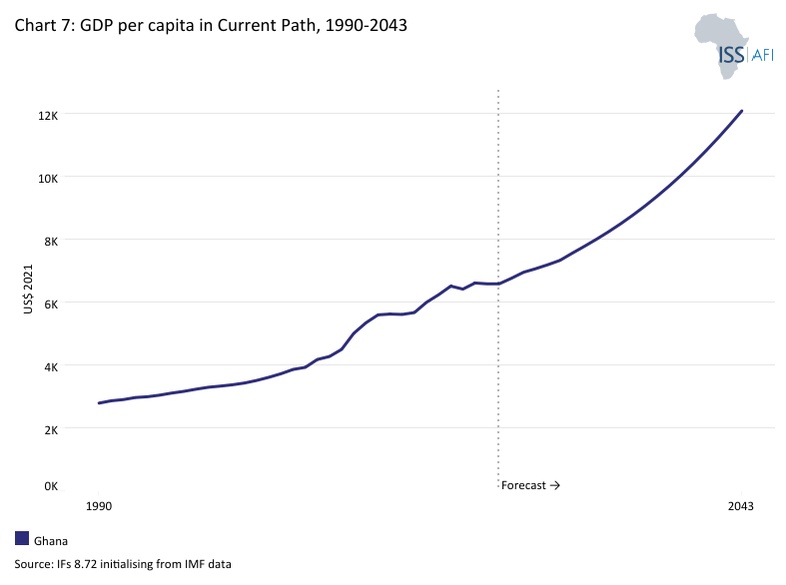
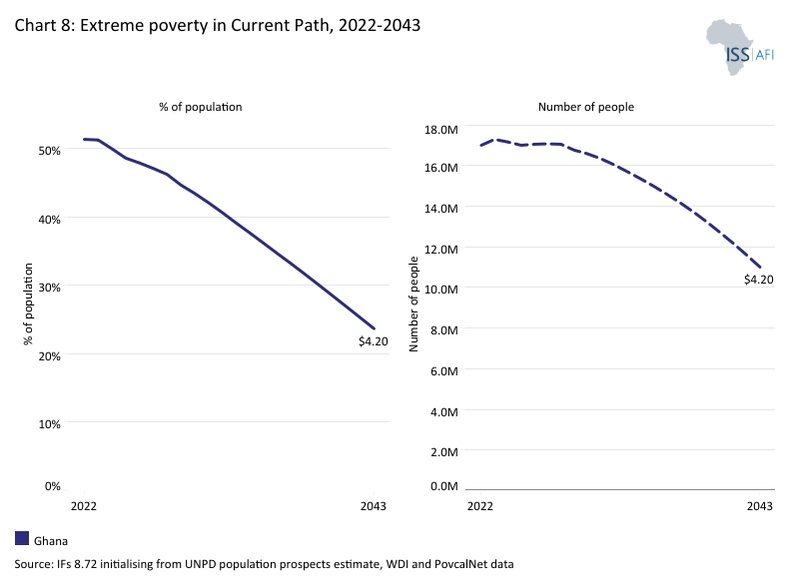
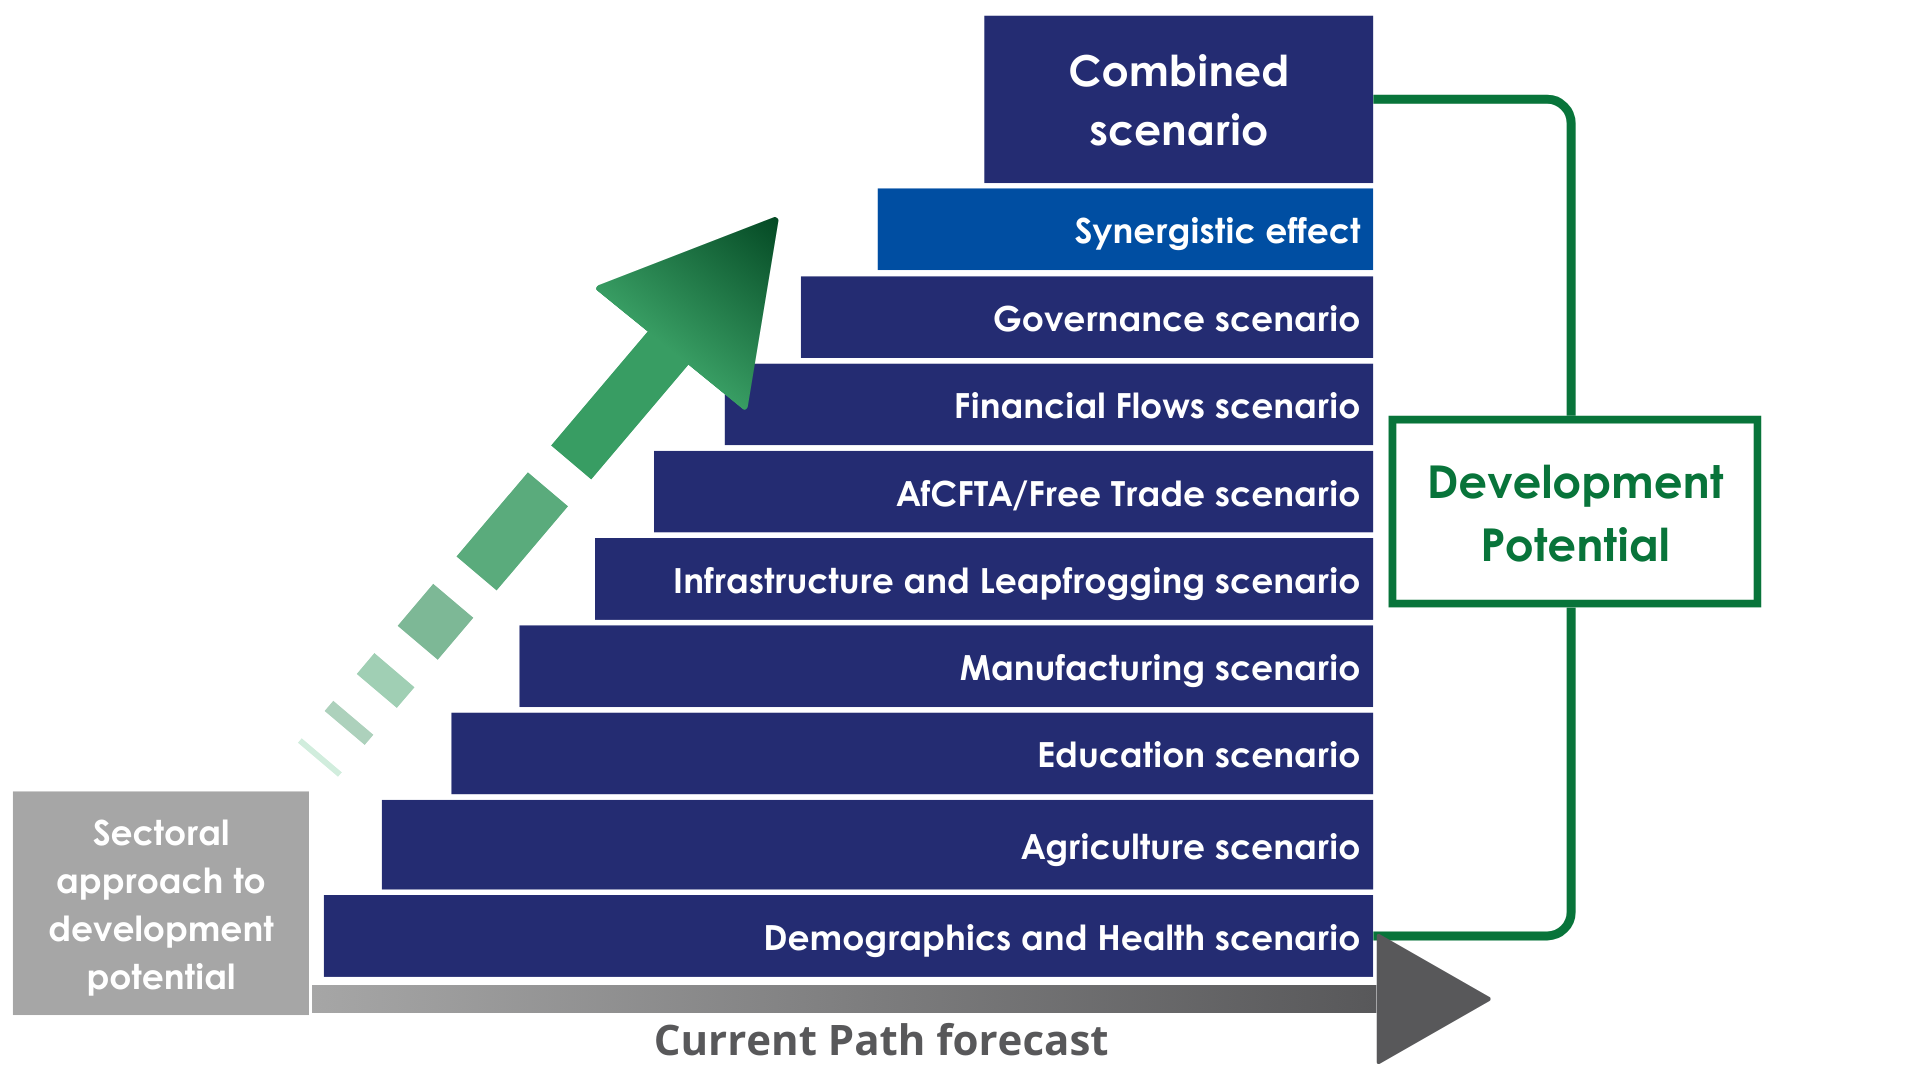
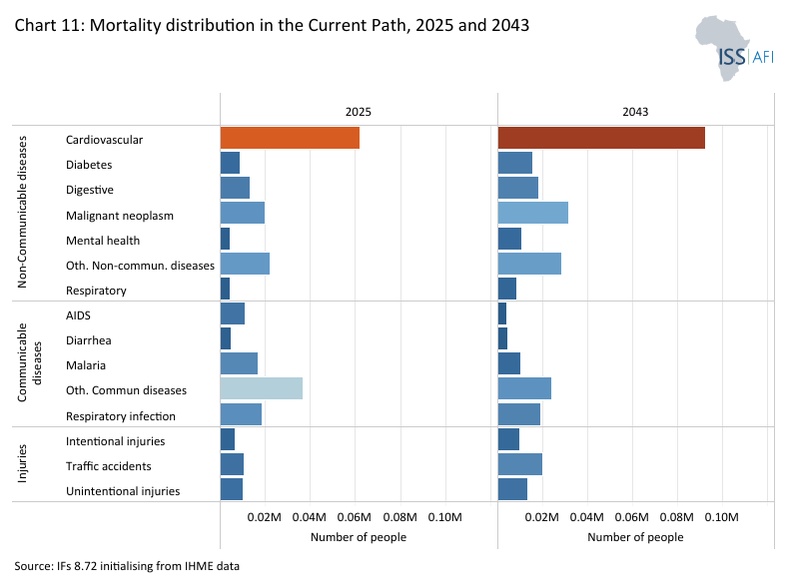
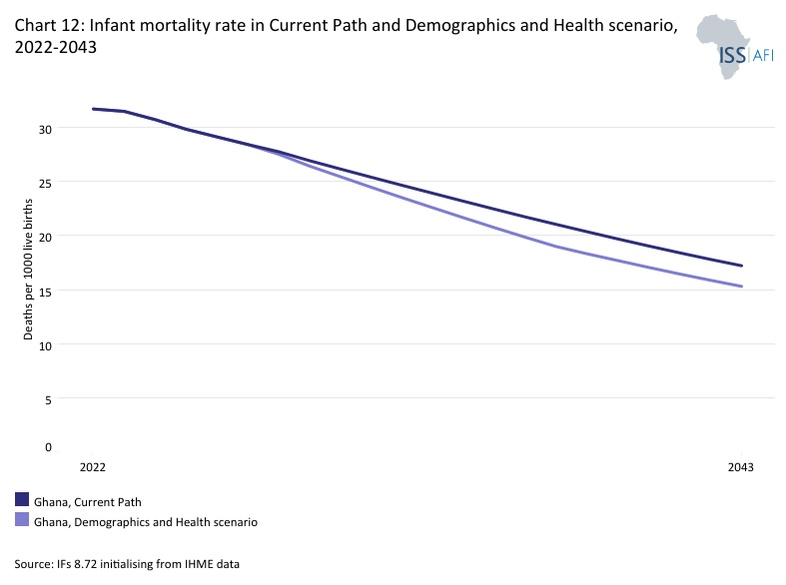
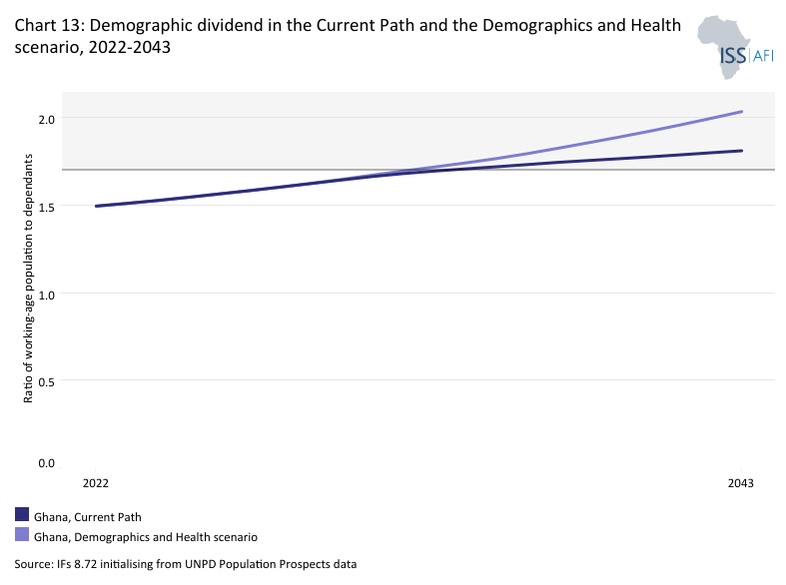
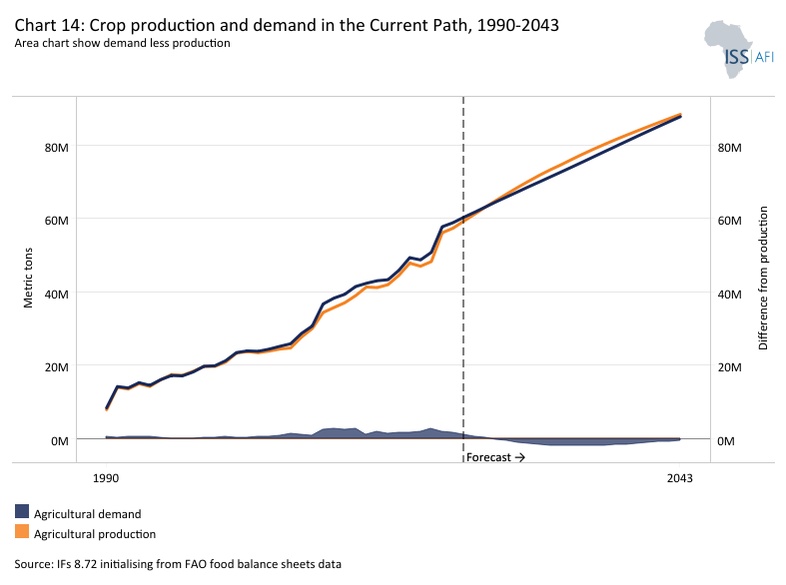
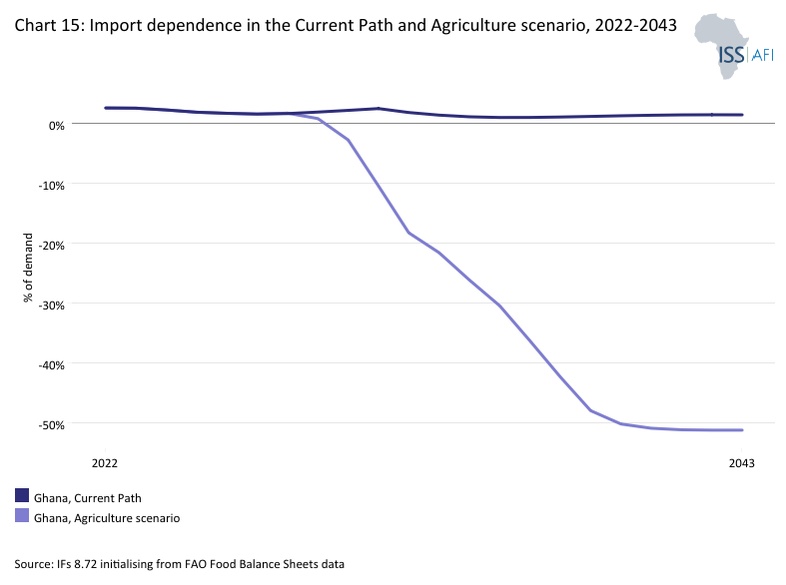
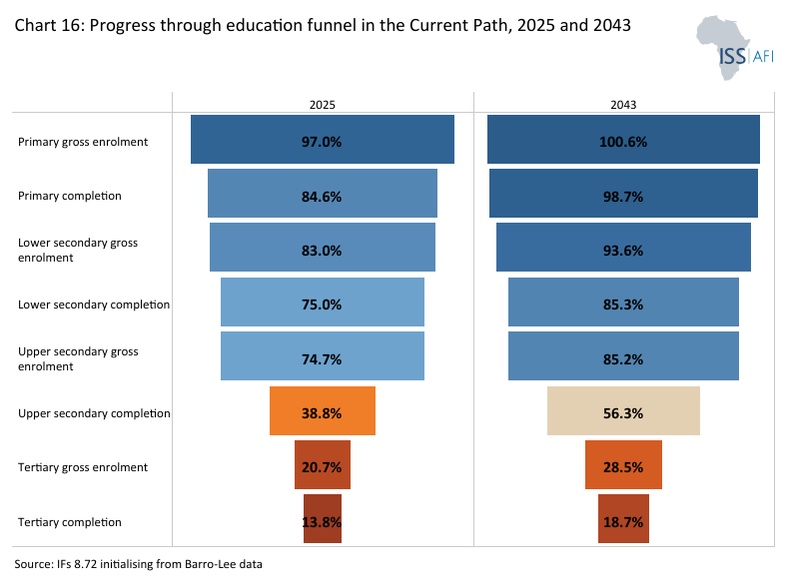
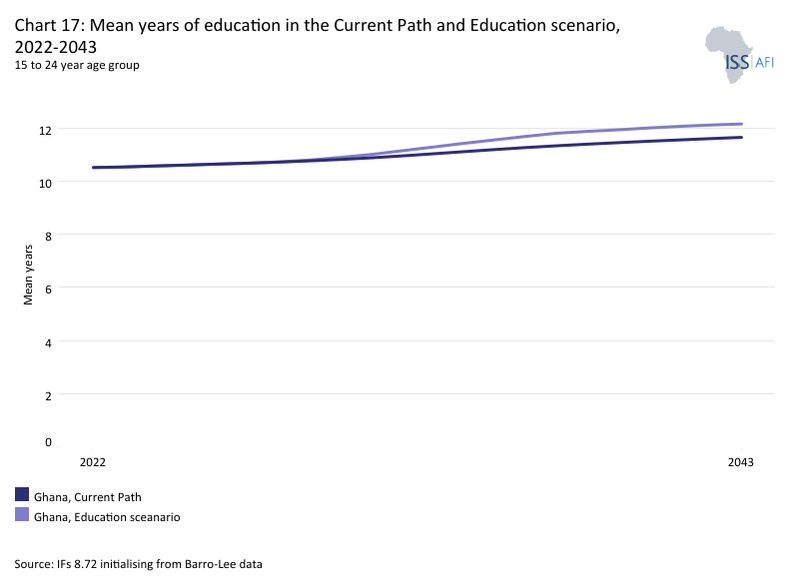
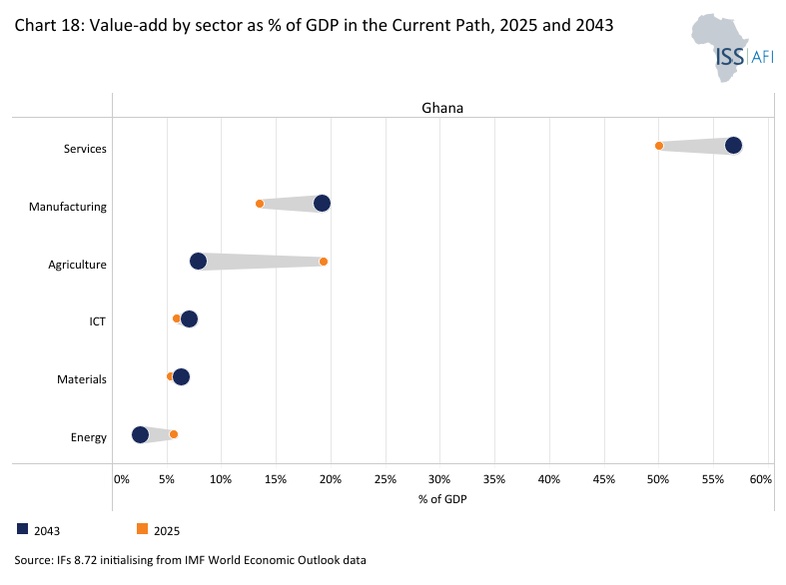
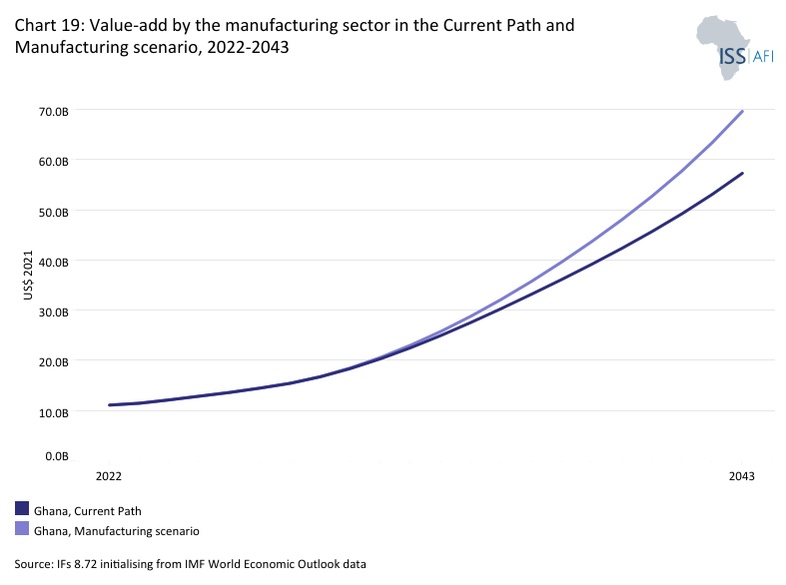
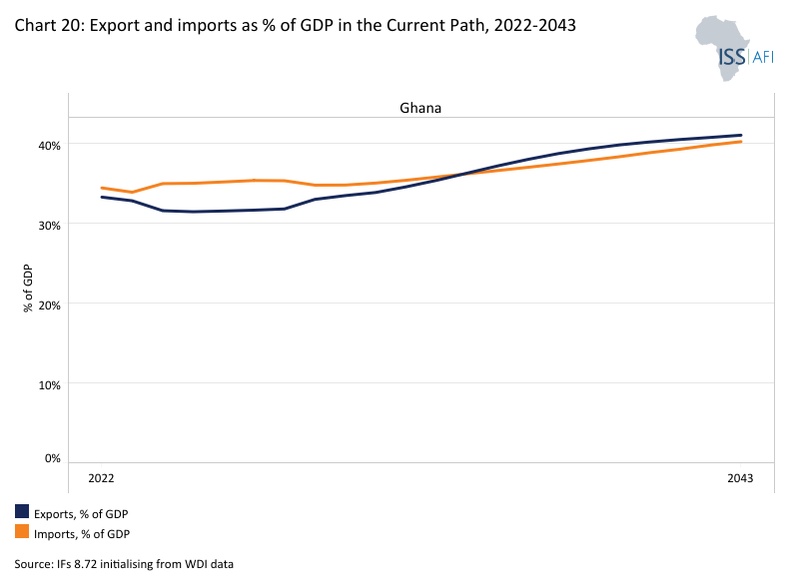
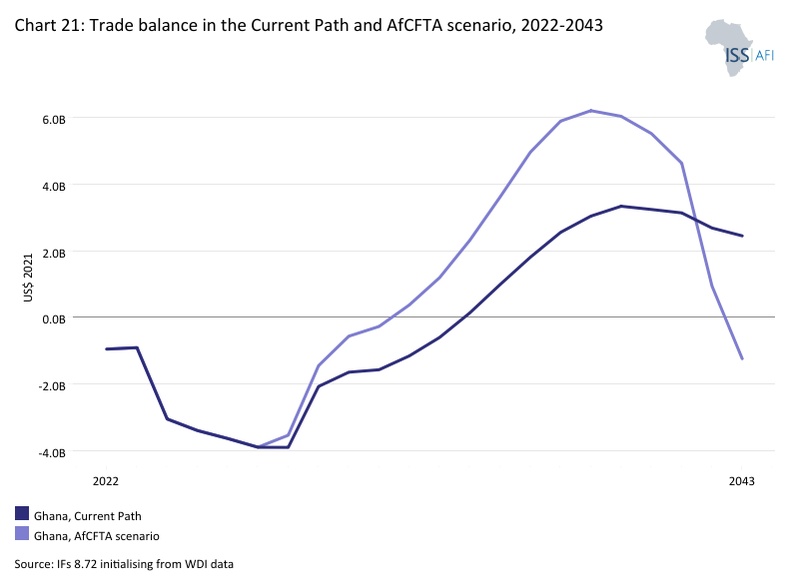

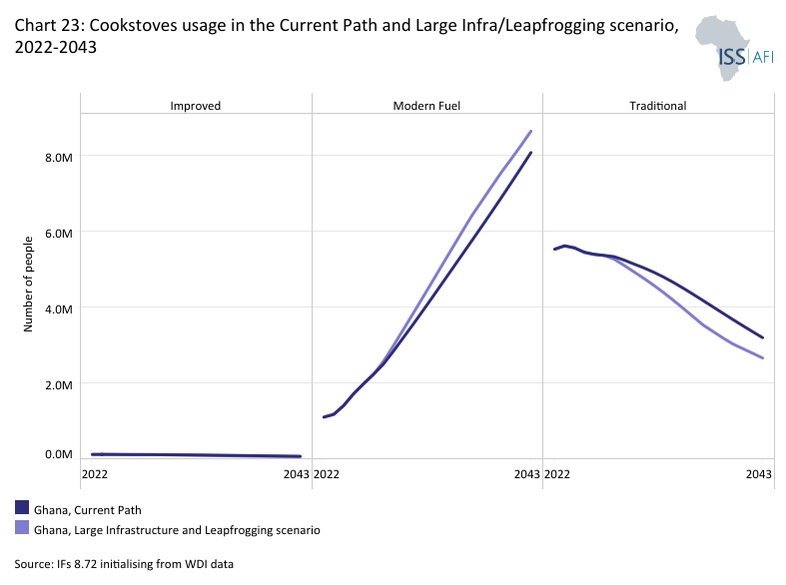
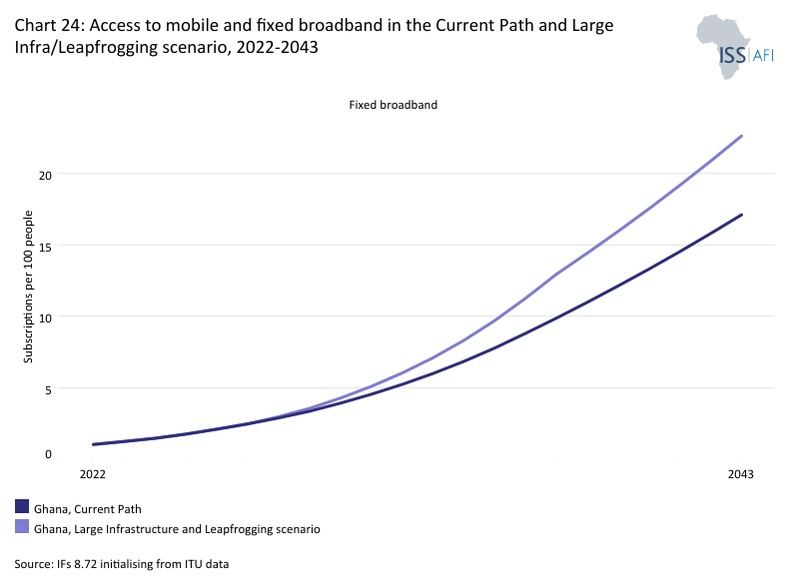
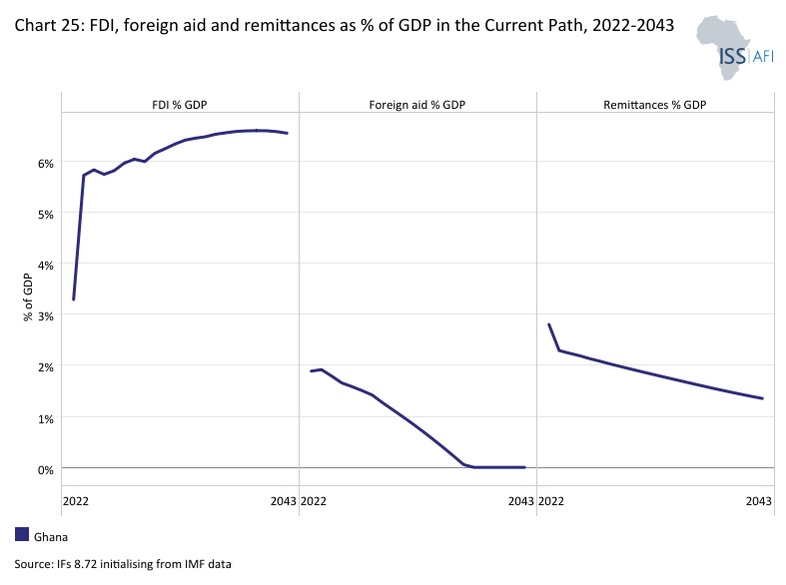
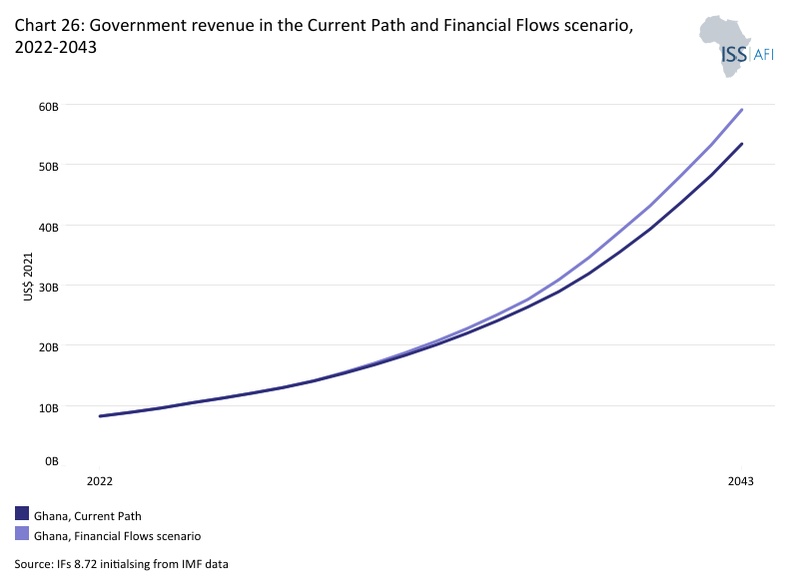
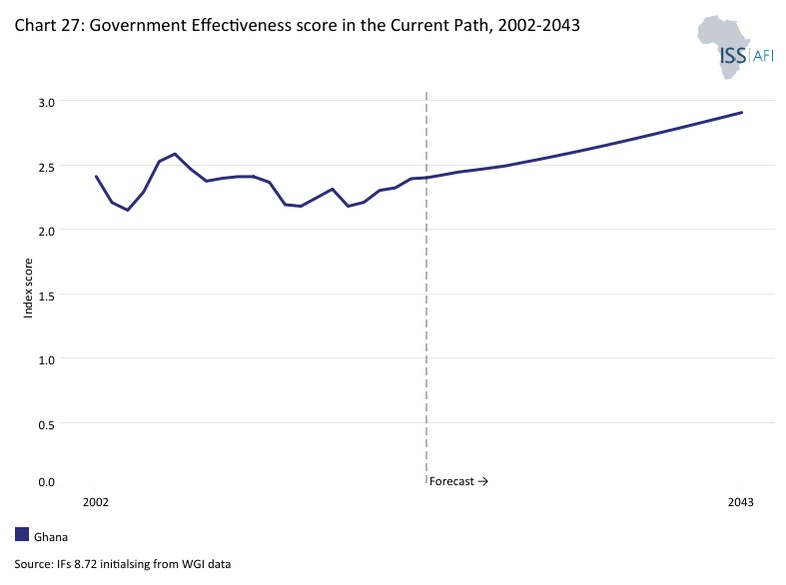
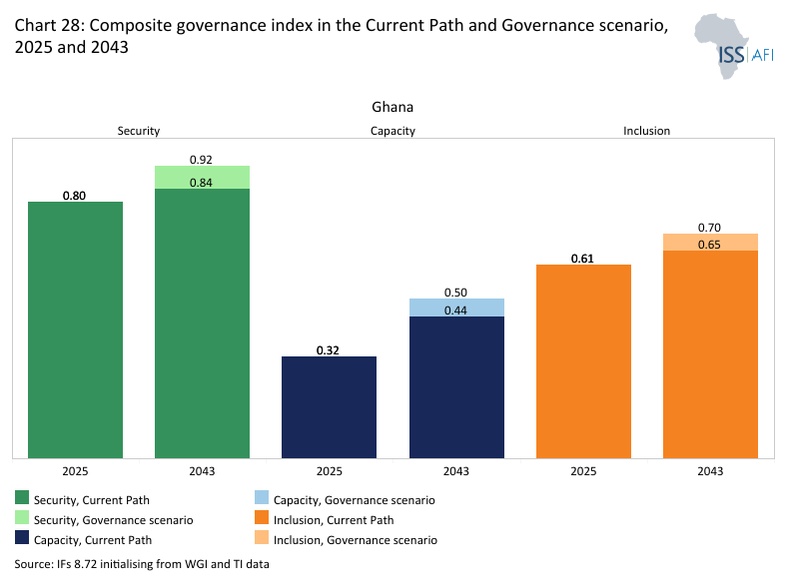
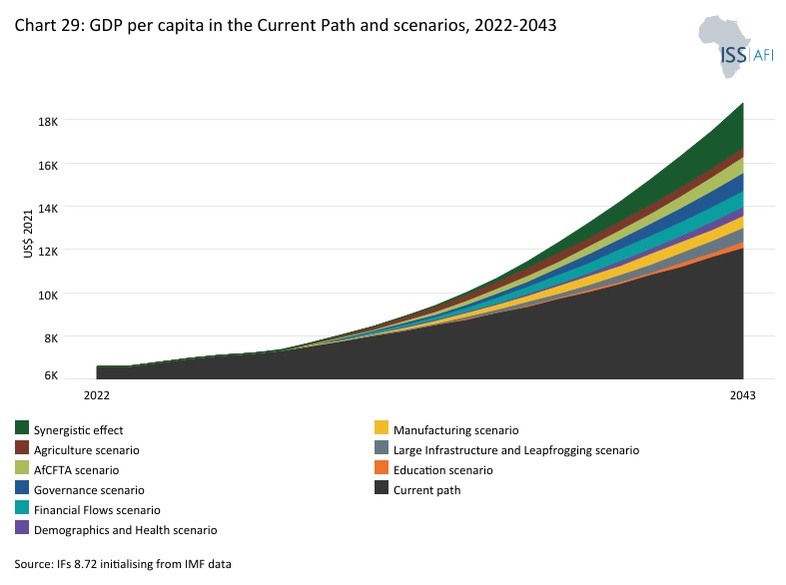
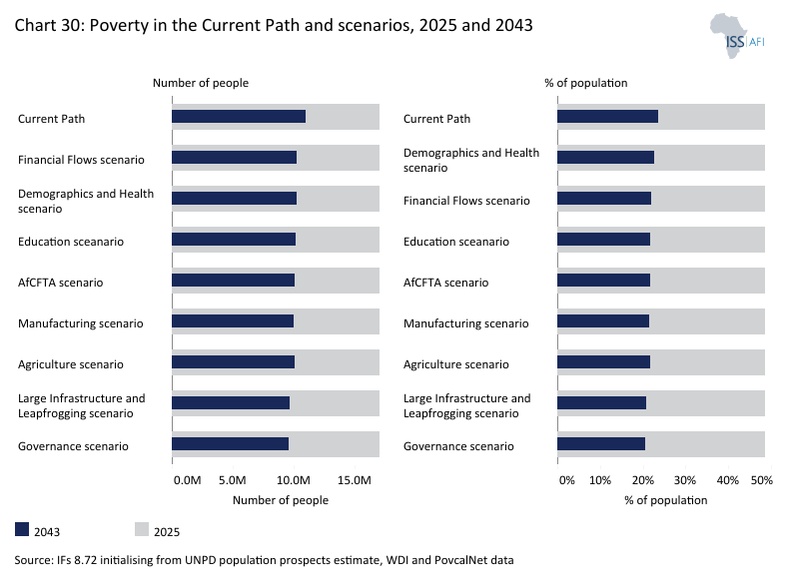
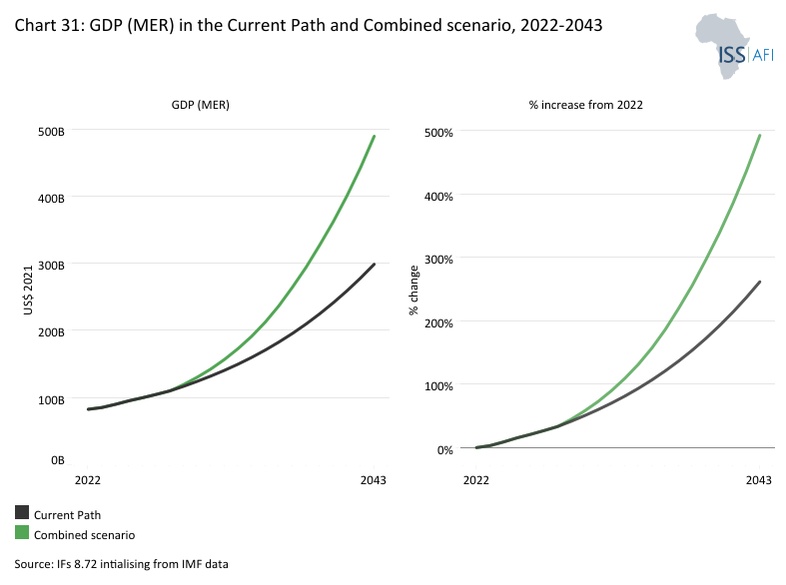
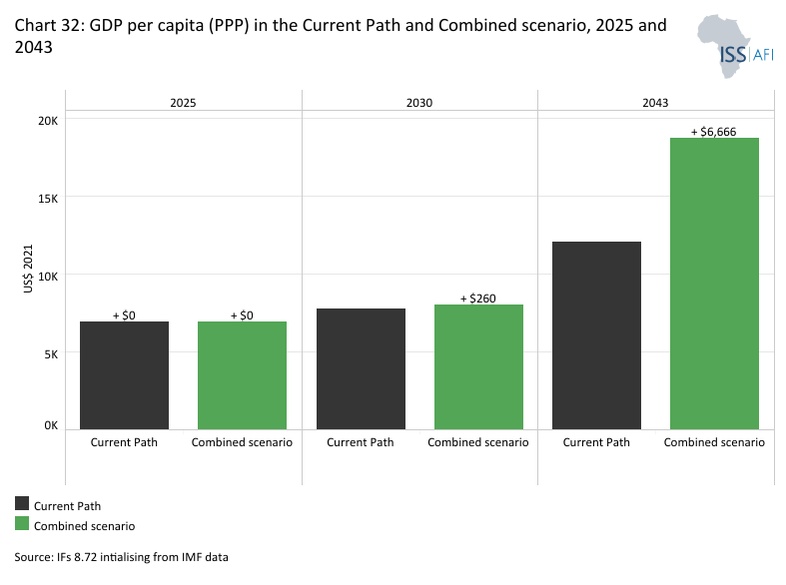
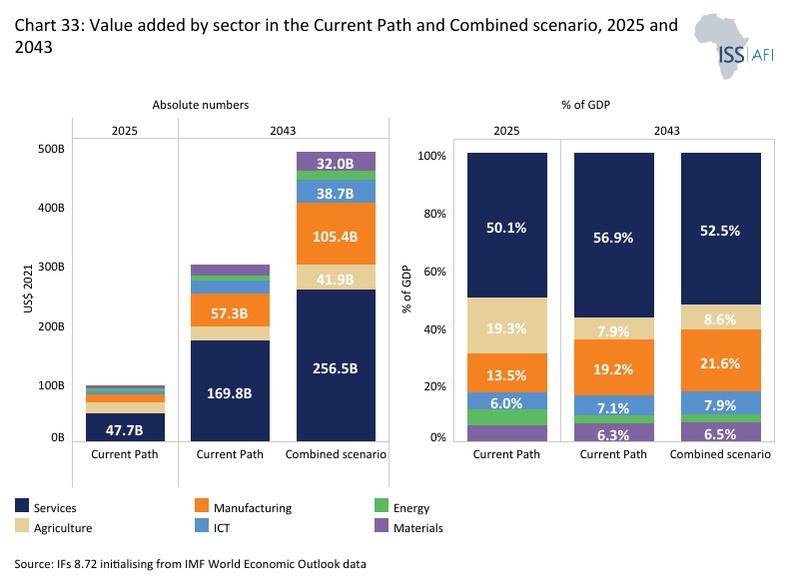
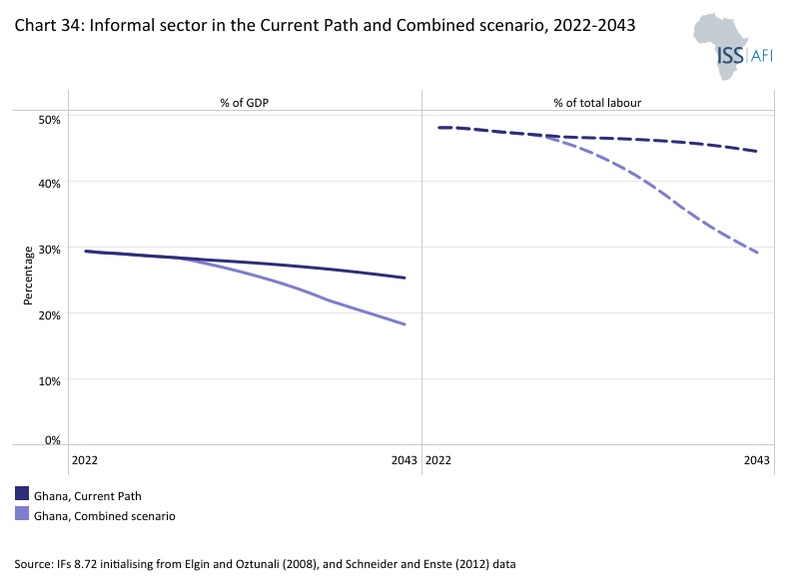
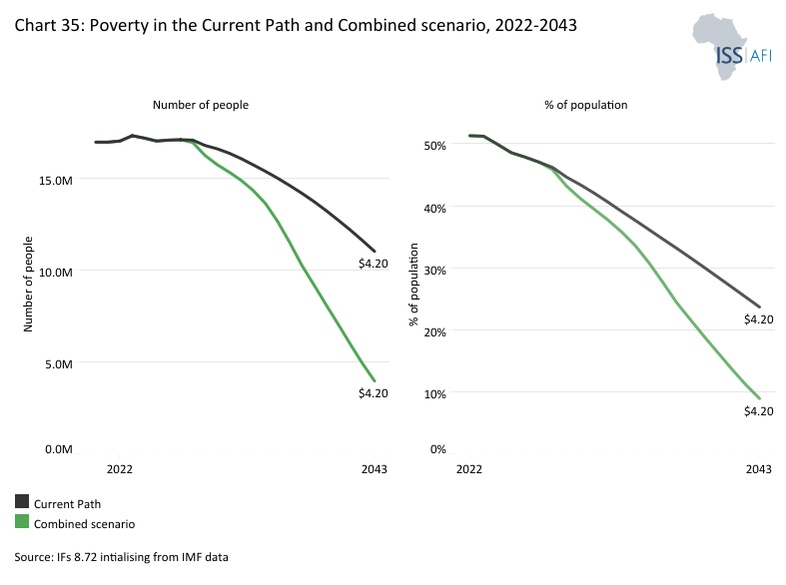
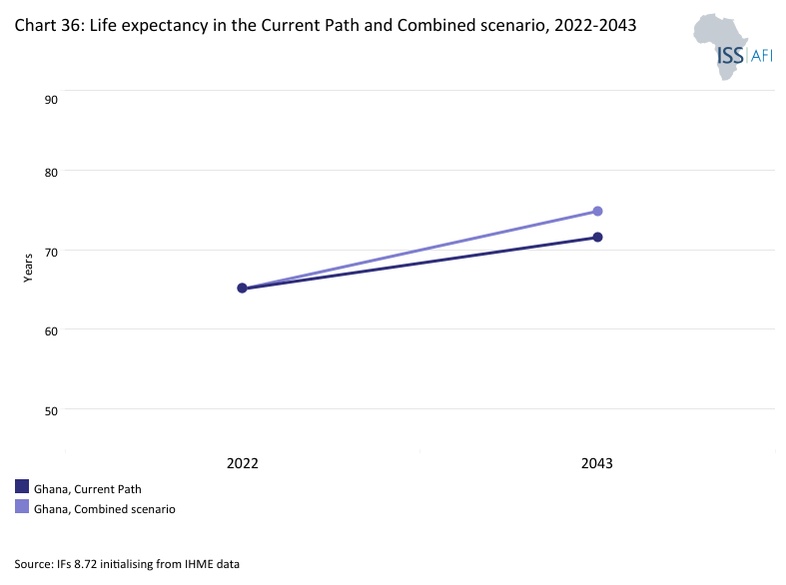
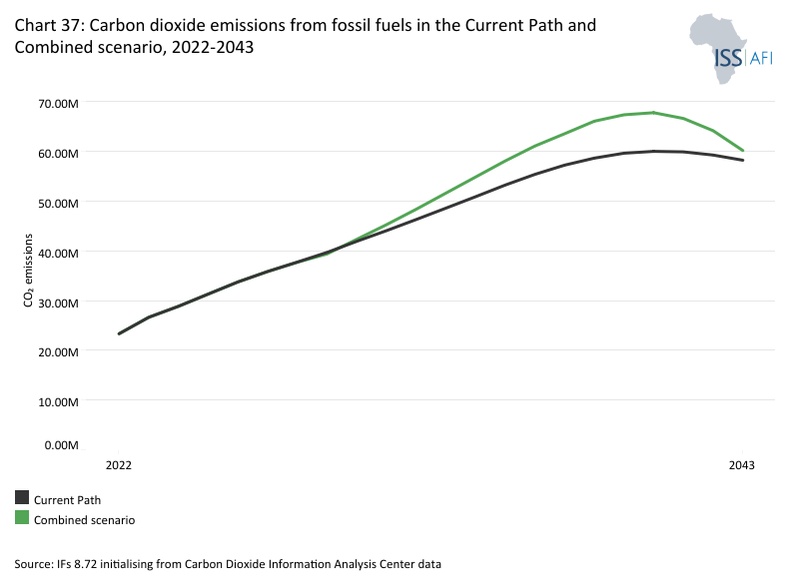
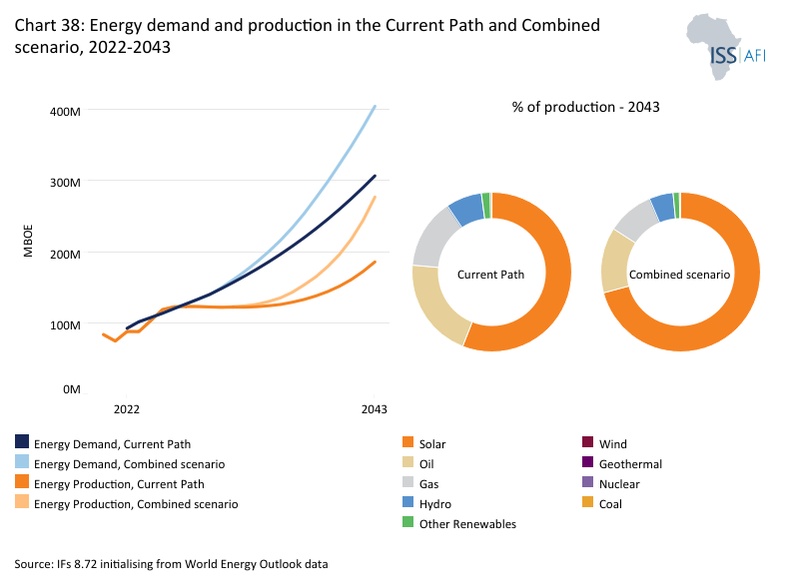

Chart 1 is a political map of Ghana.
Ghana is a lower-middle-income country located in West Africa along the Gulf of Guinea. It shares borders with Burkina Faso to the north, Côte d’Ivoire to the west, and Togo to the east, all of which are members of the Economic Community of West African States (ECOWAS). The national capital, Accra, is situated in the Greater Accra Region in the southern part of the country. Ghana covers a total area of 238 535 km² and experiences a tropical climate characterised by two main seasons: the rainy season and the dry season.
The country is divided into six ecological zones: the Sudan savannah, Guinea savannah, Coastal savannah, forest-savannah transitional zone, deciduous forest zone, and rainforest zone. Ghana is richly endowed with natural resources, including gold, bauxite, diamonds, timber, manganese, and oil. In addition, it remains one of the world’s leading cocoa producers and continues to rely heavily on agriculture, mining, and the services sector as pillars of its economy. Administratively, Ghana is divided into 16 regions and 261 districts following a 2019 referendum that increased the number of regions from 10 to 16.
Since gaining independence from British colonial rule in 1957, Ghana has experienced alternating periods of military and democratic governance, including four successful military coups and several attempted coups. Upon independence, Kwame Nkrumah, leader of the Convention People’s Party (CPP), became Prime Minister while the British monarch remained Head of State. In 1960, Ghana became a republic, making Nkrumah both Head of State and Head of Government. However, his administration was overthrown in a military coup on 24 February 1966, bringing the First Republic to an end. The coup was led by Colonel E.K. Kotoka, Major A.A. Afrifa, Lieutenant General J.A. Ankrah, and Police Inspector General J.W.K. Harlley. Following the coup, the National Liberation Council (NLC) assumed power under the leadership of Joseph Ankrah.
The NLC governed for three years before overseeing a transition back to civilian rule through the 1969 general elections. The Progress Party (PP), led by Kofi Abrefa Busia, won the elections, establishing the Second Republic with Busia as Prime Minister and Edward Akufo-Addo as President. However, this government was overthrown on 13 January 1972 in a coup led by Colonel Ignatius Kutu Acheampong. Acheampong subsequently established the National Redemption Council (NRC), which later became the Supreme Military Council (SMC) in 1975. In July 1978, Acheampong was replaced in a palace coup by General F.W.K. Akuffo.
On 4 June 1979, a group of young military officers led by Flight Lieutenant Jerry John Rawlings overthrew the SMC and established the Armed Forces Revolutionary Council (AFRC). The AFRC supervised elections later that year, which brought the People’s National Party (PNP) to power and inaugurated the Third Republic under President Hilla Limann. However, Limann’s administration was short-lived, as Rawlings again seized power in a coup on 31 December 1981. Rawlings then established the Provisional National Defence Council (PNDC), marking the beginning of the longest period of military rule in Ghana’s history.
By 1991, Rawlings agreed to a democratic transition, which led to the adoption of a new constitution in 1992. The constitution introduced multiparty democracy and paved the way for the establishment of the Fourth Republic in 1993. Since then, Ghana has consolidated its democratic system and successfully conducted eight consecutive presidential and parliamentary elections every four years. These elections have resulted in peaceful transfers of power between the two dominant political parties: the New Patriotic Party (NPP) and the National Democratic Congress (NDC), a democratic achievement widely recognised both domestically and internationally. Ghana is frequently regarded as one of the most stable democracies in Africa and has earned international recognition for its commitment to constitutional governance, electoral integrity, and peaceful political transitions.
Since the beginning of the Fourth Republic, Ghana has had six presidents: Jerry John Rawlings of the NDC (1993–2000), John Agyekum Kufuor of the NPP (2001–2008), John Evans Atta Mills of the NDC (2009–2012 - who died in office on July 2012 before completing his tenure in January 2013), John Dramani Mahama of the NDC (2012–2016), Nana Addo Dankwa Akufo-Addo of the NPP (2017–2024), and John Dramani Mahama again following his re-election in the 2024 general elections and inauguration in January 2025. The Fourth Republic is therefore regarded as the most stable, enduring, and successful republic in Ghana’s political history.
Since 1992, the political party that has won the presidential election has generally also secured a parliamentary majority, with the notable exception of the 2020 general elections. In that election, both the NDC and the NPP won 137 parliamentary seats each, while one independent candidate held the deciding seat, resulting in a hung parliament. However, the 2024 general elections restored the pattern of unified executive and legislative control. In the presidential election held on 7 December 2024, former President John Dramani Mahama of the NDC defeated Vice President Mahamudu Bawumia of the NPP and returned to office after eight years in opposition. The election also produced a decisive parliamentary victory for the NDC, giving the party a clear majority in Parliament and ending the NPP’s eight-year administration under President Akufo-Addo.
By 2026, Ghana continued to face several governance and socio-economic challenges, including public debt, youth unemployment, inflationary pressures, illegal mining, and concerns over corruption and environmental degradation. Nevertheless, the country remained an influential political and economic actor within West Africa and ECOWAS, playing an active role in regional diplomacy, peacebuilding, and democratic governance initiatives across the continent.
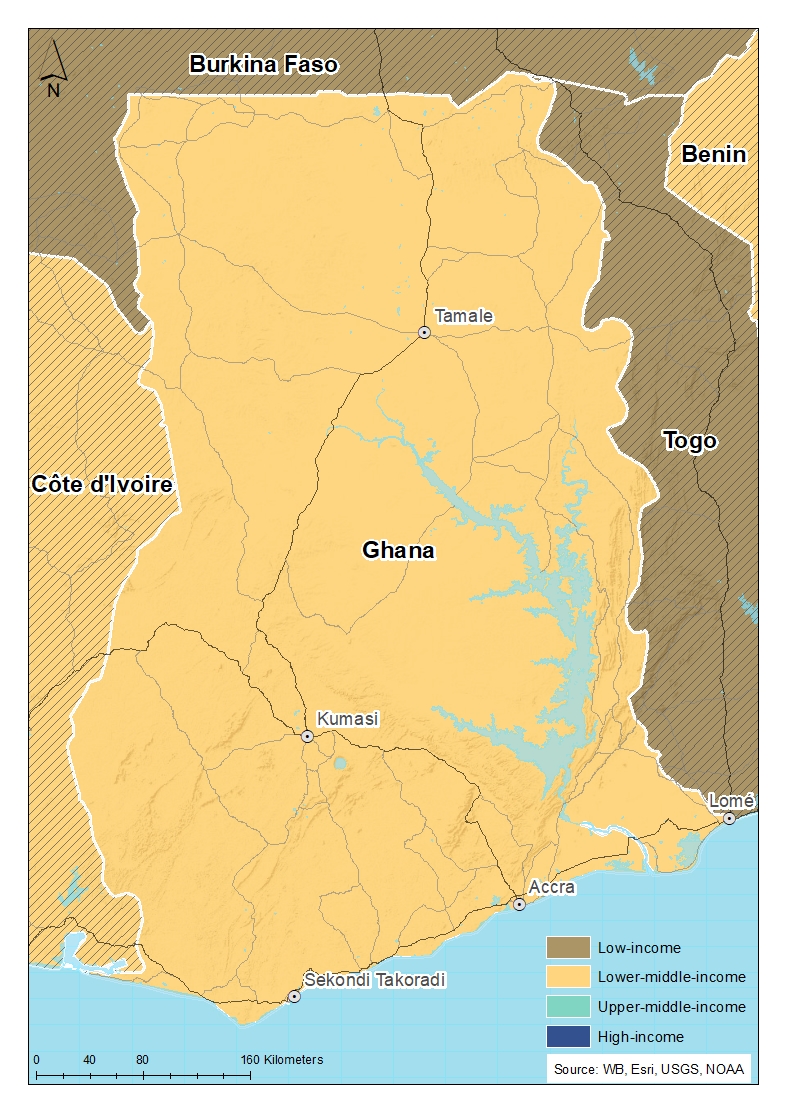
Chart 2 presents the Current Path of the population structure, from 2019 to 2043.
A country's population characteristics play a crucial role in shaping its long-term social, economic and political foundations. Therefore, analysing a nation's demographic profile provides valuable insight into its development potential.
As of 2025, Ghana was the second-most populous country in West Africa, after Nigeria, and the 14th-most populous in Africa. The country’s population increased significantly from approximately 15.4 million in 1990 to an estimated 35 million in 2025, reflecting sustained demographic growth driven largely by relatively high fertility rates and improvements in life expectancy and healthcare outcomes. In 2025, Ghana’s total fertility rate was estimated at 3.3 births per woman, which remained significantly above the population replacement level of 2.1 births per woman. At the same time, life expectancy increased to 66 years, compared to about 56.2 years in the early 1990s.
Although Ghana continues to experience relatively strong demographic growth, the annual population growth rate declined from approximately 2.5% in the early 1990s to around 1.9% in the early 2020s. This gradual slowdown has been partly driven by increased access to and use of modern contraceptives, rising levels of education, urbanisation, and changing household economic preferences.
Under the Current Path scenario, Ghana’s population is projected to increase to approximately 46.5 million by 2043, with an average annual growth rate of 1.6% between 2026 and 2043. Although population growth is expected to moderate over time, demographic expansion will continue to shape the country’s long-term development trajectory. The total fertility rate is projected to decline to 2.5 births per woman, while life expectancy is expected to rise to 71.5 years by 2043.
Rapid population growth presents both opportunities and challenges for Ghana. While a growing population can expand the labour force and domestic market, insufficient economic growth and limited job creation can place considerable pressure on public resources and social services. Ghana’s population growth rate has often outpaced the expansion of economic opportunities, contributing to rising youth unemployment, strains on healthcare and education systems, housing shortages, and increased demand for infrastructure and basic services. Consequently, these pressures can adversely affect living standards, human development outcomes, and the country’s broader socio-economic transformation agenda.
Ghana’s evolving population structure carries significant implications for the country’s long-term economic and social development. In 2025, approximately 35.4% of the population was under 15 years old, 60.7% was 15–64 years (working age), and 3.9% was aged 65 years and above. This represents a notable demographic shift from the structure observed in 1990, when 45.3% of the population was under 15, 52.1% was of working age, and only 2.6% was aged 65 years and older.
The gradual expansion of the working-age population relative to dependants reflects Ghana’s demographic transition from a predominantly youthful population towards a more mature demographic profile, creating a window for potential. When the ratio of the working-age population to dependants (children under 15 and the elderly aged 65+) reaches a ratio of 1.7 to 1 or higher, countries often experience accelerated economic growth known as the demographic dividend. This occurs because a larger labour force can enhance production, increase household savings, expand the tax base, and reduce the economic burden of supporting dependants, particularly when the workforce is adequately educated, skilled, and productively employed.
Evidence from the East Asian economic miracle illustrates this potential, with studies attributing roughly one-third of the region’s economic growth to its large working-age population and relatively low dependency burden. However, a growing working-age population does not automatically translate into economic growth. The benefits of the demographic dividend depend on whether the labour force acquires relevant skills and whether the economy can generate sufficient productive employment opportunities.
Despite these prospects, Ghana continues to face significant structural and institutional challenges. In the 2025 Human Development Index (HDI) report, Ghana is classified as a medium human development country, with an HDI score of around 0.63 and a global ranking of 143rd out of 191 countries, performing better than many of its income-group peers. Nonetheless, these indicators also highlight the need for sustained investments in human capital, job creation, and institutional development to achieve inclusive and sustainable growth.
In 2025, the country’s working-age-to-dependant ratio was estimated at 1.54:1, meaning there were 1.54 working-age individuals for every dependant. Under the Current Path scenario, Ghana is projected to enter the window of opportunity for its first demographic dividend by 2034, with the ratio expected to increase further to 1.81:1 by 2043.
Ghana’s median age was estimated at 21.3 years in 2025, an increase from 16.1 years in 1990. Under the Current Path, the median age is projected to reach 25.8 years by 2043. Despite this increase, Ghana remains a relatively youthful society. The country’s youth bulge, defined as the proportion of the population aged 15 to 29 relative to the total adult population, stood at approximately 42.1% in 2025, down from 51.4% in 1990. A large youth population can represent both a significant opportunity and a potential source of socio-economic pressure. On the one hand, a youthful population can contribute to innovation, entrepreneurship, political participation, and long-term labour force expansion, thereby supporting economic transformation and democratic renewal. On the other hand, where economic growth fails to generate sufficient employment opportunities, a large youth bulge may increase the risk of social discontent, political instability, crime, and violent conflict.
In Ghana’s case, persistent concerns over youth unemployment and underemployment remain a major policy challenge. The labour market's inability to absorb the growing number of young people entering the workforce each year raises important concerns about economic inclusion, productivity, and social cohesion. Without sustained investment in job creation, skills development, industrialisation, and private sector growth, the country risks underutilising a significant share of its human capital potential.
According to the 2023 Ghana Human Development Report, youth unemployment remains a major socio-economic challenge, with approximately 65% of Ghanaians aged 15-24 reported to be unemployed. Similarly, the World Bank estimates indicate that more than half of Ghana’s youth population is unemployed.
With such high levels of unemployment, it is not surprising that the country has witnessed several protests in recent years. One notable example was the Fix-the-Country-Movement a youth-led protest movement that emerged to demand improved economic governance, job creation, better public services, and government intervention to address rising unemployment and the escalating cost of living in Ghana.
Chart 3 presents a population distribution map for 2023.
Ghana has a total land area of approximately 238 533 km² and remains one of the most densely populated countries in both West Africa and the continent more broadly. In 2025, it ranked fourth among West African countries by population density and 12th in Africa. The country’s population density was estimated at 1.5 persons per hectare, nearly three times the continental estimated average of 0.5 persons per hectare, reflecting increasing demographic pressure on land, infrastructure, and public services.
Population distribution in Ghana is closely associated with patterns of economic activity and spatial development. The bulk of the population is concentrated in the southern growth corridor, particularly within the Accra–Kumasi–Takoradi triangle south of the Kwahu Plateau. This area constitutes the country’s principal economic zone, hosting major commercial centres, industrial activities, mining operations, cocoa-producing regions, and timber resources. Its relatively advanced transport infrastructure, including road and rail networks linking inland production centres to coastal ports, has strengthened regional integration, labour mobility, trade, and private investment flows.
Although the Northern Region remains the largest in terms of land area, the Greater Accra Region is the most populous and economically dynamic region, followed by the Ashanti Region, whose capital, Kumasi serves as a major commercial hub. The concentration of population in southern Ghana also reflects historical migration dynamics, including cross-border refugee inflows during periods of instability in neighbouring countries such as Liberia and Togo.
Looking ahead, Ghana’s population density is projected to rise to approximately 2 persons per hectare by 2043, significantly above the projected averages of 1.4 and 0.8 persons per hectare for West Africa and Africa. This trend is likely to intensify demand for employment, housing, urban infrastructure, land, and social services, underscoring the importance of spatial planning, productivity-enhancing investments, and balanced regional development policies.
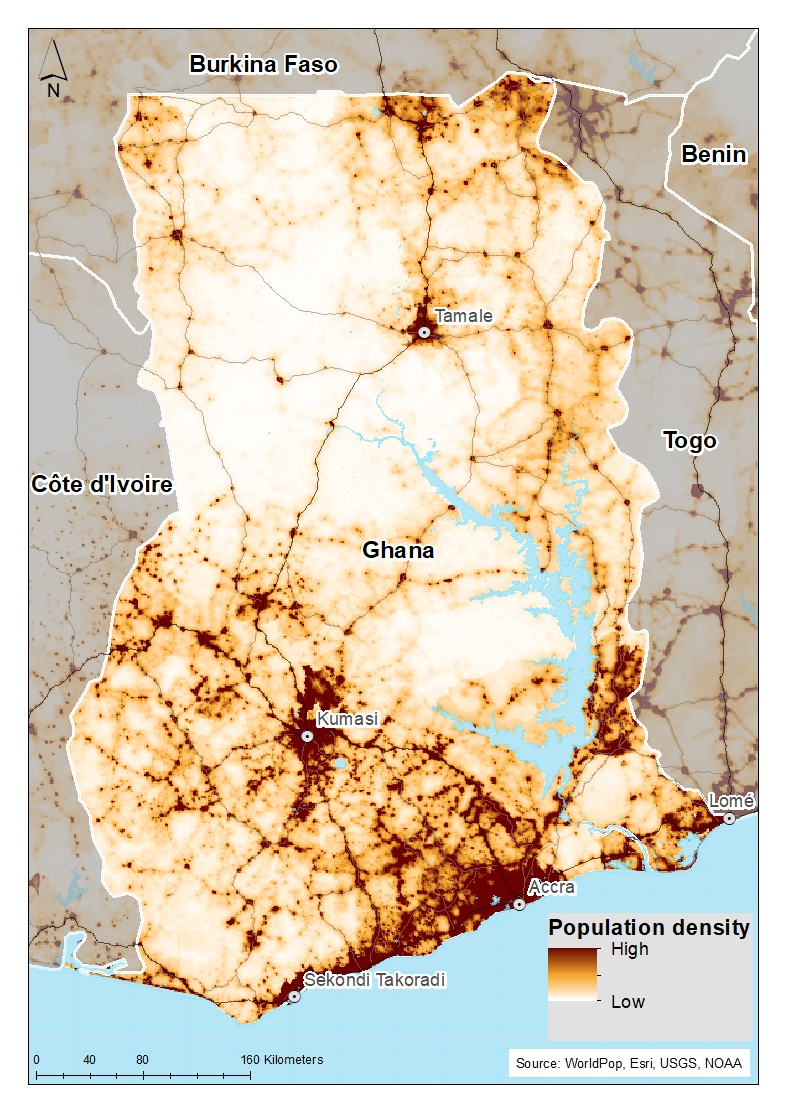
Chart 4 presents the urban and rural population in the Current Path, from 1990 to 2043.
The rapid growth of Ghana’s urban population has been one of the most significant features of the country’s demographic and economic transformation. Over the past three decades, Ghana has urbanised rapidly, reaching parity between its urban and rural populations as early as 2009. In 1990, approximately 36.4% of Ghana’s population lived in urban areas, already exceeding both the African average of 31.5% and the average of 34.3% for African lower-middle-income countries (LMICs). By 2025, the proportion of Ghanaians residing in urban centres had increased to 60.6%, placing the country among the most urbanised nations on the continent. Ghana ranked 16th in Africa, 8th among African LMICs, and 3rd in West Africa after Cabo Verde and Gambia. Over this period, the country urbanised at an average annual rate of about 3.9%, slightly higher than the average urbanisation rate of approximately 3.6% for Africa LMIC and 3.7% for Africa.
Ghana’s urbanisation process has been closely linked to structural transformation, industrialisation, and the spatial concentration of economic activity. In the post-independence period, state-led development strategies promoting industrialisation, economic diversification, and modernisation contributed to the emergence of major urban-industrial hubs such as Accra, Kumasi, and Sekondi-Takoradi, which collectively accounted for the overwhelming majority of industrial activity in the country. The expansion of cocoa production zones, investments in transport infrastructure, and decentralisation policies further stimulated the growth of secondary towns and regional urban centres.
More recently, urbanisation has been driven by three interrelated factors: natural population growth, the reclassification of settlements as urban centres once they exceed 5 000 inhabitants, and, most importantly, sustained rural–urban migration. Rural-urban migration flows are dominated by young people seeking employment, higher incomes, education, and improved access to social services in major metropolitan areas, particularly Accra and Kumasi. This pattern reflects the concentration of formal economic opportunities and public investment in urban regions, especially the Greater Accra Region, which, despite being the smallest region by land area, has become the country’s most populous and economically significant region.
While urbanisation has contributed to economic dynamism, market expansion, and labour agglomeration effects, the pace of urban growth has outstripped the capacity of urban infrastructure and public institutions. In Accra and other rapidly growing cities, this has resulted in rising housing deficits, the proliferation of informal settlements and slums, traffic congestion, pressure on transport and sanitation systems, environmental degradation, and persistent youth unemployment and underemployment. These challenges underscore the need for integrated urban planning, investment in productive infrastructure, affordable housing, and policies that promote inclusive urban growth and balanced regional development.
Chart 5 presents GDP in 2021 market exchange rates (MER) dollars and growth rate in the Current Path, from 1990 to 2043.
Ghana’s economy is heavily commodity-dependent, with gold, cocoa, and crude oil serving as the country’s principal export earners. Ghana is one of the world’s leading producers of cocoa and gold. This commodity dependence has often contributed to fiscal instability and balance-of-payments pressures during periods of declining export prices.
The country’s economy, measured in market exchange rate (2021 MER) terms, expanded significantly from approximately US$15.9 billion in 1990 to about US$95.2 billion in 2025, recording an average annual growth rate of roughly 5.2%. This growth rate was considerably higher than the average of 3.9% recorded by Africa’s LMICs over the same period. The country’s relatively strong economic performance reflects several interrelated factors, including sustained political stability under the Fourth Republic since 1992, which has created a more predictable environment for investment, trade, and economic planning compared to earlier periods of political instability.
Economic growth was also supported by a series of market-oriented and internationally supported reform programmes aimed at stabilising the macroeconomy, improving public sector management, liberalising markets, and promoting private sector development. These reforms included the Structural Adjustment Programmes (SAPs) and Economic Recovery Programmes implemented in the 1980s and 1990s, as well as debt relief initiatives such as the Highly Indebted Poor Countries (HIPC) programme. In addition, Ghana benefited from development frameworks and international partnerships linked to the Millennium Development Goals (MDGs), the Sustainable Development Goals (SDGs), and the African Union’s Agenda 2063, all of which contributed to investments in infrastructure, human capital development, poverty reduction, and institutional reforms aimed at supporting long-term economic transformation.
In addition to internationally supported reforms, Ghana has implemented several medium-term national development frameworks aimed at promoting macroeconomic stability, inclusive growth, poverty reduction, and structural transformation. These include the Ghana Poverty Reduction Strategy (GPRS I & II, 2003–2009), the Ghana Shared Growth and Development Agenda (GSGDA I & II, 2010–2017), and the Agenda for Jobs: Creating Prosperity and Equal Opportunity for All (2018–2025). Collectively, these policy frameworks prioritised infrastructure development, human capital investment, private sector expansion, employment creation, and improved economic governance.
Another major factor that strengthened Ghana’s economic performance was the discovery and subsequent commercial production of crude oil. Oil production, which commenced in 2011, significantly boosted export revenues, foreign direct investment (FDI), and government income. In that year, Ghana recorded an exceptional GDP growth rate of approximately 14.1%, one of the highest in the world at the time, largely driven by the expansion of the petroleum sector.
However, this exceptional growth was not sustained, with the growth rate declining sharply in subsequent years. From 2015 to 2025, Ghana’s economic growth followed a more uneven trajectory, marked by periods of recovery and slowdown, including a significant downturn during the COVID-19 pandemic and further pressures during the post-pandemic period of high inflation and macroeconomic instability.
The combined impact of economic reforms, development planning, and resource-based growth contributed to sustained economic expansion over the past two decades. It supported Ghana’s transition to lower-middle-income country status in 2010. Before the COVID-19 pandemic, Ghana was widely regarded as one of Africa’s strongest-performing economies and, in 2019, the International Monetary Fund (IMF) projected it to be the fastest-growing economy in the world.
Despite these periods of strong economic growth, Ghana’s underlying economic structure remains relatively weak and insufficiently transformed. The economy continues to rely heavily on the production and export of primary commodities, particularly gold and cocoa, while depending extensively on imported manufactured and processed goods. This pattern reflects the country’s limited industrial diversification and weak value addition within domestic production systems. With the exception of the state-led industrialisation efforts of the 1960s, successive development strategies have achieved only modest progress in restructuring the economy towards higher-productivity manufacturing and industrial activities. As a result, Ghana remains vulnerable to both domestic and external economic shocks.
Sustaining Ghana’s long-term sustainable economic growth will require deeper structural transformation, particularly a shift in economic activity and employment from low-productivity sectors towards higher-productivity and higher-value-added activities. Expanding manufacturing, agro-processing, modern services, and other productive industries would help diversify the economy, reduce its dependence on primary commodities, raise productivity, and generate more productive and decent employment opportunities for Ghana’s growing workforce. On the Current Path, Ghana’s economy is projected to expand significantly, with GDP increasing threefold from its 2025 level to approximately US$298.5 billion by 2043. This projected expansion reflects forecast sustained improvements in economic activity, investment, and productivity, underpinned by an average annual GDP growth rate of about 6.6% between 2026 and 2043.
Chart 6 presents the size of the informal economy as per cent of GDP and per cent of total labour (non-agriculture), from 2020 to 2043. The data in our modelling are largely estimates and therefore may differ from other sources.
Another key feature of Ghana’s economy is the dominance of the informal sector. Ghana’s economy is characterised by a large informal sector, which plays a critical role in employment generation, income creation, and household livelihoods. A large proportion of the labour force is employed in informal activities such as petty trading, small-scale agriculture, transport services, and artisanal enterprises. While the informal economy provides livelihoods for millions and supports household incomes, especially unskilled labourers, it is generally characterised by low productivity, limited access to credit, weak social protection, and low tax compliance. This constrains domestic revenue mobilisation and limits the pace of industrial and technological transformation.
Ghana’s informal sector accounts for approximately 62% of all commercial activity. In 2025, the sector was estimated to contribute about 28.9% of GDP, broadly comparable to the estimated average of 30.1% for Africa’s LMICs.
In 2025, approximately 47.7% of Ghana’s share of total labour force (non-agriculture) was employed in the informal sector, slightly below the estimated average of 55.9% for Africa’s LMICs. In Ghana, the sector is often characterised by illiterate or semi-literate people and persons with no formal training. Their skills are usually acquired through apprenticeships and from family. Among these people, the majority are women, followed by men and children. Most employees in the informal sector are paid below the national minimum wage and receive no social security benefits. This is mainly due to excess labour supply and a lack of skills that may attract higher wages.
To promote the formalisation of the informal sector, the government has implemented a range of policies to reduce barriers to business registration, improve the business environment, and expand access to financial services. A central component of these reforms has been the digitalisation of the economy through initiatives such as the digital property addressing system, the paperless port system, mobile payment interoperability platforms, and the rollout of national identification cards. These measures are intended to improve administrative efficiency, reduce transaction costs, strengthen regulatory oversight, and facilitate the integration of informal enterprises into the formal economy.
The government has also expanded access to financial services through the rapid growth of mobile money platforms and enhanced mobile money interoperability, which have significantly improved financial inclusion among informal sector workers and small enterprises. Increased access to digital financial services has supported savings mobilisation, business transactions, and access to credit, particularly for previously unbanked populations.
In addition, efforts to streamline administrative procedures and reduce bureaucratic constraints associated with business registration have been introduced to encourage informal enterprises to formalise their operations. By lowering compliance costs and improving the ease of doing business, these reforms aim to broaden the tax base, enhance productivity, improve labour conditions, and strengthen domestic revenue mobilisation over the long term.
On the Current Path, the size of Ghana’s informal economy is projected to decline gradually to approximately 25.3% of GDP by 2043, falling below the forecast average of 27.8% for Africa’s LMICs. The share of the labour force employed in the informal sector is expected to decline to about 44.5% over the same period.
This projected contraction of the informal sector suggests gradual structural transformation within the economy, driven by improvements in business formalisation, financial inclusion, digitalisation, and the expansion of formal sector employment opportunities. A smaller informal share of economy is likely to strengthen domestic revenue mobilisation by broadening the tax base, improving regulatory compliance, and increasing the proportion of economic activity captured within formal administrative systems. Over time, this could enhance the government’s fiscal capacity to finance infrastructure, social services, and long-term development priorities.
Chart 7 presents GDP per capita in the Current Path, from 1990 to 2043, compared with the average for the Africa income group.
According to the World Bank’s income classification, Ghana attained LMIC status in 2010 following a GDP rebasing by the Ghana Statistical Service. The rebasing updated the base year for national accounts calculations from 1993 to 2006, leading to a substantial upward revision in the estimated size of the economy. Consequently, Ghana’s Gross National Income (GNI) per capita exceeded the World Bank's threshold for low-income economies, leading to its official reclassification as a lower-middle-income country. The rebasing exercise also highlighted significant structural changes within the economy by capturing the growing contribution of previously underrepresented sectors, particularly services, telecommunications, construction, and financial services.
In 2025, Ghana recorded a GDP per capita of 6 949 (2021 PPP), up significantly from US$2 786 in 1990. This substantial increase reflects sustained economic growth and the upward revision associated with GDP rebasing, reinforcing Ghana’s position among the eight leading LMICs in Africa in terms of per capita income.
On the Current Path, Ghana’s GDP per capita is projected to increase to US$12 084 by 2043, reflecting continued economic expansion and rising average incomes. At this level, the country’s GDP per capita would exceed the projected regional average of US$10 480 for LMICs in Africa.
Chart 8 presents the rate and number of poor people in the Current Path from 2020 to 2043.
In 2025, the World Bank updated the poverty lines to 2021 constant dollar values as follows:
- The previous US$2.15 extreme poverty line is now set at US$3, also for use with low-income countries.
- US$3.65 for lower-middle-income countries, now US$4.20 in 2021 values.
- US$6.85 for upper-middle-income countries, now US$8.30 in 2021 values.
- US$22.70 for high-income countries. The Bank has not yet announced the new poverty line in 2017 US$ prices for high-income countries.
As a LMIC, the international poverty line of US$4.20 per person per day (2021 PPP) applies to Ghana. Based on this threshold, an estimated 48.6% of the population—approximately 17 million people—lived in poverty in 2025, slightly above the estimated average of 45.7% for LMIC in Africa. Under the Current Path scenario, the poverty rate is projected to decline significantly to 23.7% by 2043, reflecting anticipated improvements in economic growth, household incomes, and social welfare outcomes.
Using the extreme poverty threshold of US$3 per person per day (2021 PPP), 32.3% of Ghanaians were classified as extremely poor in 2025, marking a substantial decline from 79.1% in 1990. Under the Current Path scenario, the extreme poverty rate is forecast to decline significantly to 12.6% by 2043.
These reductions underscore the impact of sustained poverty alleviation and social protection interventions implemented over the past three decades. Key among these was the Ghana Poverty Reduction Strategy (GPRS), which expanded access to free compulsory basic education, introduced the National Health Insurance Scheme, and provided free maternal healthcare services. In addition, the Livelihood Empowerment Against Poverty (LEAP) programme, launched in 2008, has played a critical role in supporting extremely poor and vulnerable households through targeted cash transfers, thereby improving household resilience and reducing extreme deprivation.
In addition to government-led interventions, private organisations and non-governmental organisations (NGOs) have also played an important role in poverty reduction and inclusive development in Ghana. One notable example is Opportunity International, which promotes poverty alleviation through expanded access to agricultural finance and education funding. Through the provision of agricultural loans, particularly in the cocoa sector, the organisation supports smallholder farmers in increasing productivity and improving household incomes. These initiatives are especially significant for women, who constitute a key component of agricultural livelihoods in many rural communities.
Complementary training in modern farming techniques and income diversification has further strengthened the resilience of farming households, while mobile banking services have improved financial inclusion by extending access to credit and savings facilities in underserved rural areas. In the education sector, the Edu-Finance initiative has enhanced access to affordable private schooling by enabling low-income families to finance school fees and supporting improvements in educational quality. These interventions have contributed to higher school enrolment rates, improved learning outcomes, and stronger human capital development. Collectively, such initiatives support income generation, expand economic opportunities, and help break the intergenerational cycle of poverty in Ghana.
Monetary poverty, however, captures only part of the picture. The global Multidimensional Poverty Index (MPI) provides a broader assessment by measuring overlapping deprivations across ten indicators within three equally weighted dimensions: health, education and living standards. The MPI complements the international extreme poverty line of US$3 per day by identifying who is multidimensionally poor and highlighting the different forms of deprivation they experience. According to the 2025 Global Multidimensional Poverty Index report, 24.8% of Ghana’s population was multidimensionally poor in 2022, with a further 20% considered vulnerable to falling into multidimensional poverty.
Inequality remains a persistent structural challenge in Ghana, with income and wealth disparities remaining pronounced despite sustained economic growth. This places the country among the more unequal economies in sub-Saharan Africa, reflecting the uneven distribution of the gains from economic growth. According to the 2024 Global Inequality data published by the World Inequality Lab, the top 10% of the Ghanian population holds around 62% of the country’s wealth. In contrast, the bottom 50% of the population captures only about 2% of Ghana’s national income.
Chart 9 depicts the National Development Plan.
Ghana has formulated several long-term national development frameworks, typically operationalised through successive four-year medium-term development plans. One of the earliest of these was the Vision 2020 strategy, which served as the country’s overarching framework for socio-economic transformation and development. The strategy was implemented through a series of medium-term plans to promote economic growth, structural transformation, and improved living standards.
However, following the completion of the First Medium-Term National Development Plan, Ghana shifted away from the Vision 2020 framework after attaining Highly Indebted Poor Country (HIPC) status. This transition redirected policy priorities toward poverty reduction and macroeconomic stabilisation. Consequently, the government adopted the Ghana Poverty Reduction Strategy (GPRS I) for 2003–2005 and the Growth and Poverty Reduction Strategy (GPRS II) for 2006–2009 as the country’s principal medium-term development frameworks. Since then, Ghana has developed and implemented four successive medium-term national development plans:
- The Ghana Shared Growth and Development Agenda (GSGDA I, 2010-2013)
- The Ghana Shared Growth and Development Agenda (GSGDA II, 2014-2017)
- Agenda for Jobs: Creating Prosperity and Equal Opportunity For All, 2018-2021
- Agenda for Jobs: Creating Prosperity and Equal Opportunity For All II, 2012-2025
Ghana’s current long-term development framework, Vision 2057, outlines the country’s strategic aspirations for socio-economic and environmental transformation by the centenary of its independence in 2057. The framework reflects the collective development ambitions of the Ghanaian people. It sets out a pathway toward inclusive growth, structural transformation, improved living standards, and sustainable development over the long term.
Vision 2057 builds on several earlier national planning frameworks, including the Black Star Rising: Long-Term National Development Plan (2018–2057), commonly referred to as the 40-Year Development Plan, Ghana @100, and the National Development Policy Framework (Vision 2020). It is also aligned with broader continental and global development agendas, notably the African Union’s Agenda 2063 and the United Nations Sustainable Development Goals (SDGs).
In addition, the framework incorporates lessons from recent global and domestic shocks, including the socio-economic effects of the COVID-19 pandemic, the growing risks associated with climate change, and emerging geopolitical uncertainties affecting the global economy. Vision 2057 is intended to be implemented through successive medium-term national development plans, allowing future governments the flexibility to determine specific policy actions, programmes, and investment priorities in line with evolving development challenges and opportunities.
The vision underpinning Vision 2057 is to build ‘a free, just, prosperous, and self-reliant nation that secures the welfare and well-being of its citizens while playing a leading role in international affairs.’ Central to this ambition is the objective of improving the quality of life and living standards of Ghanaians, while transitioning the country toward upper-middle-income status through sustained economic transformation and inclusive development. This vision and overarching development goal are anchored on the following key drivers of transformation:
- Achieving and maintaining macroeconomic stability.
- Enabling attitudinal culture for sustainable social cohesion.
- Peace and security.
- Effective and efficient public service and institutional strengthening.
- Human capital development for improved productivity.
- Science, technology and innovation.
- Effective land reforms.
- Sustainable infrastructure development and
- Clean, affordable and sustainable energy transitional trajectory.
To effectively monitor progress toward its overarching development objectives, Vision 2057 is structured around five broad thematic dimensions: economic development, social development, the natural and built environment, governance, and emergency preparedness and resilience. Each dimension is supported by clearly defined objectives, measurable targets, and strategic policy interventions designed to drive sustainable and inclusive national development.
The eight sectoral scenarios as well as their relationship to the Current Path and the Combined scenario are explained in the About Page. Chart 10 summarises the approach.
Chart 11 presents the mortality distribution in the Current Path for 2023 and 2043.
Population dynamics and health outcomes are closely interconnected. Improvements in healthcare, nutrition, sanitation, and access to essential services can reduce mortality and morbidity, increase life expectancy, and influence fertility patterns. At the same time, population growth and changing demographic structures place additional pressure on healthcare systems and increase demand for basic services such as adequate nutrition, clean water, sanitation, and housing.
Beyond demographic effects, health is an important determinant of human capital development and economic performance. A healthy population is better able to participate effectively in education and the labour market, while poor health can constrain productivity through absenteeism, disability, premature mortality, and reduced physical and cognitive capacity. Health conditions during childhood are particularly important, as adequate nutrition, disease prevention, and access to quality healthcare contribute to physical and cognitive development, educational attainment, and future earning potential.
These relationships are particularly important for Ghana as its working-age population expands. The extent to which the country can translate its demographic transition into a demographic dividend will depend on its ability to develop a healthy, educated, and skilled workforce while creating sufficient productive employment opportunities. Persistent gaps in healthcare access, nutrition, and disease prevention could undermine these gains by limiting educational outcomes, labour productivity, and household incomes.
Strengthening Ghana’s health system should therefore be viewed not only as a social priority but also as an investment in the country’s long-term development. Improved access to quality healthcare, preventive services, nutrition, and sanitation can strengthen human capital, enhance productivity, and support more inclusive and sustained economic growth.
The Demographics and Health scenario, therefore, envisions ambitious improvements in child and maternal mortality rates, enhanced access to modern contraception, and decreased mortality from communicable diseases (e.g., AIDS, diarrhoea, malaria, respiratory infections) and non-communicable diseases (e.g., diabetes), alongside advancements in safe water access and sanitation. This scenario assumes a swift demographic transition supported by heightened investments in health and water, sanitation and hygiene (WaSH) infrastructure.
Visit the themes on Demographics and Health/WaSH for more details on the scenario structure and interventions.
Over the past decade, Ghana has made notable progress in expanding access to healthcare and strengthening health service delivery. The country has increased the coverage of health facilities, while the number of doctors and nurses per capita has steadily improved. In parallel, the government has promoted Community-based Health Planning and Services (CHPS) to enhance the delivery of primary healthcare at the community level, particularly in underserved and rural areas.
A major milestone in Ghana’s health sector reforms was the establishment of the National Health Insurance Scheme (NHIS) in 2003, aimed at improving financial access to essential healthcare services for residents. The scheme was subsequently expanded to include free maternal healthcare in 2008 and free mental healthcare services in 2012. Since its introduction, the NHIS has contributed significantly to increased healthcare utilisation, including higher outpatient visits per capita and improved access to basic health services.
Despite these achievements, substantial challenges remain in ensuring equitable healthcare access and quality outcomes across the country. Significant regional and socio-economic disparities persist in the distribution of healthcare infrastructure, medical personnel, and NHIS coverage. Urban and wealthier populations generally have greater access to healthcare services than poorer and rural communities. Consequently, women from low-income households are more likely to give birth outside formal health facilities, while under-five mortality rates remain disproportionately high among poorer populations.
The NHIS also faces operational and financial sustainability challenges. Delayed reimbursements and inadequate public financing have contributed to service disruptions and the emergence of informal charges, undermining access and affordability for vulnerable groups. In addition, the quality of healthcare delivery continues to be constrained by weak administrative systems, inadequate medical equipment, shortages of essential medicines, and inconsistent adherence to clinical protocols. Ghana’s heavy dependence on imported pharmaceuticals and medical technologies further exacerbates supply vulnerabilities, particularly within public health facilities.
The health sector has also experienced increasing workforce pressures in the aftermath of the COVID-19 pandemic, marked by the large-scale emigration of skilled health professionals. Many Ghanaian nurses and doctors have migrated to countries such as the United Kingdom, the United States, and Canada in search of better remuneration and working conditions. In 2022 alone, more than 1 200 Ghanaian nurses joined the UK nursing register. This growing health-sector brain drain has placed additional strain on the country’s capacity to deliver quality healthcare services.
In response to these challenges, the government has committed to increasing healthcare expenditure to address infrastructure deficits and workforce shortages. Ghana has also adopted a roadmap toward achieving Universal Health Coverage (UHC) by 2030, with a strong emphasis on primary healthcare and community-based service delivery. Central to this strategy is the expansion of the CHPS programme, which decentralises primary healthcare services to more accessible community settings. Currently, more than 6 500 CHPS compounds are operational nationwide, contributing to improved rural healthcare access, greater equity in service delivery, enhanced intersectoral coordination, and improved health system efficiency.
Additionally, the government has launched the Agenda 111 initiative, an ambitious infrastructure programme aimed at constructing 101 district hospitals, seven regional hospitals, two psychiatric hospitals, and redeveloping the Accra Psychiatric Hospital. The initiative seeks to strengthen healthcare infrastructure and ensure broader access to quality healthcare services across all districts and regions of Ghana.
Our modelling adopts the International Classification of Diseases (ICD) framework to analyse the evolving burden of disease and its implications for health sector resource allocation and economic productivity. The analysis categorises mortality into three broad groups: communicable diseases (CDs), non-communicable diseases (NCDs), and injuries. In 1990, CDs accounted for approximately 60.8% of all deaths, reflecting the dominant share of infectious diseases in Ghana's disease burden. NCDs diseases and injuries represented 32.4% and 6.8% of total mortality, respectively. By 2025, however, the mortality profile had shifted considerably, with the share of deaths attributable to CDs declining to 35.2%, while NCDs increased to 53.9% and injuries to 10.8% of total deaths. Cardiovascular and malignant neoplasms diseases emerged as the leading causes of mortality, accounting for an estimated 62 120 and 20 120 deaths, respectively, in 2025.
Ghana reached a critical epidemiological transition in 2017, when mortality from NCDs surpass that from CDs. By 2043, mortality from NCDs is forecast to account for 66.2% of all mortality, while CDs are expected to account for 19.9%. This shift in the disease burden will have significant implications for healthcare financing, labour productivity, and long-term economic growth, as NCDs typically require sustained treatment, long-term care, and greater health system resources. The coexistence of persistent communicable diseases alongside a rising burden of chronic conditions will increase pressure on public health expenditure and healthcare infrastructure. Addressing this dual burden will require strategic investments in healthcare systems, strengthened capacity for chronic disease prevention and management, and expanded access to quality healthcare services. Enhancing preventive healthcare and reinforcing public health institutions will not only improve population health outcomes but also support human capital development, increase workforce productivity, and contribute to Ghana's long-term economic resilience and sustainable development.
Chart 12 presents the infant mortality rate in the Current Path and in the Demographics and Health scenario, from 2020 to 2043.
The infant mortality rate measures the probability that a child born in a given year will die before reaching the age of one. Expressed as the number of infant deaths per 1 000 live births, it is a key indicator of a country’s overall health and socioeconomic development. The rate reflects the broader social, economic, and environmental conditions that influence health outcomes, including household income, nutrition, sanitation, maternal education, and access to quality healthcare services. As a result, infant mortality serves as a widely used proxy for the effectiveness of a country's health system and the inclusiveness of its socio-economic development. Lower infant mortality rates are generally associated with stronger health systems, improved living standards, and greater long-term economic productivity.
Ghana has made significant progress in reducing infant mortality over the past three decades, reflecting improvements in healthcare delivery, human capital development, and overall socio-economic conditions. The infant mortality rate declined from 68.1 deaths per 1 000 live births in 1990 to 29.8 deaths per 1 000 live births in 2025, placing Ghana as the 8th best performer among 24 LMICs in Africa. This decline in infant mortality underscores significant gains in child survival, supported by expanded access to primary healthcare services, improved maternal and child health interventions, and broader immunisation coverage.
Despite this progress, Ghana is projected to narrowly miss the Sustainable Development Goal (SDG) target of reducing infant mortality to fewer than 25 deaths per 1 000 live births by 2030. On the Current Path forecast, the rate is expected to decline to 26.2 deaths per 1 000 live births by 2030 before falling further to 17.2 deaths per 1 000 live births by 2043. Sustaining this progress will require continued investment in maternal and child healthcare, nutrition, sanitation, and preventive health services to strengthen human capital outcomes and support long-term economic growth.
Under the Demographics and Health scenario, Ghana's infant mortality rate is projected to decline more rapidly, reaching 25.5 deaths per 1 000 live births by 2030, narrowly missing the SDG target of fewer than 25 deaths per 1 000 live births. Continued improvements in health outcomes are expected to further reduce the rate to 15.3 deaths per 1,000 live births by 2043, which will be about 1.9 deaths lower than the Current Path projection in the same year. These gains would enhance human capital accumulation by improving child survival, reducing future healthcare costs, and strengthening the productivity potential of future generations.
Chart 13 presents the demographic dividend in the Current Path and in the Demographics and Health scenario, from 2020 to 2043.
The demographic dividend refers to the potential for accelerated economic growth that arises from shifts in a country's age structure, particularly when declining fertility rates and improvements in health increase the share of the working-age population relative to dependants. As the proportion of children and elderly dependants in the population falls, households can increase savings while governments can redirect resources from consumption towards productive investments in education, infrastructure, and technology. This creates opportunities for higher labour productivity, increased capital accumulation, and stronger long-term economic growth.
A country is generally considered to have entered the demographic dividend phase when the ratio of working-age individuals (aged 15–64) to dependants exceeds 1.7:1. However, favourable demographic conditions alone do not guarantee economic gains. Realising the demographic dividend requires complementary policies that expand employment opportunities, improve education and skills development, strengthen governance, and enhance access to essential services. Without these enabling conditions, a growing working-age population may not translate into higher productivity, incomes, or sustained economic growth.
On the Current Path, Ghana is projected to enter its first demographic dividend window by 2034, approximately 15 years earlier than the average forecast for LMICs in Africa. The country's working-age-to-dependant ratio increased from 1.05 in 1990 to an estimated 1.55 in 2025, exceeding the projected Africa LMIC average of 1.4. This reflects steady progress in Ghana's demographic transition, driven by declining fertility rates and improvements in health outcomes.
Under the Demographics and Health scenario, these gains could be accelerated, enabling Ghana to enter the demographic dividend phase by 2033, one year earlier than under the Current Path. This earlier transition would provide an opportunity to unlock additional economic benefits, provided that supportive policies are in place to expand productive employment, enhance skills development, and improve labour market outcomes.
Chart 14 presents crop production and demand in the Current Path from 1990 to 2043.
Agriculture remains central to Ghana’s economy, serving as a major source of income, employment and food security, particularly in the northern regions where significant agricultural potential remains underutilised. The sector contributes about 20% of its GDP, employs over half of the workforce and provides livelihoods for many rural households, making it critical to poverty reduction, economic resilience and inclusive development.
Maize, cassava and yam are among Ghana’s principal food staples and are cultivated by the majority of smallholder farmers across the country. Other important food crops include rice, plantain, sorghum, vegetables and fruits, which play a critical role in food security and rural livelihoods. Livestock production, particularly poultry, cattle, sheep and goats, contributes significantly to household incomes, nutrition and asset accumulation, especially in northern Ghana. Commercial agriculture is dominated by export-oriented commodities such as cocoa, oil palm, cashew and horticultural products, which are important sources of foreign exchange earnings. The country is the world's second-largest producer and exporter of cocoa, behind Côte d'Ivoire.
However, the sector remains vulnerable to climate variability, infrastructure deficits and fluctuations in global commodity prices, all of which affect agricultural productivity, export revenues and broader economic performance. Poor infrastructure, inadequate irrigation systems and increasing climate variability remain among the most pressing challenges. Irregular rainfall patterns, recurrent flooding and prolonged dry spells have heightened production risks, particularly for smallholder farmers who rely heavily on rain-fed agriculture. Although the government launched the One Village, One Dam initiative in 2017 to support year-round farming in northern Ghana, implementation challenges and limited funding have reduced its effectiveness, with many dams proving unable to retain sufficient water during the dry season. Consequently, seasonal water shortages continue to undermine agricultural output, household incomes and rural livelihoods.
Additional constraints include low levels of mechanisation, limited adoption of modern technologies, declining soil fertility and inadequate transport and storage infrastructure, all of which contribute to low agricultural productivity. In recent years, illegal mining (galamsey) has emerged as a major threat to agricultural production, particularly in cocoa-growing areas. The destruction of farmland, soil degradation and water pollution associated with mining activities have adversely affected crop yields and rural livelihoods. According to the Ghana Cocoa Board (COCOBOD), cocoa production has fallen significantly below historical levels, with illegal mining identified as a key contributing factor. In communities such as Mankurom, extensive areas of cocoa farmland have reportedly been lost to galamsey operations, highlighting the growing tension between agricultural sustainability and extractive activities.
To strengthen agricultural productivity and food security, Ghana has implemented several policy initiatives aimed at supporting farmers and modernising the sector. A flagship intervention was the launch of the Planting for Food and Jobs (PFJ) programme in 2017, which sought to boost agricultural output and rural incomes through the provision of subsidised fertilisers, improved seeds and extension services. By enhancing access to key inputs, the programme has helped address constraints related to low soil fertility, limited productivity and climate vulnerability, particularly among smallholder farmers. Complementing these efforts, the Ghana Feed the Future Agriculture Policy Support Project promotes evidence-based policy reforms and an enabling business environment to attract private-sector investment in agriculture.
In addition, the government has sought to promote sustainable agricultural development through the Ghana Agricultural Investment framework and related policies that support productivity growth, resilience and market access. These efforts are complemented by the Modernising Agriculture in Ghana (MAG) programme, a CAD$135 million initiative aimed at enhancing agricultural productivity through improved extension services, value-chain development and greater market integration. Similarly, initiatives such as BRIDGE-in Agriculture seek to increase youth participation in the sector by providing access to finance, skills development and technical assistance, thereby fostering innovation and sustainable agricultural growth.
Beyond government interventions, development partners and non-governmental organisations also play a significant role in supporting the sector. USAID's Feed the Future initiative, for example, adopts a behaviour-change and market systems approach to help Ghana achieve greater food security and agricultural self-sufficiency. The programme focuses on improving agricultural productivity and profitability, strengthening market systems, expanding access to finance, enhancing resilience to climate shocks, promoting economic inclusion and improving nutrition outcomes. These objectives are pursued through evidence-based interventions, including support for food security programmes in northern Ghana, sustainable fisheries management, the promotion of nutrient-rich crops, improvements in processing and storage infrastructure, and partnerships with private-sector actors to strengthen competitiveness and compliance with national and international standards. Collectively, these efforts are intended to modernise the agricultural sector, raise productivity and improve food security.
In 1990, Ghana's total crop production was at 7.8 million metric tons, compared with total crop demand of 8.3 million metric tons, resulting in a supply deficit of approximately 0.5 million metric tons. Over the period 1990–2025, crop production expanded substantially, reaching an estimated 63.2 million metric tons by 2025. This represents an average annual growth rate of 6.2%, nearly double the 3.3% average recorded for the LMICs in Africa. During the same period, total crop demand increased at an average annual rate of 6%, reaching approximately 63.2 million metric tons by 2025. As a result, Ghana narrowed its crop deficit to the margins, with demand exceeding production by around 20 000 metric tons.
Under the Current Path, Ghana’s total crop production is projected to reach 88.5 million metric tons by 2043, while crop demand is expected to increase to 87.9 million metric tons. As production growth slightly outpaces demand growth, the country is forecast to move into a crop surplus of approximately 0.6 million metric tons, indicating a narrowing gap between domestic supply and consumption requirements.
The Agriculture scenario envisions an agricultural revolution that ensures food security through ambitious yet feasible increases in yields per hectare, thanks to improved management, seed, fertiliser technology and expanded irrigation. Efforts to reduce food loss and waste are emphasised. Additionally, enhanced forest protection signifies a commitment to sustainable land use practices.
Chart 15 presents the import dependence in the Current Path and the Agriculture scenario, from 2020 to 2043.
Visit the theme on Agriculture for our conceptualisation and details on the scenario structure and interventions.
In the Agriculture Scenario, crop yields are projected to increase to 15.9 metric tons per hectare by 2043, representing a 43.7% improvement above the Current Path and nearly three times the projected average yield of 6.3 metric tons per hectare for LMICs in Africa. The substantial gains in agricultural productivity translate into significantly higher output, with total crop production projected to reach 123.7 million metric tons by 2043, approximately 35.2 million metric tons above the level anticipated under the Current Path.
The resulting expansion in domestic crop production would substantially reduce Ghana's dependence on crop imports and strengthen its agricultural trade balance. By 2043, the country is projected to become a net exporter of crops, with net exports equivalent to 51.3% of total crop demand under the Agriculture Scenario. This outcome underscores Ghana's potential to achieve food self-sufficiency while generating sizeable export surpluses, provided sustained investments and transformative reforms are implemented to enhance agricultural productivity and competitiveness.
To unlock the sector's full potential, policy efforts should focus on increasing productivity, improving climate resilience, expanding rural infrastructure, strengthening agricultural finance and promoting value addition. Such measures would enhance food security, create jobs, increase export earnings and support Ghana's broader goals of inclusive and sustainable economic development.
Chart 16 depicts the progress through the educational system in the Current Path, for 2023 and 2043.
Countries with large youth populations must invest heavily in education and skills development to harness the demographic dividend and support sustained economic growth. Broadening access to quality education is essential for poverty reduction, human capital accumulation, and moderating population growth. By equipping all children with the knowledge and skills needed to participate productively in the economy, education serves as a key driver of inclusive development and long-term prosperity.
Like many African countries, Ghana's education system follows a 6–3–3 structure, comprising six years of primary education, three years of junior secondary education, three years of senior secondary education, and then tertiary education. Despite notable progress in expanding access to education, Ghana’s education sector continues to face significant resource and infrastructure constraints. Government expenditure on education, which was about 3% of GDP in 2025, remains below UNESCO’s recommended benchmark of 6% of GDP, limiting the resources available to accommodate growing enrolment and improve the quality of education. These funding pressures have contributed to infrastructure deficits, overcrowded classrooms, and shortages of qualified teachers and essential teaching and learning materials. The challenges are particularly evident at the basic education level, where public schools accommodate a large share of learners and therefore face considerable pressure to provide adequate infrastructure, resources, and quality instruction.
The education system can be conceptualised as a long-term funnel in which learners progress from primary through secondary to tertiary education. Although many students enter the system at the primary level, relatively few complete the full cycle and emerge with tertiary qualifications. In Ghana, substantial leakages along this funnel through dropout, low progression rates, and incomplete transitions between educational levels constrain human capital accumulation and reduce the efficiency of investments in education.
Of Ghana’s estimated population of 35 million in 2025, approximately 9.1 million individuals were enrolled in educational institutions across all levels, representing an increase of 960 590 students compared with 2020. Primary education accounted for the largest share of enrolment, with more than 4.8 million learners, while tertiary enrolment reached 692 283 students. The latter reflects an increase of 145 780 students over the same period, highlighting the growing demand for higher education and continued investment in human capital development.
Ghana has made substantial progress in expanding access to primary education. In 2025, the gross enrolment rate at the primary level was estimated at approximately 97%, broadly in line with the average for Africa LMICs in Africa and an improvement from 61.5% in 1990. However, the corresponding net enrolment rate of 86.7% suggests that important challenges remain. The gap between gross and net enrolment indicates, first, that a proportion of school-age children remain outside the education system and, second, that a significant number of learners are over-aged for their grade level, contributing to overcrowded classrooms, a common feature across many African education systems. Under the Current Path scenario, both indicators are expected to improve further, with the gross enrolment rate approaching universal participation at 100.6% and the net enrolment rate rising to 94.1%, reflecting expected continuous gains in educational access and retention.
The transition rate from primary to lower secondary education in Ghana was estimated at 93.7% in 2025, significantly higher than the average of 80.9% for LMICs in Africa. This strong progression rate reflects relatively low attrition between the two levels of schooling and suggests that most learners who complete primary education continue their studies at the lower secondary level. Under the Current Path scenario, the transition rate is projected to increase further to 96.3% by 2043, indicating expected continuous improvements in educational retention and progression, which are essential for strengthening human capital accumulation and supporting long-term economic development.
Gross enrolment rates at both lower and upper secondary levels in Ghana compare favourably with those of many peer countries in Africa. In 2025, gross enrolment in lower secondary education was estimated at 83.0%, significantly higher than the average of 68.3% for LMICs in Africa. Similarly, gross enrolment in upper secondary education reached 74.7%, well above the Africa LMIC average of 47.1%.
The transition rate from lower to upper secondary education was estimated at 99% in 2025, indicating that almost all students who completed lower secondary schooling progressed to the upper secondary level. This exceptionally high transition rate reflects strong retention within the education system and suggests that barriers to progression between the two levels are minimal.
According to the 2025 Human Development Index (HDI) Report, based on 2023 data, Ghana remained classified as a medium human development country, with an HDI score of 0.628 and a global ranking of 143rd out of 191 countries, placing it above many low- and middle-income countries (LMICs) in Africa. However, this represents a slight deterioration in human development outcomes compared to 2021, when Ghana recorded an HDI score of 0.632 and ranked 133rd globally. The decline in both score and ranking suggests that progress in key dimensions of human development (education, health and income) has not kept pace with improvements achieved by other countries globally.
Ghana has introduced several policy reforms to strengthen its education system and expand access, most notably through the Education Strategic Plan (ESP) 2018–2030. Key interventions include the Free Senior High School (SHS) policy, launched in 2017, which removed tuition fees to improve affordability and broaden participation. The government has also expanded school infrastructure to accommodate rising enrolment, improved learning quality through the provision of core textbooks and supplementary readers, and rationalised teacher deployment to enhance efficiency. To promote equity, a 30% quota has been introduced in elite senior high schools for students from public junior high schools.
Under the Current Path scenario, lower and upper secondary educational participation is expected to improve further. Gross enrolment in lower secondary education is projected to increase to 93.6% by 2043, while upper secondary enrolment is forecast to rise to 85.2%. These gains would enhance educational attainment, expand the skilled labour force, and support the country's long-term economic growth and structural transformation objectives. With upper secondary enrolment reaching 85% by 2043, demand for tertiary education in Ghana is likely to increase significantly in years after 2043. A comparison with countries (such as Bolivia and Vietnam) that had upper secondary enrolment rate in the mid- to high 80% range in 2022 suggests that higher tertiary participation often follows.
At the tertiary level, educational participation remains relatively limited despite progress in expanding access. In 2025, the gross enrolment rate in tertiary education was estimated at 20.7%, indicating that only about one in five individuals of tertiary-school age were enrolled in higher education. While this figure was slightly above the average of approximately 19.1% for LMICs in Africa, it underscores the continued challenges in expanding advanced skills development and human capital formation. Moreover, the tertiary graduation rate was estimated at just 13.8% in 2025, suggesting that a significant proportion of those entering higher education do not successfully complete their studies.
Under the Current Path scenario, tertiary enrolment is projected to increase modestly to 28.5% by 2043, remaining only marginally higher than the forecast average of 24.8% for Africa LMICs. The tertiary graduation rate is also expected to improve, rising to 18.7% by 2043. While these projection trends point to gradual gains in both access and completion, the projected pace of improvement remains modest. Further investments in tertiary education will therefore be critical to accelerating human capital accumulation required for sustained economic growth and structural transformation.
Chart 17 presents the mean years of education in the Current Path and in the Education scenario, from 2020 to 2043, for the 15 to 24 age group.
The Education scenario represents reasonable but ambitious improvements in intake, transition, and graduation rates from primary to tertiary levels and better quality of education at primary and secondary levels. It also models substantive progress towards gender parity at all levels, additional vocational training at the secondary school level, and increases in the share of science and engineering graduates.
Visit the theme on Education for our conceptualisation and details on the scenario structure and interventions.
The average years of education among the population aged 15–24 years is an important indicator of the evolving stock of human capital in an economy. It provides insight into the extent to which younger generations are acquiring knowledge and skills, and serves as a useful measure of progress in educational attainment.
In 2025, Ghana ranked eighth in Africa, with an average educational attainment of 10.6 years of schooling (10 years for males and 11.3 years for females). Under the Current Path scenario, average years of schooling are projected to increase to 11.7 years by 2043. Under the Education Scenario, educational attainment is expected to rise further to 12.2 years by 2043 (11.6 years for males and 12.7 years for females), representing an additional gain of 0.5 years relative to the Current Path.
Under the Education Scenario, learning outcomes improve substantially relative to the Current Path. By 2043, average primary school test scores are projected to reach 44.8, representing a 19.4% increase over the Current Path outcome in the same year. Similarly, average secondary school test scores are expected to rise to 42.9, which is 13.9% higher than the Current Path projection. These gains in educational quality are accompanied by improvements in educational access and attainment, with the literacy rate increasing to 90.9% by 2043, a 0.3 percentage points above the Current Path and a marked improvement from the estimated 80.2% recorded in 2025. The share of science, technology, engineering and mathematics (STEM) graduates among tertiary graduates is projected to increase to 18.7% by 2043, five percentage points higher than the Current Path in the same year and a substantial rise from 5.2% in 2025.
Chart 18 presents the value-add by sector as share of GDP in the Current Path, for 2023 and 2043.
The manufacturing sector remains a key pillar of economic transformation, serving as an important source of productivity growth, employment generation and structural diversification. In Ghana, the sector employs more than 250 000 people and encompasses a broad range of activities, including mining-related manufacturing, light industry, aluminium smelting, food processing, cement production and shipbuilding. Major manufactured products include processed cocoa, beverages, palm oil, textiles, chemicals, pharmaceuticals, electric vehicles, aluminium and cement, reflecting the sector’s growing role in domestic value addition and industrial development.
Recognising the strategic importance of manufacturing, Ghana has implemented a range of policies and incentives to stimulate investment, enhance competitiveness and deepen industrialisation. These include exemptions from minimum foreign capital requirements for manufacturing investors, incentives for manufacturing and export-oriented firms through the Free Zones Scheme, and targeted support for micro, small and medium-sized enterprises (MSMEs) under the MSME and Entrepreneurship Policy. Such measures are intended to attract FDI, expand domestic production capacity and accelerate economic growth.
Complementing these efforts, the Industrial Transformation Agenda, launched in 2017, outlines a ten-point strategy to strengthen local production and reduce import dependence, particularly in sectors such as automotive manufacturing and pharmaceuticals. The One District, One Factory (1D1F) initiative further seeks to promote geographically inclusive industrial development by establishing at least one factory in every district, thereby strengthening local value chains, creating employment opportunities and fostering regional economic development. In addition, Ghana is well positioned to leverage the African Continental Free Trade Area (AfCFTA), headquartered in Accra, to access larger regional markets, expand manufacturing output and enhance export competitiveness.
Despite these policy interventions, the sector continues to face significant structural constraints that limit its contribution to economic growth and industrial upgrading. High electricity tariffs and unreliable power supply raise production costs and reduce profitability, particularly for energy-intensive industries. The burden of import duties, indirect taxes and levies further undermines competitiveness, offsetting some of the benefits provided through investment incentives. Access to finance remains another major challenge, especially for small and medium-sized enterprises, as financial institutions often perceive manufacturing activities as high-risk and impose restrictive lending conditions. This constrains firms’ ability to invest in new technologies, innovation and capacity expansion. Furthermore, weaknesses in logistics and supply chain management, compounded by limited access to formal training, contribute to inefficiencies and elevated operating costs.
Persistent infrastructure deficits, including inadequate transport networks, poor road and rail connectivity, and unpredictable lead times, continue to hamper the sector’s productivity and integration into regional and global value chains. As a result, addressing these bottlenecks will be critical for enhancing the competitiveness of Ghana’s manufacturing sector and unlocking its potential as an engine of sustained economic growth and employment creation.
Ghana’s economic structure is dominated by the services, agriculture and manufacturing sectors, which together account for the majority of national output. In 2025, the services sector was the largest contributor to GDP, accounting for an estimated 50.1%, underscoring its central role in driving economic activity. The agriculture sector followed, contributing approximately 19.3% of GDP and continuing to serve as a critical source of livelihoods and food security. Manufacturing contributed an estimated 13.5% of GDP, reflecting its importance in value addition, industrialisation and structural transformation.
Other key sectors included information and communications technology (ICT), which accounted for nearly 6% of GDP, highlighting the growing role of the digital economy, while the energy and materials sectors contributed 5.6% and 5.4% of GDP, respectively. Together, these sectoral contributions illustrate the diverse composition of Ghana’s economy.
On the Current Path, the services sector is projected to further consolidate its position as the dominant driver of Ghana’s economy, with its share of GDP increasing to 56.9% by 2043. Over the same period, manufacturing is expected to emerge as the second-largest contributor to GDP, with its share rising to 19.2%, surpassing agriculture as industrialisation and domestic value addition gain momentum. In contrast, the agriculture sector’s contribution is projected to decline to 7.9% of GDP by 2043, consistent with the structural transformation process in which labour and resources gradually shift from lower-productivity agricultural activities to higher-productivity industrial and service sectors.
The information and communications technology (ICT) sector is also expected to expand its economic footprint, contributing 7% of GDP by 2043, reflecting the growing role of digitalisation in economic development. Meanwhile, the materials and energy sectors are projected to account for 6.3% and 2.6% of GDP, respectively. Overall, these trends point to a more diversified and modern economy, characterised by a greater reliance on services, manufacturing and technology-driven activities as key sources of growth.
Chart 19 presents the contribution of the manufacturing sector to GDP in the Current Path and in the Manufacturing scenario, from 2020 to 2043. The data is in US$ and % of GDP.
In the Manufacturing scenario, reasonable but ambitious growth in manufacturing is envisaged through increased investment in the sector, research and development (R&D) and improved government regulation of businesses.
Visit the theme on Manufacturing for our conceptualisation and details on the scenario structure and interventions.
As industrialisation deepens and productivity gains spread across the economy, the expansion of manufacturing typically creates higher-quality employment, raises household incomes and supports more inclusive and sustained economic growth. The larger manufacturing footprint would not only enhance economic diversification but also support export competitiveness and the development of stronger domestic value chains. Over time, these effects can contribute significantly to poverty reduction and a broader distribution of economic opportunities, reinforcing the long-term benefits of structural transformation.
In the Manufacturing Scenario, Ghana is projected to make significant progress in industrialisation and structural transformation. By 2043, the manufacturing sector’s contribution to GDP is expected to increase to 21.8%. This would represent an expansion of approximately 2.6 percentage points relative to the Current Path.
Realising these gains, however, requires a sustained and coordinated industrialisation strategy. Industrial development is a complex and long-term process that depends on effective collaboration between the state and the private sector. The state plays a critical role in addressing market failures and creating the conditions necessary for firms to invest, innovate and expand. This includes articulating a clear economic vision, maintaining macroeconomic stability, providing reliable infrastructure and public services, and ensuring a regulatory environment that supports entrepreneurship and investment.
Equally important is the state's ability to facilitate technological upgrading, enhance firms’ access to finance and skills, and lower barriers to entry into new industries and export markets. By strengthening these enabling conditions, governments can accelerate industrial upgrading, improve competitiveness and support the transition towards a more diversified and resilient economy.
Chart 20 depicts exports and imports as a percentage of GDP, from 2000 to 2043, in the Current Path.
Ghana’s economy is relatively well integrated into global markets compared to many of its African peers. In 2025, it ranked 26th out of 54 African countries in terms of trade openness, with total trade measured as the sum of exports and imports estimated at 66.4% of its GDP. This represents a significant increase from 42.7% of GDP in 1990, reflecting the country’s growing integration into the global economy. Despite this relatively high degree of openness, Ghana’s export basket remains concentrated in a narrow range of primary commodities. Gold, cocoa and crude oil account for the majority of export earnings and foreign exchange receipts, leaving the economy exposed to fluctuations in global commodity prices and external demand conditions.
Ghana is among the world’s leading producers of both gold and cocoa, underscoring the continued importance of the extractive and agricultural sectors to the country’s external trade performance. However, this dependence also highlights the need for greater export diversification and value addition to enhance economic resilience and support long-term structural transformation.
The country’s trade policy is centred towards promoting economic growth, strengthening export competitiveness and deepening the country’s integration into regional and global markets. To support these objectives, Ghana has entered into a range of multilateral, regional and bilateral trade agreements that expand market access and facilitate cross-border trade. As a longstanding member of the World Trade Organization (WTO), Ghana is a signatory to the WTO Trade Facilitation Agreement, which aims to reduce trade costs and improve the efficiency of international commerce.
At the regional level, Ghana is a member of the Economic Community of West African States (ECOWAS), which seeks to promote economic integration and facilitate the free movement of goods, services and factors of production across West Africa. Ghana has also ratified the African Continental Free Trade Area (AfCFTA) Agreement, whose Secretariat is headquartered in Accra. The AfCFTA provides a strategic opportunity to expand intra-African trade, strengthen regional value chains and support industrial development through access to a larger continental market.
Beyond Africa, Ghana has secured preferential access to key international markets through several bilateral agreements. These include the Economic Partnership Agreement (EPA) with the European Union and a similar interim agreement with the United Kingdom, both of which provide reduced tariffs on a substantial share of traded goods. Ghana also participates in the Trade and Investment Framework Agreement with the United States, enabling many of its exports to benefit from duty-free access under the African Growth and Opportunity Act (AGOA) and the Generalized System of Preferences (GSP). Collectively, these agreements enhance Ghana’s trade competitiveness, attract investment and create opportunities for export-led growth and economic diversification.
To further promote trade and investment, Ghana has pursued a range of policies aimed at trade liberalisation, tariff rationalisation and investment promotion. A key component of this strategy is the government’s ambition to position the country as a regional automotive manufacturing hub in sub-Saharan Africa. To support this objective, Ghana offers tax incentives and other investment facilitation measures to attract Original Equipment Manufacturers (OEMs) to establish local assembly operations. As a result, several global automotive companies, including Toyota, Volkswagen, Nissan, Suzuki, Kia and Mahindra, have established vehicle assembly plants in the country. More recently, fiscal reforms include adjustments to excise duties and the introduction of the Growth and Sustainability Levy, have been implemented to strengthen public finances and enhance fiscal sustainability. While these measures are important for macroeconomic stability, they may also affect firms’ production costs, profitability and overall competitiveness.
Despite these efforts, several structural constraints continue to limit Ghana’s trade and investment potential. Access to affordable finance remains a major challenge for domestic firms, with commercial lending rates averaging around 32%, significantly increasing the cost of capital and constraining business expansion and export capacity. Ghana’s elevated public debt burden and persistent challenges in domestic revenue mobilisation further reduce fiscal space and weigh on private sector activity.
In addition, businesses face a range of operational bottlenecks, including limited access to financial services, governance and transparency concerns, corruption, inadequate infrastructure, a complex land and property market, and unreliable electricity and water supply. High logistics and cross-border trade costs, cumbersome administrative procedures and skills shortages also undermine productivity and competitiveness. Addressing these structural impediments will be essential for improving Ghana’s business environment, strengthening export performance and fully realising the country’s potential as a regional trade and manufacturing hub.
On the Current Path, Ghana’s trade openness is projected to increase further, with total trade rising to 81.2% of GDP by 2043. This would place the country well above the projected averages for both Africa’s LMICs (63.6% of GDP) and the continent as a whole (65.3% of GDP) in the same year.
In 2025, Ghana's exports accounted for 31.4% of its GDP, an increase of 14.5 percentage points when compared to 1990, underscoring its firm reliance on external trade. The country’s export composition is highly concentrated in homogeneous goods (gold, crude petroleum, cocoa and other primary products), which account for the majority of the country’s export earnings. Under the Current Path, Ghana’s export performance is projected to strengthen further, with exports increasing to 41.0% of GDP by 2043.
The concentration of Ghana’s export basket can be assessed by examining the share of total export earnings accounted for by its five largest export products. A higher share indicates greater dependence on a narrow range of products, while a lower share reflects a more diversified and potentially resilient export structure. In 2024, Ghana’s top five exports accounted for approximately 77% of total export earnings, highlighting a relatively high degree of export concentration. Gold was the largest export, contributing 36.9% of total export revenues, followed by crude petroleum (23.1%), cocoa beans (9.1%), cocoa paste (4.4%) and manganese ore (3.5%). This composition underscores the continued dominance of primary commodities in Ghana’s export sector and its exposure to fluctuations in global commodity markets. The country’s principal export destinations were Switzerland, China, India, the United States and the Netherlands.
Ghana’s import basket is relatively diversified and dominated by manufactured goods, with the top five import categories accounting for only 15.6% of total imports in 2024. Refined petroleum products constituted the largest share (7.5%), followed by heavy construction vehicles (3.0%), poultry meat (1.8%), passenger cars (1.7%), and telecommunication devices, including mobile phones (1.7%). These imports were sourced primarily from China, India, the Netherlands, the United States, and Belgium.
Chart 21 presents the trade balance in the Current Path and in the AfCFTA scenario, from 2020 to 2043 as a percentage of GDP.
Deeper regional economic integration, supported by more efficient cross-border movement of goods and services, could accelerate economic development across Africa by reducing trade costs, improving market access, and strengthening regional value chains. As incomes and living standards rise across the continent, expanding consumer demand would increase the size and purchasing power of the regional market. For Ghana, this would create greater opportunities for domestic firms to expand exports, achieve economies of scale, diversify production, and integrate more deeply into regional value chains. Ghana’s access to a larger and more prosperous African market could therefore become an important source of trade-led growth and structural transformation.
The AfCFTA scenario represents the impact of fully implementing the African Continental Free Trade Agreement by 2034. The scenario increases exports in manufacturing, agriculture, services, ICT, materials and energy exports. It also includes improved multifactor productivity growth from trade and reduced tariffs for all sectors.
Visit the theme on AfCFTA for our conceptualisation and details on the scenario structure and interventions.
Historically, Ghana has recorded persistent trade deficits, reflecting a structural imbalance between its import and export earnings. In 2025, the trade deficit was estimated at approximately 3.6% of GDP, driven largely by deficits in the services and agricultural trade. Under the Current Path scenario, Ghana’s external trade position is projected to improve steadily, resulting in a trade surplus equivalent to about 0.8% of GDP (approximately US$2.4 billion) by 2043.
In contrast, under the AfCFTA scenario, Ghana is projected to record a trade deficit of nearly 0.4% of GDP (equivalent to around 1.2 billion) in 2043. This suggests that while the AfCFTA may stimulate greater trade integration and economic activity, it is also expected to increase import demand more rapidly than export growth, effectively reversing the trade surplus projected under the Current Path and resulting in a modest trade deficit.
Chart 22 presents the Current Path of access to electricity for urban, rural and the total population from 2000 to 2043.
The Large Infrastructure and Leapfrogging scenario involves ambitious investments in road and renewable energy infrastructure, improved electricity access and accelerated broadband connectivity. It emphasises adopting modern technologies to enhance government efficiency and incorporates significant investments in major infrastructure projects like rail, ports and airports (other infra) while highlighting the positive impacts of renewables and ICT.
Visit the themes on Large Infrastructure and Leapfrogging for our conceptualisation and details on the scenario structure and interventions.
Modern infrastructure plays a pivotal role in economic development by enhancing productivity, improving health outcomes, strengthening educational attainment, and increasing the efficiency of public service delivery. This study considers both physical and digital infrastructure, encompassing transport networks, electricity access, and information and communication technologies (ICT).
Physical infrastructure such as roads and railways are fundamental drivers of economic growth, reducing transaction costs, facilitating the movement of people, goods, and services, and deepening domestic market integration. It also serves as a critical enabler of social development by improving access to essential services such as education and healthcare.
Digital infrastructure serves as the backbone of innovation, productivity growth, and economic transformation. Reliable internet connectivity, mobile networks, and digital platforms facilitate the flow of information, expand access to financial and government services, support business competitiveness, and enable participation in the digital economy. By improving communication, reducing information asymmetries, and fostering technological adoption, digital infrastructure enhances economic efficiency and strengthens a country's capacity to integrate into regional and global value chains. Together, physical and digital infrastructure create the enabling environment necessary for sustained economic growth and inclusive development.
Ghana’s relatively high level of urbanisation facilitates the provision of infrastructure and public services, as delivering infrastructure in densely populated urban areas is generally more cost-effective than in dispersed rural communities. Reflecting this advantage, Ghana ranked 12th out of 54 African countries on the African Infrastructure Development Index (AIDI) in 2025, with a score of 84.5 out of 100. The AIDI assesses infrastructure performance across four key dimensions: transport, electricity, information and communication technology (ICT), and water supply and sanitation. Despite notable progress in expanding access to and improving the quality of infrastructure over recent decades, Ghana continues to face significant infrastructure challenges. Much of the country's infrastructure stock remains inadequate to meet growing demand, while ageing assets and maintenance deficits constrain service quality and economic productivity.
Recognising the role of transport infrastructure as a catalyst for economic growth and structural transformation, the government has prioritised investments aimed at modernising the country's transport network. Consequently, several major road projects have been implemented in Accra and other key urban centres, including Kumasi and Cape Coast. In August 2024, the government further launched the District Road Improvement Programme (DRIP), which seeks to strengthen the capacity of Metropolitan, Municipal and District Assemblies (MMDAs) by providing equipment and resources for local road construction and maintenance. Despite these efforts, Ghana's road infrastructure remains comparatively underdeveloped relative to many of its regional peers, highlighting the need for continued investment to address infrastructure gaps and support long-term economic development.
By 2025, Ghana’s road network had expanded substantially, growing from an estimated 38 145 km in 1990 to 70 086 km. Despite this progress, only about 25.3% of the network was paved, compared with an estimated African average of 32%, highlighting a persistent infrastructure quality gap. Under the Current Path scenario, Ghana’s total road network is projected to increase further to approximately 103 637 km by 2043. Over the same period, significant investment in road infrastructure is expected to accelerate the upgrading of the network, with paved roads increasing to account for 62.1% of total road length.
Regarding access to electricity, the country has made significant investments in electricity generation capacity over the years. Ghana’s power supply sources include hydroelectricity and thermal plants. It consists of 1.584MW of installed hydro, 3.758MW of thermal power plants (mostly fuelled by natural gas from Nigeria and sometimes light crude oil), and 112MW of solar generation. The major source of hydro production in Ghana is the Akosombo dam which was constructed in 1965 generate 1 020MW. Other hydro sources of power include the Kpong Hydro Plant established in 1982 which generates 160MW. The Bui Dam which was also constructed from 2007 and completed in 2013 also generates 400MW of hydro power for the country. Major thermal sources include the Karadeniz Powership Osman Khan (470MW), Aksa Enerji Oil Fired Power Plant (370MW) and Sunon Asogli Power Plant Phase II (360 MW), mostly owned and operated by independent power producers. Aside these, the Volta River Athority also operate the TAPCO (T1), TICO(2), Tema Thermal Plant 1&2, among others. The VRA also operate various solar plants such as Navrongo, Lawra and Kaleo solar plants.
As a result of sustained investments in electricity generation and distribution, Ghana has made remarkable progress in expanding access to electricity, with the electrification rate increasing from 30.6% in 1993 to an estimated 87.1% of the population in 2025. This places Ghana well above the estimated averages of 72% for LMICs in Africa and 61% for the continent as a whole. The country's relatively strong electricity sector has also enabled it to export electricity to neighbouring countries, including Togo, Burkina Faso, and Benin.
However, significant spatial disparities in access persist. In 2025, an estimated 95.7% of urban residents had access to electricity, compared to 74.2% of the rural population, reflecting the higher costs and logistical challenges associated with extending grid infrastructure to sparsely populated areas. Nevertheless, Ghana remains one of the leading performers in electricity access in Africa, owing largely to successive government investments in rural electrification programmes that have significantly expanded access beyond major urban centres.
Despite Ghana’s relatively high electricity access rate, the reliability and stability of power supply remain significant challenges. The country has experienced recurrent periods of load shedding, commonly known as Dumsor, with the most severe episode occurring between 2014 and 2016. The prolonged power crisis imposed substantial economic costs by disrupting industrial production, reducing business productivity, and constraining economic growth.
Addressing the crisis required costly emergency interventions. To alleviate power shortages, the government entered into agreements with Independent Power Producers (IPPs) and procured emergency power plants, leading to the accumulation of substantial financial obligations through capacity charge arrangements. These agreements guaranteed payments to IPPs for maintaining generation capacity, regardless of actual electricity consumption. As a result, Ghana paid an estimated US$937.5 million in capacity charges between 2017 and 2020.
The financial sustainability of the power sector remains under pressure, with mounting debt owed to IPPs raising concerns about the sector’s viability. For example, Sunon Asogli power temporarily shut down its 560 MW plant due to outstanding arrears reportedly amounting to US$259 million owed by the Electricity Company of Ghana (ECG), while several other IPPs have issued similar warnings over unpaid debts. The situation is further exacerbated by operational inefficiencies and persistent financial losses at ECG, the country's main power distribution utility. In 2022 alone, ECG recorded losses estimated at GHC10.2 billion, reflecting challenges related to revenue collection, technical losses, and inefficiencies in electricity distribution.
Unless the structural drivers of the sector's debt burden are effectively addressed including financial losses, cost-recovery challenges, and governance inefficiencies, the long-term sustainability of Ghana’s power sector will remain at risk, with potentially adverse implications for economic growth, investment, and energy security.
Under the Current Path scenario, electricity access in Ghana is projected to expand further, reaching 96.8% of the population by 2043. While urban residents are expected to continue enjoying higher levels of access, the urban-rural gap is projected to narrow considerably over time. By 2043, electricity access among urban residents is forecast to reach 99.6%, while rural electrification is expected to increase to 90.9%.
Chart 23 presents the number of people using cookstoves in the Current Path and in the Large Infrastructure and Leapfrogging scenario, from 2020 to 2043.
Cooking with biomass stoves poses serious health risks, especially for women and children, due to prolonged exposure to indoor air pollution, which can lead to respiratory illnesses. At the same time, reliance on biomass fuels contributes to deforestation, forest degradation and significant carbon emissions, further intensifying climate change.
In 2025, an estimated 74.9% of households in Ghana relied on traditional cooking fuels, while 23.5% used modern cooking fuels. Only 1.5% of households were estimated to use improved cookstoves. This relatively low adoption of modern cooking technologies is notable given the country's high electricity access rate. It suggests that factors such as unreliable electricity supply, affordability constraints, and limited access to alternative clean cooking fuels may be hindering the transition away from traditional cooking methods.
A similar pattern is observed across LMICs in Africa, where an estimated 51.2% of the population still relies on traditional cookstoves, while 44.9% use modern cooking fuels. Continued dependence on traditional cooking fuels contributes to indoor and outdoor air pollution, increases greenhouse gas emissions. Under the Current Path scenario, the share of Ghanaians relying on traditional cookstoves is projected to decline significantly, from 74.9% in 2025 to 28.2% by 2043. Over the same period, the proportion of households using modern cooking fuels is expected to increase to 71.3%.
Under the Large Infrastructure and Leapfrogging scenario, the transition to cleaner cooking technologies is expected to occur more rapidly. The share of households using traditional cookstoves could fall to 23.4% by 2043, which will be 4.8 percentage points lower than the Current Path projection for the same year. Correspondingly, the adoption of modern cooking fuels is projected to rise from 23.5% in 2025 to 76.1% by 2043, exceeding the Current Path forecast of 71.3%.
Chart 24 presents the percentage of the population and number of people with access to mobile and fixed broadband in the Current Path and in the Large Infrastructure and Leapfrogging scenario, from 2020 to 2043. The user can toggle between mobile and fixed broadband.
The Large Infrastructure and Leapfrogging scenario is projected to accelerate the expansion of fixed broadband connectivity in Ghana. By 2043, fixed broadband subscriptions are expected to reach 22.6 subscriptions per 100 people, compared with 17.1 subscriptions per 100 people under the Current Path. In contrast, the scenario has only a marginal effect on mobile broadband penetration, reflecting the country's already strong performance in this area. Under the Current Path, mobile broadband subscriptions are projected to reach 154.4 subscriptions per 100 people by 2043, unchanged under the Large Infrastructure and Leapfrogging scenario. This suggests that the greatest gains from additional infrastructure investments are likely to come from expanding fixed broadband access, where significant scope for improvement remains.
Chart 25 presents the trends in FDI, aid and remittances in the Current Path and in the Financial Flows scenario as a percentage of GDP, from 1990 to 2043.
The Financial Flows scenario represents a reasonable but ambitious increase in inward flows of worker remittances, aid to poor countries and an increase in the stock of foreign direct investment (FDI) and additional portfolio investment inflows. We reduce outward financial flows to emulate a reduction in illicit financial outflows.
Visit the theme on Financial Flows for our conceptualisation and details on the scenario structure and interventions.
Like many African economies, Ghana has historically attracted relatively low levels of FDI. In 1990, FDI inflows amounted to just 0.3% of GDP, below the average of 0.7% of GDP recorded by LMICs in Africa. Since then, however, Ghana has emerged as one of the continent’s more attractive investment destinations. By 2025, FDI inflows had increased substantially to an estimated 5.7% of GDP, more than double the LMIC average of 2.8% of GDP.
Ghana's FDI flows are predominantly directed into several major industries, including manufacturing, building and construction, tourism, services, general trading and export trading, and agriculture, which are critical for job creation and economic growth. However, the promising sectors are the downstream oil, gas and minerals processing; construction and real estate; mining-related services subsectors; agribusiness and food processing; ICT and business-related services; textiles and apparel. These sectors offer significant opportunities for industrialisation, export diversification, and structural transformation.
The country has implemented a range of policy measures to attract and retain FDI. The Ghana Investment Promotion Centre (GIPC) Act of 2013 provides a comprehensive regulatory framework for foreign investment, promoting transparency, legal certainty, and investor protection across key sectors, including mining, oil and gas, agriculture, and manufacturing. To enhance its attractiveness as an investment destination, the government offers various incentives, such as tax holidays, preferential corporate tax rates, and exemptions from import duties and value-added tax (VAT) on selected inputs and capital goods.
In addition, substantial investments in transport, energy, and telecommunications infrastructure have sought to improve the overall business environment and reduce the cost of doing business. The Ghana Free Zones Authority (GFZA) further supports investment promotion by overseeing free zones that provide a range of fiscal and regulatory incentives aimed at attracting export-oriented industries and foreign investors. Together with Ghana’s political stability, abundant natural resource endowment, and strategic location within West Africa, these policies have contributed to creating a relatively favourable investment climate and strengthening the country's appeal as a destination for international capital.
However, there are still challenges in attracting FDI. Economic uncertainties, such as exchange rate volatility and high inflation, deter potential investors. Poor infrastructure, particularly in transportation and utilities, hampers investment opportunities and increases operational costs. Furthermore, high minimum capital requirements and bureaucratic hurdles complicate the investment process, making Ghana less attractive to foreign investors. Weak governance and corruption further undermine investor confidence, as investors prefer stable legal environments for their investments.
Under the Current Path scenario, FDI inflows are projected to increase steadily, reaching 6.6% of GDP by 2043, well above the average of 3.3% projected for African LMICs. Under the Financial Flows scenario, FDI inflows are expected to rise further to 8.6% of GDP by 2043, representing an increase of 2.1 percentage points relative to the Current Path forecast.
Typical of many developing economies, Ghana's dependence on foreign aid has declined markedly over time. In 1990, official development assistance amounted to 9.7% of GDP, exceeding the average of 7.4% recorded by LMICs in Africa. Aid inflows peaked in the early 2000s, largely due to Ghana's participation in the Heavily Indebted Poor Countries (HIPC) Initiative, which provided substantial debt relief and concessional financing. Between 2000 and 2005, aid inflows averaged approximately 13% of GDP, reflecting the significant role of external assistance in supporting public finances and development programmes.
Since then, however, the importance of aid as a source of financing has diminished considerably. By 2025, aid inflows had fallen to just 1.66% of GDP, only marginally above the estimated LMIC average of 1.58% for Africa. This decline reflects not only a reduction in external assistance but also Ghana's economic expansion, which has reduced the relative contribution of aid to national income. As the economy has grown and diversified, domestic revenue mobilisation, private investment, and other external financial flows have become increasingly important sources of development finance.
Most aid to the country goes into the health, education and agriculture sectors, with an emphasis on the poorest and most vulnerable populations. Aid and donor support are also used to strengthen institutions, implement anti-corruption campaigns, enhance tax policies, and boost social services.
As part of the effort to reduce the reliance on aid, the President in 2018 announced the Ghana Beyond Aid vision. In his speech on Ghana’s 61st Independence Day celebration, the President stated “It is time to pursue a path to prosperity and self-respect for our nation. A Ghana Beyond Aid is a prosperous and self-confident Ghana that is in charge of her economic destiny; a transformed Ghana that is prosperous enough to be beyond needing aid, and that engages competitively with the rest of the world through trade and investment.” However, this vision has yet to materialise, especially after the 2022 economic crisis where Ghana had to seek debt relief from multilateral and bilateral creditors. For instance, in June 2024, the country received US$2.8 billion in debt relief from bilateral creditors as part of the IMF programme and effort to achieve fiscal consolidation. On the Current Path, foreign aid will decline further to a negligible level by 2043.
Remittances are increasingly becoming an important source of financial flows globally, especially to African countries. Just like many African countries, many Ghanaians have migrated abroad mainly for education and in search of greener pastures. The remittances from these immigrants have become a vital source of inflow to their families. At the macro level, remittances often provide a buffer against economic shocks and contribute to national financial stability.
The cost of sending remittances through formal channels has generally declined over time, supported by the expansion of digital financial services, increased competition among money-transfer operators, and technological improvements in cross-border payment systems. These developments have lowered transaction costs and improved the accessibility and efficiency of remittance transfers. However, the decline has been less pronounced in sub-Saharan Africa (SSA), where remittance costs remain relatively high compared with other developing regions. Limited competition, inadequate financial infrastructure, regulatory barriers, and the high cost of cross-border transactions continue to constrain further reductions in transfer costs. Lowering these costs would increase the share of remittance income received by households and could strengthen the contribution of remittances to consumption, savings, investment, and broader economic development.
In 1990, remittance inflows to Ghana were relatively small, accounting for only 0.1% of GDP, well below the 3.5% average for LMICs in Africa. Since then, remittances have increased substantially, reaching an estimated 2.2% of GDP in 2025. However, this remains below the average of 3.5% for Africa LMICs.
Remittances are mainly sent by Ghanaian migrants to support families and relatives at home, with major source countries including the United States, the United Kingdom, Nigeria, and Côte d'Ivoire. These transfers play an important role in household welfare by helping finance essential expenses such as education, healthcare, housing costs, and general consumption. However, as in many African countries, the high cost of sending money to Ghana can discourage migrants from using formal remittance channels and limit the full developmental impact of these flows.
Under the Current Path scenario, remittances are projected to decrease as a proportion of GDP, falling to 1.4% by 2043. The implementation of the Financial Flows scenario yields only a modest improvement, raising remittance inflows to 1.6% of GDP by 2043, equivalent to an increase of 0.1 percentage points relative to the Current Path forecast.
Chart 26 presents government revenue in the Current Path and in the Financial Flows scenario, from 2020 to 2043. The data is in US$ 2017 and % of GDP.
Wagner's law, or the law of increasing state activity, states that public expenditure increases as national income rises. In the Financial Flows scenario, it is reasonable to expect that government revenues will increase as a percentage of GDP compared to the Current Path.
Higher external financial inflows in the form of FDI, official ODA, and remittances can strengthen government revenue by stimulating economic activity and expanding the tax base. Increased FDI contributes to higher economic growth, job creation, and business expansion, which generate additional government revenue through corporate income taxes, personal income taxes, royalties, and indirect taxes such as value-added tax (VAT). Similarly, aid and remittance inflows can support consumption, investment, and productivity, further enhancing domestic revenue mobilisation and fiscal capacity.
In 2025, Ghana's total government revenue amounted to 11% of GDP, while domestic revenue excluding aid stood at 9.3% of GDP. The relatively small gap between total revenue and revenue excluding aid indicates a limited dependence on external assistance.
Under the Current Path scenario, total government revenue is projected to increase to 17.9% of GDP by 2043. Revenue excluding aid is also forecast to remain at 17.9% of GDP, suggesting that future revenue growth will be driven primarily by enhanced domestic resource mobilisation rather than external assistance. Under the Financial Flows scenario, government revenue is expected to rise slightly further, reaching 18.2% of GDP by 2043.
Chart 27 presents the Current Path of government effectiveness comparing the country to the average for the African income group, from 2002 to 2043.
The World Bank’s index on government effectiveness captures perceptions of the quality of public services, the quality of the civil service and the degree of its independence from political pressures, the quality of policy formulation and implementation and the credibility of the government's commitment to such policies.
Good governance is key to economic progress. Greater security and stability at the national level create an enabling environment for domestic and foreign investment. It creates conditions for governments to pursue effective, sustainable development strategies. Good governance and security cut across all sectors; they create incentives and confidence for investment and innovation. Good governance is crucial for the efficient use of public funds for development and improving the well-being of the population.
Ghana is widely regarded as one of the most stable democracies in West Africa and has long been considered an oasis of peace in a region often affected by political instability and violent conflict. Unlike many of its neighbours, Ghana has not experienced civil war, major political crises or direct terrorist attacks. Since the establishment of the Fourth Republic in 1993, Ghana has successfully conducted nine successive presidential and parliamentary elections, several of which have resulted in peaceful alternations of power between the National Democratic Congress (NDC) and the New Patriotic Party (NPP). This record has strengthened Ghana's reputation as one of the most stable democracies in Africa.
Ghana’s governance performance is reflected in several international indices. According to the 2023 Ibrahim Index of African Governance (IIAG), Ghana ranked 7th out of 54 African countries, with an overall score of 62.3 out of 100, well above both the continental average of 49.3 and the West African average of 51.3. Similarly, the Economist Intelligence Unit's 2023 Democracy index classified Ghana as a flawed democracy, ranking it 6th in Sub-Saharan Africa and 65th globally, while the 2024 Varieties of Democracy (V-Diem) Liberal Democracy Index ranked the country 5th in Africa and 55th worldwide.
The World Bank's Government Effectiveness Index, which measures perceptions of public service quality, civil service professionalism, policy implementation and government credibility, further highlights Ghana’s relative institutional strength. Measured on a scale from 0 to 5, Ghana scored approximately 2.4 in 2025, ranking 9th among 55 African countries and substantially above the continental average of 1.7. Under the Current Path scenario, the score is projected to increase to 2.9 by 2043, compared with a projected African average of 2.2.
Despite these achievements, several governance challenges persist. The IIAG reports a notable deterioration in security and the rule of law, with Ghana’s score in this category declining from 69 in 2017 to 60 in 2023. Security concerns have become increasingly prominent, particularly in the northern regions bordering Burkina Faso. The porous nature of this border facilitates the movement of illicit arms and contraband, creating vulnerabilities to the spillover effects of insecurity from the Sahel region. With extremist groups controlling significant portions of Burkina Faso, concerns have grown about the potential spread of violent extremism into northern Ghana.
Domestic factors further compound these risks. Long-standing tensions between ethnic groups such as the Mamprusi and Kusasi in Bawku have periodically resulted in armed conflict. Combined with limited economic opportunities, poverty and unemployment in northern communities, these local grievances create conditions that extremist groups could exploit for recruitment. The worsening security environment across the Sahel region following the withdrawal of French military forces has further heightened concerns about regional instability spilling over into Ghana.
In response, the government has implemented several preventive measures. These include the "See Something, Say Something" campaign, designed to encourage public reporting of suspicious activities, as well as the deployment of additional military brigades and battalions to strengthen security along the northern frontier. While these initiatives have enhanced border security, analysts caution that a narrow focus on external threats may overlook the internal governance and development challenges that contribute to community vulnerability.
Corruption remains another significant governance challenge. According to the 2025 global Corruption Perceptions Index (CPI) by Transparency International, Ghana scored 42 out of 100 and ranked 80th out of 180 countries surveyed, down from 70th and a score of 43 in 2023. Lower scores indicate higher perceived corruption, while 100 reflects a very clean public sector.
Estimates from the Ghana Integrity Initiative estimated that corruption costs the country as much as US$3 billion annually. The 2021 Ghana Integrity of Public Services Survey (GIPSS) reported that approximately GHS5 billion was paid in bribes to public officials during that year alone. Public perceptions of corruption have also worsened significantly. According to the 2022 Afrobarometer Survey, the proportion of Ghanaians who believe corruption has increased rose from 33.2% in 2017 to 77% in 2022.
Efforts to strengthen anti-corruption institutions have yielded mixed results. In 2018, the government established the Office of the Special Prosecutor to investigate and prosecute corruption-related offences. However, institutional and political constraints have limited its effectiveness. The first Special Prosecutor resigned, citing political interference, while his successor has repeatedly raised concerns about inadequate funding, logistics and operational support.
Although Ghana has maintained democratic stability, public confidence in democratic governance has weakened in recent years. According to the 2024 Afrobarometer African Insight report, satisfaction with the functioning of democracy declined from 74% in 2012 to 51% in 2024. More concerning is the increase in public support for military intervention, which rose from 14% to 32% over the same period. This trend suggests growing frustration with governance outcomes and indicates that democratic gains have not fully translated into the expected socioeconomic benefits for many citizens.
Gender inclusion and representation also remain areas requiring significant improvement. While Ghana has made notable progress—including appointing a female Speaker of Parliament, three female Chief Justices, two female Electoral Commission Chairpersons and the nomination of a female vice-presidential candidate by one of the major political parties—women remain underrepresented in political decision-making. Since the establishment of the Fourth Republic, women have consistently occupied less than 15% of parliamentary seats, well below the global benchmark of 30%. Similarly, women have accounted for less than 20% of ministerial appointments and District Chief Executive positions.
To address these disparities, Ghana enacted the Affirmative Action (Gender Equity) Act in July 2024. Originating from policy discussions that began in 2011, the legislation seeks to promote gender parity in political representation, public appointments and decision-making institutions. Effective implementation of the Act will be critical to improving women's participation in governance and strengthening inclusive development.
Overall, Ghana continues to outperform many of its regional and income-group peers in governance, democratic stability and institutional effectiveness. However, rising security threats, persistent corruption, declining public confidence in democratic institutions and gender inequalities highlight the need for continued reforms to sustain and deepen the country's governance gains.
Chart 28 presents the security, capacity and inclusion index for the Current Path versus the Governance scenario, for 2023 and 2043.
In our modelling framework, governance is conceptualised across three dimensions - security, capacity, and inclusion - representing the traditional stages of state formation. Each governance dimension is scored on a scale from zero (poor) to one (excellent). The security dimension evaluates the likelihood of internal conflict and overall risk levels. The capacity dimension encompasses factors such as government revenue, corruption, regulatory quality, economic freedom, and government effectiveness. Finally, the inclusion dimension assesses the extent of democracy and gender empowerment.
Visit the theme on Governance for a full conceptualisation and details on the scenario structure and interventions.
Generally, Ghana performs better on governance indices than most African countries. The composite ‘governance triangle’ in our modelling measures a state’s progress using the average of these three indices. To this end, it includes an index (0 to 1) for each dimension, with higher scores indicating improved outcomes. In 2025, Ghana recorded a composite governance index score of 0.58, outperforming the average for African LMICs by 19% and the continental average by 22%. Governance outcomes are expected to strengthen over the forecast period, with the score rising to 0.65 under the Current Path scenario by 2043. Enhanced governance reforms under the Governance scenario would further improve performance, increasing the score to 0.71 by 2043.
A disaggregation of the index into its three core dimensions - security, capacity and inclusion - reveals that Ghana outperforms its income peers across all three components, underscoring its relatively strong governance performance on the continent. In 2025, Ghana scored 0.80 on the security index, 0.32 on capacity and 0.61 on inclusion. Under the Current Path scenario, these scores are projected to improve by 2043, reaching 0.84 for security, 0.44 for capacity and 0.65 for inclusion. The Governance scenario would accelerate progress across all three dimensions, raising the scores further to 0.92 for security, 0.50 for capacity and 0.70 for inclusion by 2043.
Chart 29 presents GDP per capita in purchasing power parity (PPP) in the Current Path and each of the eight sectoral scenarios. The data is from 2020 with a forecast to 2043.
The combined effects of improvements in education, health, infrastructure, technological leapfrogging, demographics, agriculture, manufacturing, trade and financial flows generate additional gains larger than any other individual scenarios impact interventions. This additional benefit, referred to as the synergistic effect, reflects the mutually reinforcing interactions among sectors. As a result, all sectoral scenarios increase Ghana’s GDP per capita (2021 PPP) above the Current Path trajectory. Among the alternative scenarios, the Governance scenario delivers the largest improvement in GDP per capita by 2043, followed by the AfCFTA, Financial Flows, and Infrastructure and Leapfrogging scenarios. In contrast, the Education and Agriculture scenarios have the smallest impacts, generating only modest increases in GDP per capita relative to the Current Path by 2043.
In the Governance scenario, Ghana’s GDP per capita is projected to reach US$12 940 by 2043, approximately 7.1% higher than under the Current Path scenario. This translates into an additional gain of about US$860 per person by 2043. The substantial economic benefits associated with improved governance reflect the critical role of strong institutions in promoting sustainable growth. Enhancements in the rule of law, transparency, accountability and political stability, alongside reductions in corruption, can strengthen investor confidence, improve the business environment and attract higher levels of FDI. These factors can boost productivity, stimulate private-sector development and accelerate long-term economic growth in Ghana.
Under the AfCFTA scenario, Ghana’s GDP per capita is projected to reach US$12 830 by 2043, representing an increase of approximately US$750, or 6.2%, relative to the Current Path. These gains highlight the significant growth potential associated with deeper regional economic integration. By reducing tariff and non-tariff barriers, expanding access to continental markets and strengthening participation in regional value chains, the AfCFTA can enhance Ghana’s trade competitiveness and stimulate economic diversification.
Greater trade openness through the full implementation of the AfCFTA is also expected to facilitate technology transfer, boost productivity and encourage innovation, thereby improving the efficiency with which resources are allocated across the economy. In addition, access to a larger regional market can support export expansion, strengthen the manufacturing sector through increased competition and economies of scale, and attract investment into higher-value-added activities. Collectively, these effects can accelerate economic growth, create employment opportunities in key sectors and contribute to sustained poverty reduction.
Chart 30 presents poverty in the Current Path and for each scenario, from 2020 to 2043. The user can select the number of extremely poor people or the percentage of the population.
Using the World Bank LMICs poverty line of US$4.20 per person per day, all intervention scenarios reduce poverty in Ghana relative to the Current Path. However, the Governance scenario delivers the largest reduction in poverty by 2043, followed by the Infrastructure and Leapfrogging, the Manufacturing and Agriculture scenarios. The Demographics and Health scenario and the Financial Flows scenario have the smallest impact in reducing poverty by 2043.
Under the Governance scenario, the poverty rate is projected to decline to 20.6% by 2043, compared with 23.7% under the Current Path. This represents a reduction of approximately three percentage points. Using the headcount poverty, this would result in around 1.4 million fewer people living below the US$4.20-per-day poverty line, reducing the number of people in poverty to approximately 10.4 million, compared with 11.0 million under the Current Path in 2043.
The strong poverty-reducing impact of the Governance scenario reflects the central role that effective institutions play in fostering inclusive economic development. Good governance characterised by effective regulation, transparency, accountability and strong control of corruption ensures that all citizens, particularly the poor, are able to participate in and benefit from economic growth. Well-functioning institutions improve the efficiency of public resource allocation, create a predictable regulatory environment for investment, and support the equitable distribution of economic opportunities. Conversely, corruption undermines these processes by diverting public resources, weakening service delivery, and distorting spending priorities in favour of narrow interests. This disproportionately affects poor and vulnerable populations, who often face reduced access to quality education, healthcare, infrastructure and economic opportunities.
Strengthening governance therefore has a dual effect: it enhances economic efficiency by reducing waste, uncertainty and transaction costs, while simultaneously improving equity by ensuring that the gains from growth are more broadly shared. In Ghana, reforms that strengthen transparency, improve institutional effectiveness and promote accountable governance can serve not only as catalysts for higher economic growth but also as powerful instruments for poverty reduction and inclusive development.
By 2043, the Large Infrastructure and Leapfrogging scenario is projected to reduce the poverty rate to 20.9%, translating to a decline of about 2.8 percentage points. This would result in 1.36 million fewer people living below the US$4.20-per-day poverty line. Improved infrastructure and technological adoption accelerate economic productivity, expand access to markets and services, and create employment opportunities, thereby contributing to broad-based poverty reduction.
The Demographics and Health scenario is projected to have the smallest impact on poverty, lowering the poverty rate by about 0.9 percentage points to 22.8% by 2043. Nevertheless, this modest reduction would still lift approximately 67 000 people out of poverty relative to the Current Path. While investments in health and demographic outcomes yield important long-term benefits through improved human capital and labour productivity, their effects on poverty reduction tend to materialise more gradually than interventions that directly stimulate economic growth and job creation.
Chart 31 presents GDP in the Current Path and in the Combined scenario from 2020 to 2043. The data is in US$2017 and at market exchange rates (MER).
The Combined scenario combines all eight sectoral scenarios: Governance, Demographics and Health, Education, Large Infrastructure and Leapfrogging, Agriculture, Manufacturing, AfCFTA and Financial Flows.
In practice, these eight sectors do not operate independently; rather, they are linked through strong economic complementarities and spillover effects. Investments in infrastructure and human capital, for example, are fundamental enablers of industrialisation, productivity growth and economic diversification. Similarly, the expansion of rural transport networks lowers transaction costs, improves market access and facilitates agricultural commercialisation, thereby strengthening food security and self-sufficiency. A more productive agricultural sector can, in turn, stimulate manufacturing development through backward and forward linkages, particularly in agro-processing and value-added activities. At the same time, improvements in governance and security provide the institutional foundation necessary for investment, efficient resource allocation and private sector development, reinforcing progress across all sectors of the economy.
These strong intersectoral linkages suggest that a holistic and coordinated policy approach offers the greatest potential for achieving sustained and inclusive economic growth in Ghana. Rather than pursuing isolated sectoral interventions, a comprehensive development strategy can generate synergies that amplify the impact of individual reforms and investments. The Combined scenario therefore integrates all the sectoral interventions described above, representing a broad-based development push aimed at simultaneously addressing the structural constraints to growth, productivity, job creation and poverty reduction. By leveraging complementarities across sectors, the Combined scenario seeks to accelerate economic transformation, strengthen resilience and promote more inclusive development outcomes over the long term.
Under the Combined scenario, the size of Ghana’s economy, measured in GDP at the market exchange rate (MER) will be US$489 billion by 2043, about US$190.5 billion larger than under the Current Path. This represents an increase of approximately 63.8% relative to the Current Path projection. Thus, the Combined scenario places Ghana on a significantly higher growth trajectory.
Chart 32 presents GDP per capita in purchasing power parity (PPP) in the Current Path and the Combined scenario. The data is from 2023 with a forecast to 2043.
The impact of the Combined scenario on GDP per capita is significantly greater than the sum of the individual thematic scenarios. Ghana’s GDP per capita will be 18 750 by 2043, US$6 670 higher relative to the Current Path forecast. This will represent an increase of around 55.2% compared to the Current Path projection.
Chart 33 presents the value-add by sector in the Current Path and in the Combined scenario, for 2023 and 2043. The data is in US$ 2017 and as a percentage of GDP.
Our modelling provides forecasts in six economic sectors namely agriculture, energy, materials (including mining), manufactures, services and ICTech.
In 2025, the services sector was the largest contributor to Ghana’s economy, generating US$47.7 billion in value added and accounting for 50.1% of GDP. Under the Current Path, the sector is projected to more than triple in size, reaching US$169.8 billion by 2043, while its share of GDP increases to 56.9%, reflecting the continued structural shift towards services as incomes rise and the economy develops.
Under the Combined scenario, the services sector remains the dominant sector of the economy, although its share of GDP is projected to be 4.4 percentage points lower than under the Current Path, accounting for 52.5% of GDP by 2043. This relative decline does not indicate weaker performance; rather, it reflects faster growth in other productive sectors, particularly the manufacturing, as the economy becomes more diversified. In absolute terms, the services sector expands substantially to US$256.5 billion, which is approximately US$86.7 billion larger than the Current Path projection.
The agriculture sector was the second-largest contributor to Ghana’s economy in 2025, generating approximately US$18.4 billion in value added and accounting for 19.3% of GDP. Under the Current Path, agriculture’s share of GDP is projected to decline to 7.9% by 2043, reflecting the structural transformation typically associated with economic development, where the relative importance of agriculture decreases as industry and services expand more rapidly.
In the Combined scenario, agriculture’s contribution is projected to be modestly higher, accounting for 8.6% of GDP by 2043, compared with 7.9% under the Current Path. While this represents an increase of only 0.7 percentage points, it indicates a more productive and resilient agricultural sector that continues to play an important role in supporting economic growth, food security and rural livelihoods. Nevertheless, agriculture is projected to become the third-largest sector by 2043 as the manufacturing sector expands more rapidly.
The manufacturing sector was the third-largest contributor to Ghana’s economy in 2025, accounting for 13.5% of GDP. Under the Current Path, the sector is projected to expand significantly, increasing its share of GDP to 19.2% by 2043, equivalent to approximately US$57.3 billion in value added. In the Combined scenario, the manufacturing sector is projected to grow even more rapidly, with its share of GDP rising to 21.6% by 2043, an increase of 2.4 percentage points relative to the Current Path.
The ICT sector was the fourth-largest contributor to Ghana’s economy in 2025, accounting for approximately 6% of GDP. Under the Current Path, the sector’s share is projected to rise gradually to 7% by 2043. This expansion illustrates the importance of digital infrastructure and innovation in building a modern, competitive economy. In the Combined scenario, the ICT sector is expected to play an even more prominent role in the economy, with its contribution increasing to 7.9% of GDP by 2043, representing a gain of 0.8 percentage points relative to the Current Path.
The energy sector was the fifth-largest contributor to Ghana’s economy in 2025, accounting for 5.7% of GDP. Under the Current Path, the sector’s share is projected to decline significantly to 2.6% by 2043. Under the Combined scenario, the energy sector performs somewhat better, with its share of GDP increasing to 3.0% by 2043, representing a 0.4 percentage-point gain relative to the Current Path. Nevertheless, despite this improvement, the energy sector is projected to become the smallest contributor to GDP by 2043, as more rapidly growing sectors such as manufacturing, services and ICT account for an increasing share of economic output.
The materials sector, which includes mining and quarrying activities, was the smallest contributor to Ghana’s economy in 2025, accounting for 5.4% of GDP. Under the Current Path, its share of GDP is projected to increase modestly to 6.3% by 2043, reflecting continued growth in extractive industries and demand for mineral resources. Under the Combined scenario, the sector’s contribution is projected to rise slightly further to 6.5% of GDP by 2043.
Chart 34 presents the size of the informal sector in the Current Path and in the Combined scenario, from 2020 to 2043.
Countries with high levels of informality often face significant development constraints, including weak domestic revenue mobilisation, limited social protection coverage and lower productivity. A large informal sector can reduce the tax base, constrain public investment and limit the state’s capacity to finance essential services and infrastructure. As a result, economic growth in highly informal economies often remains below potential, as many firms and workers operate outside formal regulatory, financial and productivity-enhancing systems.
Coordinated reforms across sectors can accelerate formalisation by expanding productive employment, improving the business environment, strengthening governance and increasing access to infrastructure, finance and markets. A reduction in informality of this magnitude would broaden the tax base, enhance fiscal capacity and support more inclusive and sustainable economic growth.
As in many African economies, Ghana’s informal sector remains large. In 2025, it was estimated to account for 28.9% of GDP. Under the Current Path, informality is projected to decline only modestly, falling to 25.3% of GDP by 2043. In the Combined scenario, the size of the informal economy in Ghana is projected to decline more rapidly, reaching 18.3% of GDP by 2043, a seven percentage points reduction relative to the Current Path in the same year.
Chart 35 presents poverty in the Current Path and the Combined scenario, for 2023 and 2043.
In the Combined scenario, Ghana is projected to achieve significantly greater poverty reduction than under the Current Path. Using the LMICs poverty line of US$4.20 per person per day (2021 PPP), the poverty rate is expected to decline to 8.9% by 2043, approximately 14.8 percentage points lower than the Current Path projection for the same year.
Using the international extreme poverty line of US$3.00 per person per day (2021 PPP$), the Combined scenario is projected to reduce the extreme poverty rate to 3.4% by 2043, compared with 12.6% under the Current Path. This represents a 9.2 percentage-point decline and would result in approximately 4.3 million Ghanaians escaping extreme poverty by 2043. These substantial reductions reflect the synergistic effects of coordinated interventions across multiple sectors of the economy.
The stronger poverty outcomes arise because the Combined scenario simultaneously addresses the structural causes of poverty while expanding opportunities for inclusive growth. Investments in human capital enhance labour productivity, employability and earning potential; structural transformation in manufacturing and agriculture creates productive and formal employment opportunities; and improvements in infrastructure and digital connectivity reduce transaction costs while expanding access to markets, services and information. In addition, stronger institutions and improved fiscal capacity enhance the government's ability to provide targeted social protection and support vulnerable households. Together, these interventions ensure that the gains from economic growth are more broadly distributed, resulting in faster poverty reduction and more inclusive development outcomes.
Alongside substantial poverty reduction, the Combined scenario also delivers significant improvements in income distribution. Ghana’s Gini coefficient—a widely used measure of income inequality, where 0 denotes perfect equality and 1 indicates complete inequality is projected to decline from 0.43 under the Current Path to 0.39 by 2043.
The improvement in income distribution reflects the broad-based nature of the Combined scenario, which expands access to productive employment, enhances human capital, and increases economic opportunities across regions and population groups. As a result, the benefits of higher growth are more widely shared, reducing disparities in income and living standards. The sharper decline in the Gini coefficient suggests that the Combined scenario promotes not only faster economic growth but also a more inclusive pattern of development, in which improvements in welfare are distributed more evenly across society.
Chart 36 compares life expectancy in the Current Path with the Combined scenario from 2020 to 2043.
Life expectancy at birth is widely recognised as one of the most comprehensive indicators of a population’s overall health and well-being. It reflects not only mortality patterns but also access to healthcare, nutrition, sanitation, education and broader living conditions. As such, it serves as a powerful proxy for the strength of a country’s human capital base.
In Ghana, life expectancy remains relatively low by regional averages, reflecting longstanding constraints in healthcare access, nutrition, sanitation and broader living conditions. Improving health outcomes is therefore critical for strengthening human capital. A healthier population is generally more productive, able to participate in the labour force for longer, and better positioned to contribute to sustained economic growth. In this sense, gains in life expectancy and overall health can generate important economic dividends by raising labour productivity, reducing disease-related losses, and supporting more inclusive development.
In 2025, life expectancy at birth in Ghana was estimated at 66 years, comprising 63.2 years for males and 68.9 years for females. Under the Current Path, life expectancy is projected to increase steadily to 71.5 years by 2043, reflecting gradual improvements in healthcare access, nutrition and living standards. Under the Combined scenario, life expectancy is projected to rise further to 74.8 years by 2043, an increase of 3.3 years above the Current Path forecast.
This relatively strong life expectancy is an asset; it must be complemented by investments in education, job creation and governance reforms to transform longer lives into higher productivity, innovation and inclusive growth. Without these, the relatively high life expectancy advantage may not translate into sustained economic diversification or improved living standards.
A population that lives longer but lacks sufficient opportunities for skill acquisition, formal employment or productive engagement risks underutilising its potential. In such cases, the economic gains of high life expectancy are not fully realised.
Chart 37 compares carbon emissions in the Current Path with the Combined scenario from 2020 to 2043.
As in many African economies, Ghana’s carbon emissions remain relatively modest despite steady economic growth. Compared with the continent’s largest emitters (South Africa, Egypt, Algeria, and Nigeria), Ghana’s carbon emissions are lower because of its relatively small industrial and manufacturing base, which limits energy-intensive production. In 2025, Ghana emitted approximately 31.3 million tonnes of carbon dioxide from fossil fuel consumption, accounting for just 1.8% of Africa’s total emissions. This underscores Ghana’s limited contribution to the continent’s overall carbon emissions, although emissions have increased significantly from about 21.3 million tonnes in 2020, reflecting rising energy demand and expanding economic activity.
The upward trend in emissions has strengthened the case for climate mitigation policies. Under its Nationally Determined Contribution, Ghana has committed to reducing greenhouse gas (GHG) emissions by 15% by 2030 through interventions across the energy, transport, agriculture, forestry, land-use, and industrial sectors. Key measures include improving energy efficiency in industrial facilities by 20%, restoring and afforesting 10,000 hectares of degraded land annually, and substituting light crude oil with natural gas in electricity generation. These initiatives aim to decouple economic growth from carbon emissions while supporting the country’s broader sustainable development objectives.
Despite its relatively low emissions profile, Ghana ranked as the ninth-largest carbon dioxide emitter among Africa’s 55 countries in 2025, highlighting the concentration of emissions within a small group of economies on the continent. However, Ghana remains highly vulnerable to the adverse effects of climate change, including extreme heat, recurrent droughts, and growing water scarcity. This reflects a broader climate justice challenge facing many developing economies: countries that have contributed relatively little to global greenhouse gas emissions often bear a disproportionate share of the economic, environmental, and social costs associated with climate change.
The major source of carbon emission in Ghana is land-use change and forestry which contributes about 53% of total emissions in the country mainly due to changes in forest cover. A major cause for the depletion of forest reserves is the activities of illegal mining. According to the Ghana Forestry Commission, 34 out of the 288 forest reserves in the country have been affected by illegal mining, in the process destroying 4 726 hectares of forest land. Major reserves such as Offin Shelterbelt and Asenanyo Forest, Nueng South and Bonsa River forest reserves, Atewa Range Extension and Atewa Range forest reserves, Denyau Forest Reserve, Supoma Forest Reserve, Apamprama Forest, Subin Shelterbelt Reserve and Oda River Forest Reserve have been destroyed by illegal mining activities. Another source of carbon emission is energy production which accounts for 25% of total emission in the country.
Under the Current Path, Ghana’s carbon dioxide emissions are forecast to further increase to 58.3 million tons by 2043. The materialisation of the Combined scenario, associated with rapid economic growth in Ghana, will increase carbon dioxide emissions to 60.2 million tons by 2043, about 2.0 million tons above the Current Path in that year.
Chart 38 compares energy demand and production in the Current Path with the Combined scenario from 2020 to 2043.
Production is done in nine types, namely oil, gas, coal, hydro, nuclear, solar, wind, geothermal and other renewables. The data is converted into billion barrels of oil equivalent (BBOE) to allow for comparisons. Note that energy production could be for domestic use or for export.
The total energy produced in Ghana in 2025 was equivalent to 118.5 million barrels of oil equivalent (BOE). In the same period, total energy demand was estimated at 113.3 million BOE, leading to a surplus of 5.2 million BOE. This excess energy is partly due to the numerous power purchase agreements that were signed in 2014/2015 at the peak of its energy crisis as discussed in the preceding Large Infrastructure and Leapfrogging section. Under the Current Path, total energy demand is forecast to increase to 306.7 million BOE, outpacing projected production of 185.6 million BOE by 2043, creating an energy demand deficit of 121.0 million BOE.
Between 1990 and 2009, hydro was the sole energy produced by the country. With Ghana discovering oil in commercial quantities and starting to commercialise production, oil became the second-largest energy source. By 2011, oil had become the dominant energy produced in the country, accounting for over 80% of the total energy produced in the country, which is equivalent to 24.1 million BOE. As a result of its oil production, it also started producing gas in 2015. Currently, the main sources of energy produced in Ghana are oil, gas, hydro and some negligible amount of other renewable energy. In 2025, the total amount of oil produced in the country amounted to 78 million BOE, constituting 66% of total production.
Ghana’s crude oil production is sourced from three main fields: Jubilee which commenced production in December 2010, TEN in August 2016 and Sankofa Gye-Nyame (SGN) in May 2017. In 2023, the Jubilee field produced 63% of total crude oil production while SGN and TEN accounted for 23% and 14% of total crude oil production, respectively.
Oil production is followed by gas production which accounted for 25% of total production in 2025. Ghana’s gas production is sourced from the Atuabo Gas processing plant, which produces natural gas and processes it into liquefied petroleum gas for domestic use. Prior to this, all domestic gas in Ghana was imported from Nigeria through the West African Gas Pipeline.
Hydro production accounted for about 8% of total energy production in 2025. The major source of hydro production in Ghana is the Akosombo dam, which was constructed in 1965 to generate 1020MW. Other hydro sources of power include the Kpong Hydro Plant, established in 1982, which generates 160MW. The Bui Dam, which was also constructed from 2007 to 2013, generates 400MW of hydro power for the country, similar to Kpong.
By 2027, Ghana will have more than 17 oil and gas projects scheduled for development, which could improve its oil and gas production. These major projects include the Jubilee South East Project – developed by oil and gas company Tullow Oil; the Pecan Conventional Oilfield – developed by global energy firm Aker Energy, the Ghana National Petroleum Company (GNPC), Russian multinational oil and gas company Lukoil and maritime engineering and energy company Bulk Ship & Trade; and the Ntomme Far West Development. In addition, ongoing hydro projects such as the Akosombo Hydrokinetic (95MW), Juale (90MW), Lanka (95MW), Ntereso (64MW) and Hemang (60MW) will boost the country’s hydro capacity.
Under the Current Path scenario, Ghana’s total energy production is projected to increase to 185.6 million BOE by 2043. However, the composition of the energy mix will change significantly, with oil and gas accounting for a smaller share of total output as hydroelectric and renewable energy sources expand. Oil and gas production are forecast to decline to 37.9 million BOE and 26.4 million BOE, respectively, by 2043. This decline reflects both the gradual depletion of domestic hydrocarbon reserves and the global transition to cleaner, more sustainable energy sources.
In the Combined scenario, Ghana’s energy demand is projected to reach 404.5 million BOE by 2043, approximately 97.8 million BOE higher than under the Current Path, driven by faster economic growth and rising energy consumption. Although total energy production would also increase substantially to 276.8 million BOE, supply would still fall short of demand, resulting in an energy deficit of about 127.7 million BOE. This highlights the scale of investment required in energy generation, infrastructure, and efficiency improvements to support accelerated economic development while maintaining energy security.
Chart 39 summarises the policy recommendations.
Since independence, Ghana has achieved notable economic progress, supported by a series of national development strategies and internationally backed reform programmes. Key initiatives—including the Structural Adjustment Programmes (SAPs), the Highly Indebted Poor Countries (HIPC) Initiative, the Aid Effectiveness Agenda, the Millennium Development Goals (MDGs), and, more recently, the Sustainable Development Goals (SDGs)—have contributed to macroeconomic stabilisation, economic liberalisation and sustained growth. The cumulative impact of these reforms helped accelerate economic expansion over the past two decades and culminated in Ghana attaining lower-middle-income status in 2010.
Despite these achievements, the country's economic growth has not translated fully into broad-based development outcomes. Persistent fiscal challenges, including high public debt, weak domestic revenue mobilisation and governance constraints, have limited the state's capacity to invest in development priorities. At the same time, successive governments have struggled to achieve substantial reductions in unemployment, poverty and income inequality, while improvements in living standards have been uneven across the population. Consequently, many of the expected social and economic dividends of growth have remained elusive.
Underlying these challenges is the limited structural transformation of the Ghanaian economy. Although the economy has diversified somewhat over time, it continues to rely heavily on the production and export of primary commodities, particularly cocoa and gold, while depending substantially on imports of manufactured and higher-value-added goods. This pattern has constrained productivity growth, export diversification and job creation in higher-productivity sectors. With the exception of the early post-independence industrialisation efforts of the 1960s, there have been relatively few sustained attempts to fundamentally restructure the economy towards a more diversified, industrialised and value-added growth model. As a result, the economy remains characterised by a relatively large agricultural sector, limited industrial depth and vulnerability to external commodity price fluctuations.
Article 36 of Ghana’s 1992 Constitution requires the state to manage the national economy in a manner that maximises economic development, promotes the welfare, freedom and happiness of all citizens, provides adequate livelihoods and suitable employment, and ensures public assistance for those in need. However, this constitutional objective remains only partially realised. Similarly, Ghana’s Vision 2057 sets out an ambition to build a free, just, prosperous and self-reliant nation that secures the welfare and happiness of its citizens while playing a leading role in international affairs. Achieving this vision will require more than sustained economic growth; it will demand a comprehensive and targeted package of socio-economic policy interventions capable of raising living standards, expanding opportunities and moving the country towards upper-middle-income status.
Put differently, Ghana’s long-term development prospects depend on its ability to address the structural constraints that have limited economic transformation since independence. This requires major policy reforms and strategic investments across key sectors, including demographics, health, education, agriculture, infrastructure, manufacturing, trade, financial flows and governance. As this study has shown, Ghana has the potential to expand its economy and promote sustainable and inclusive growth. Realising these outcomes will require reforms that move Ghana decisively beyond its current development trajectory and place the economy on a more inclusive, productive and structurally transformed growth path.
As this study demonstrates, strengthening governance is one of the most important priorities for unlocking Ghana’s development potential. In particular, improving institutional effectiveness, enhancing transparency, reducing corruption and strengthening accountability can significantly increase the efficiency of public spending, improve service delivery and create a more conducive environment for private investment and economic growth. Stronger governance would also enhance domestic resource mobilisation and ensure that development gains are translated into improved welfare outcomes for the broader population.
At the same time, an aggressive export-oriented industrialisation strategy, centred on manufacturing and value addition, has the potential to accelerate structural transformation. Moving beyond a reliance on primary commodity exports towards a more diversified and industrialised economy would boost productivity, create quality jobs, expand export earnings and increase economic resilience. Such a transformation would contribute to faster poverty reduction, higher incomes and improved living standards for Ghanaians.
Achieving these objectives will also require substantial investment in human capital, particularly in education. Improving both the quality and relevance of education is essential to equip future generations with the knowledge, skills and competencies demanded by the Fourth Industrial Revolution. Aligning educational outcomes with the evolving needs of the labour market will enhance workforce productivity, support innovation and ensure that Ghana’s growing population is able to participate effectively in a modern, technology-driven economy.
The importance of these sectors notwithstanding, we recommend the following policy options in these sectors:
Demographics and Health
- Promote inclusive family planning practices as a shared responsibility between men and women and increase access to modern contraceptives.
- Also, the working conditions of doctors and other health professionals in the country should be reviewed and improved to minimise the drastic brain drain in the health sector.
- The government, through the Ministry of Health and the Ghana Health Service should intensify education on healthy lifestyle practices to reduce the rising burden of diseases such as kidney, strokes, cancer, and respiratory infections in the country.
- The government should uncap the national health insurance fund and ensure sufficient allocation and timely disbursement of funds towards service providers and healthcare.
- Complete the Agenda 111 projects to expand access to healthcare, especially to remote districts in the country
Education
- The government should review the Free Senior High School (SHS) programme, for greater efficiency by ensuring that those who can afford to pay their wards' fees are made to do so. Accordingly, students from private Junior High Schools (JHS) could be charged while SHS remains free for those from public JHS. Alternatively, parents could be made responsible for the feeding fees of their wards so that the government only has to cater for other costs.
- Elimination of schools under trees in basic schools and expansion of infrastructure at the secondary level to abolish the double track system.
- Continue with the prioritisation of STEM and vocational education to ensure that more students enrol in STEM and vocational courses.
- Provision of textbooks on the newly introduced curriculum to enhance the quality of learning in basic schools.
Agriculture
- Construction of multipurpose dams especially in the northern part of Ghana to ensure all-year-round agriculture
- Enhancing roads, storage facilities, and market access is crucial for reducing post-harvest losses and boosting farmer incomes
- Strengthen research on climate-smart agricultural technologies as part of the National Climate-Smart Agriculture and Food Security Action Plan.
- Adoption of modern Provision of subsidies on fertiliser especially to small-scale farmers to ensure improved yields
- Government, in partnership with traditional authorities, should address land tenure and land ownership challenges to ensure large-scale agriculture
Manufacturing
- Address the unstable electricity supply in the country to access reliable and cheap power for production.
- The government should reduce high import taxes on raw materials and levies at the port that increase the cost of production.
- Promoting manufacturing sector growth requires improving the country's macroeconomic conditions so that financial institutions can advance cheaper credit to micro, small, and medium-scale enterprises, which constitute the majority of firms in Ghana.
- Address the rising youth unemployment by promoting entrepreneurship, skills development and an enabling environment for the private sector to thrive in order to create more jobs.
- Higher educational institutions should also collaborate and partner with the private sector and businesses to design curricula that equip students with the required industrial and critical skills.
AfCFTA
- Commit to and take advantage of the full implementation of AfCFTA to trade more with other African countries.
Infrastructure
- The government must urgently address the energy sector debt to ensure a sustainable supply of electricity. Accordingly, it should prioritise using the proceeds from the energy sector levy to pay off some of these debts. Also, the inefficiency in power distribution and revenue collection by the electricity company of Ghana should be addressed to ensure revenue maximisation in the distribution of power
- The government should continue with its commendable digitalisation agenda to rapidly formalise the economy.
- The government should ban all mining activities around water bodies to prevent the looming danger of galamsey on water bodies in the country.
- Rely on its huge renewable energy sources such as solar and hydro to gradually phase out reliance on fossil fuel for its energy needs. This will help promote growth while ensuring that environmental concerns are addressed.
Financial Flows
- Address the macroeconomic challenges of the economy particularly the cedi fluctuation and high interest rate to inspire investor confidence. This will help the country to attract more FDI
- The government should encourage foreign investors to invest in capital and knowledge transfer to build the needed workforce in the country.
- With the massive remittance inflow into the country, the Government should encourage its expatriate community to invest in the economy by establishing diaspora bonds, as countries such as Israel, India, Nigeria, and Ethiopia have done. These bonds not only provide a secure investment opportunity for the diaspora but also inject much-needed capital into the economy, fostering growth and development.
Governance
- Urgent need for constitutional reforms to address major structural governance issues in the country. For instance, Article 78 of the constitution should be revised to separate the executive and legislative branches to ensure that Parliament operates with genuine independence. The current provision, which requires the President to appoint a majority of ministers from Parliament, compromises the legislature’s oversight and accountability functions
- Resource the office of the special prosecutor and other anti-corruption agencies in the country to effectively fight corruption.
- It is imperative to protect the independence of the police service by amending Articles 202 and 203 to reinforce the rule of law. The Police Council should be depoliticized, and the Inspector General of Police (IGP) and other key leaders should be appointed for fixed terms with guaranteed security of tenure
Government should tackle the rising insecurity in the northern part of Ghana and the threat of violent extremism.
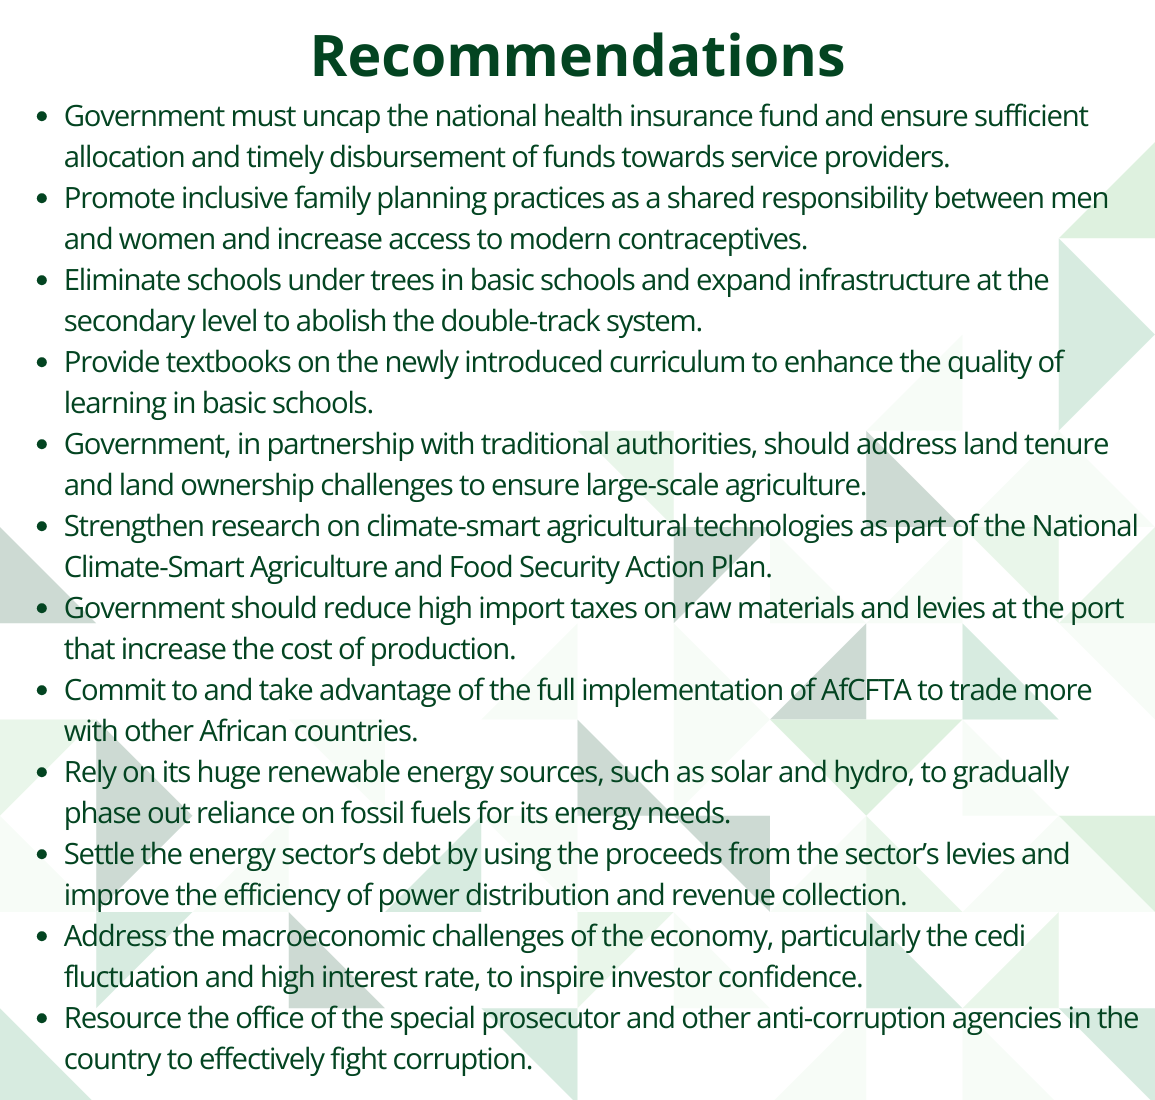
Page information
Contact at AFI team is Blessing Chipanda
This entry was last updated on 31 August 2026 using IFs v8.72.
Donors and sponsors
Reuse our work
- All visualizations, data, and text produced by African Futures are completely open access under the Creative Commons BY license. You have the permission to use, distribute, and reproduce these in any medium, provided the source and authors are credited.
- The data produced by third parties and made available by African Futures is subject to the license terms from the original third-party authors. We will always indicate the original source of the data in our documentation, so you should always check the license of any such third-party data before use and redistribution.
- All of our charts can be embedded in any site.
Cite this research
Blessing Chipanda (2026) Ghana Development Futures. Published online at futures.issafrica.org. Retrieved from https://futures.issafrica.org/geographic/countries/ghana/ [Online Resource] Updated 31 August 2026.