Africa needs better investment, not just more investment
Listen to this article
Investor rankings tell only part of the story, as both the scale and development impact of FDI matter.
Investor rankings can mislead
The widely held view that China has become Africa’s largest foreign investor risks distorting policymakers' assessments of the continent’s investment partnerships. The claim appears plausible because Chinese-built railways, ports, roads, industrial parks and power plants are highly visible. European and US investments are often less conspicuous, embedded in banks, telecommunications, consumer businesses, mining groups and corporate structures. Visibility, however, is not a statistical measure of investment.
The ranking depends on what is measured. Annual FDI flows capture net transactions during a particular year, while FDI stocks record accumulated ownership positions. Greenfield announcements describe planned investments in new facilities or operations, whereas brownfield investment involves acquiring, expanding or upgrading existing assets. Construction contracts measure revenue from delivering projects without necessarily creating a foreign ownership stake.
That distinction matters particularly for China. In 2024, for example, China recorded US$3.37 billion in FDI flows to Africa, while Chinese companies earned US$40 billion from engineering and construction projects on the continent. The latter is contract revenue, not FDI. China’s combination of investment, lending and contracting makes its economic presence exceptionally visible, but does not make it Africa’s largest source of conventional FDI.
European investors retain the largest FDI presence in Africa
FDI positions (or accumulated stocks) provide a clearer indication of investors’ established presence. China’s FDI position in Africa increased from US$26.19 billion in 2013 to US$43.80 billion in 2024. It nevertheless remained below the US position of US$47.47 billion. The EU-27 held by far the largest collective position, at approximately US$270.72 billion in 2024, more than six times China’s stock and almost six times that of the US.
The EU-27 also recorded some of the largest annual FDI flows over 2013–2024, although these were considerably more volatile. US flows were generally modest and frequently negative. China, by contrast, recorded smaller but more consistently positive annual flows. Negative flows may reflect asset sales, intracompany debt repayments or profit distributions rather than the closure of existing operations. Annual flows should therefore be interpreted as short-term financial movements rather than as a measure of investors’ accumulated presence.
However, FDI stock comparisons in Chart 1 should be interpreted with caution. Countries such as the Netherlands can act as intermediate corporate and financial jurisdictions, meaning the immediate investing country may differ from the ultimate beneficial owner of the capital. Valuation methods, geographical coverage and the treatment of special-purpose entities also complicate comparisons. Even allowing for these limitations, the available evidence does not support the view that China has overtaken Europe as Africa’s largest holder of conventional FDI. In any case, investor rankings are useful for understanding the changing structure of Africa’s investment partnerships, but they do not reveal the development impact of those investments. That requires examining where investment goes, what it creates and how strongly it connects to the domestic economy.
Both the scale and impact of investment matter
Investor nationality tells only part of the development story. The sectoral destination and domestic linkages of investment strongly shape its contribution to structural transformation. China’s concentration in construction and mining can help relieve transport and energy infrastructure bottlenecks, expand industrial capacity and generate foreign exchange, but outcomes depend heavily on local procurement, processing, employment and technology transfer. Europe’s broader footprint across manufacturing, services, renewable energy and infrastructure may support a wider range of productive linkages. In contrast, US investment in finance, digital services, energy and healthcare can contribute to financial deepening, technological upgrading and higher-value services.
These sectoral profiles highlight distinct development opportunities rather than a simple ranking of investment quality. Infrastructure can reduce production and trade costs; extractives can generate foreign exchange and fiscal revenue; and manufacturing and tradable services can offer wider opportunities for employment, supplier development and technology transfer.
Africa’s policy challenge is therefore not to choose between China and its traditional investment partners but to harness competition among investors to increase both the scale and development impact of FDI. This means attracting investment that expands productive capacity, creates better jobs, transfers skills and technology, strengthens domestic suppliers, increases exports and raises public revenue.
The central test should be additionality: does an investment create assets, capabilities and domestic linkages that would not otherwise exist?
Absorptive capacity changes the return from finance
Investment volume and quality are not competing priorities. More external finance can generate development gains, but those gains are considerably larger when countries have the domestic capacity to use additional resources productively.
Investment quality also depends on the capacity of recipient economies to turn foreign capital into productive activity. Infrastructure, skills, effective institutions, domestic suppliers and technology absorption determine whether additional finance generates wider gains or remains weakly connected to the domestic economy.
Scenario analysis by the African Futures and Innovation (AFI) Programme at the Institute for Security Studies (ISS) illustrates the importance of this capacity. In a scenario combining higher FDI, portfolio investment, aid and remittances, increasing external finance without strengthening domestic absorptive capacity raises Africa’s GDP by only about US$63.7 billion or 0.8%, above the Current Path (baseline forecast) by 2043, the end of the third ten-year implementation plan of AU Agenda 2063. When the same interventions are accompanied by stronger investment efficiency, technology absorption, institutional capability, skills utilisation and domestic productive linkages, the gain rises almost threefold to approximately US$210 billion or 2.6%.
The modelling does not imply that foreign finance automatically raises productivity. Rather, it illustrates how much more development could be generated when countries strengthen the domestic capabilities through which additional capital is deployed. Attracting sufficient volumes of investment is essential, but the development payoff is much larger when that investment is converted into domestic productive capacity.
Making FDI work better for Africa
To attract larger volumes of FDI while maximising their development impact, African governments should act on four fronts.
First, improve investment transparency and selectivity. Investment data should identify the ultimate beneficial owner, the financing instrument, the sector and the project status, with announced commitments clearly distinguished from realised investment.
Second, strengthen domestic absorptive capacity. Reliable infrastructure, skills, effective institutions, project preparation and domestic supplier networks can increase technology absorption, reinvestment and local value creation.
Third, link incentives to development outcomes. Investment incentives should be transparent and time-bound, with measurable expectations for employment, workforce training, exports, local procurement and technology transfer. Sector policies should reflect different opportunities: local processing and supplier development in extractives; open procurement and multipurpose infrastructure; and stronger links to skills systems and African value chains in manufacturing and services.
Fourth, deepen domestic financial markets. Stronger banking systems, capital markets and long-term financing can help domestic firms access finance, participate in foreign-investment projects, scale supplier relationships and mobilise local savings.
Effective implementation of the AfCFTA can reinforce these measures by expanding market scale and making regional production and sourcing more commercially viable.
Successful FDI depends on both how much capital Africa attracts and how much productive value it retains
The data point to a more nuanced investment landscape. China has become a major and increasingly important investor in Africa, but it has not overtaken Europe as the continent’s largest holder of conventional FDI. More importantly, the development challenge is not to choose between investment quantity and quality. Africa needs both: sufficient volumes of long-term capital and domestic conditions that allow that capital to expand productive capacity, transfer skills and technology, deepen local supply chains and generate public revenue.
Successful FDI, therefore, depends not only on how much capital Africa attracts or who provides it, but also on how much productive value the continent retains from that investment.
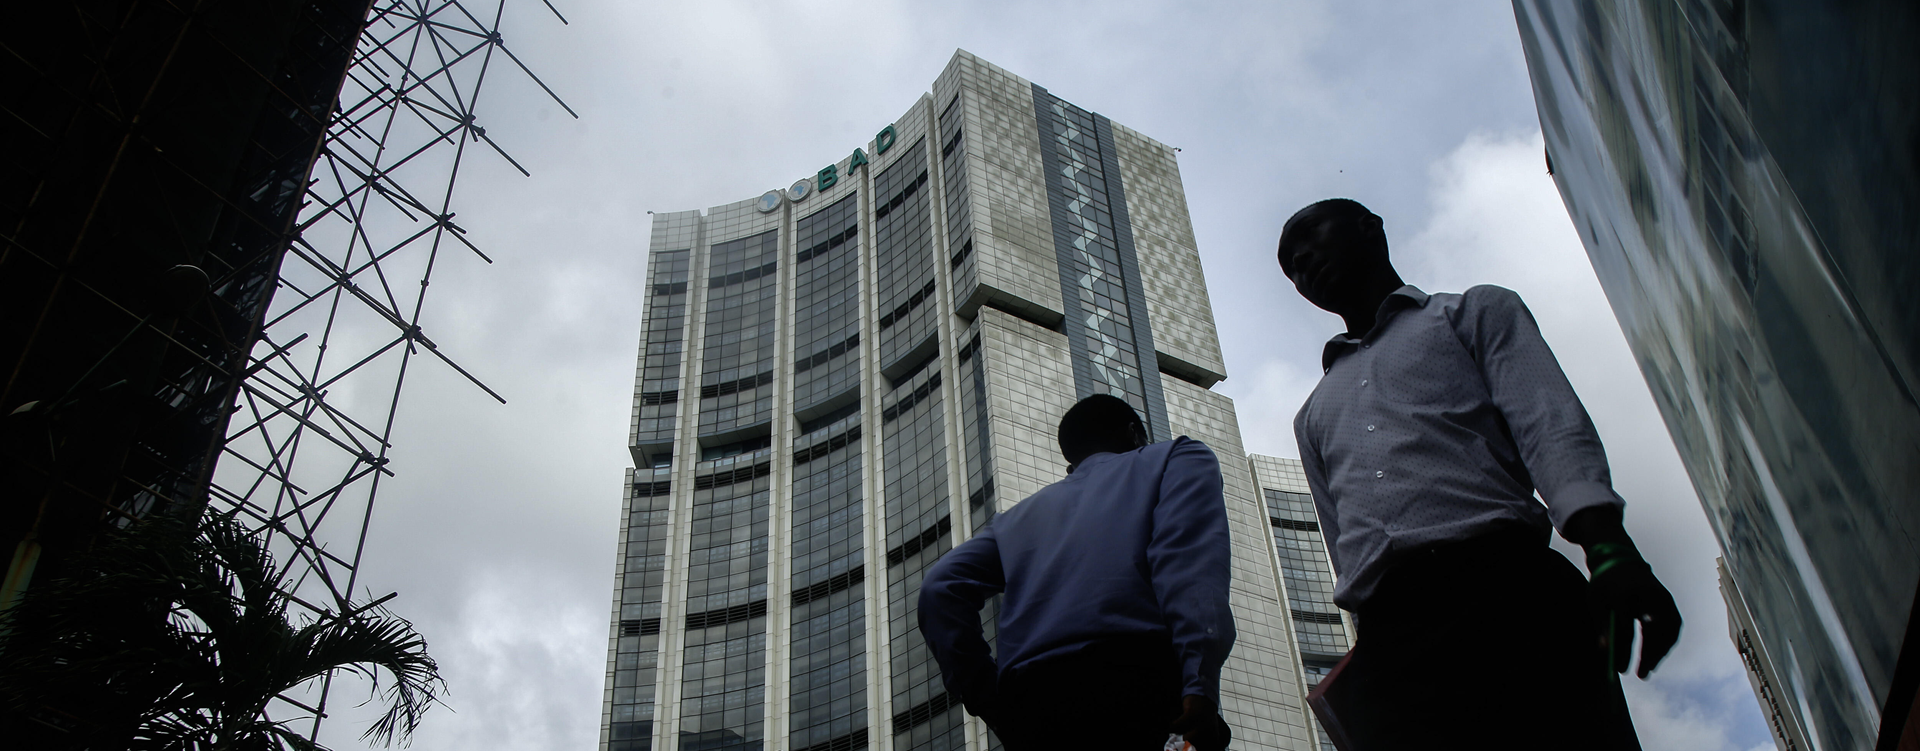
Image: picture alliance / Matrix Images | Joseph Zahui
Picture Information: Pedestrians walking next to the headquarters of the African Development Bank (AfDB) in Abidjan, Ivory Coast on May 28, 2025.
Republication only with permission. Contact us for any enquiries.
This article is part of the Spotlight series in the project, The Future of African-European Relations.
The Future of African-European Relations project examines how the two regions can build stronger partnerships in an era of geopolitical fragmentation, economic competition and changing global power dynamics. It is a collaboration between the African Futures & Innovation Programme at the Institute for Security Studies (ISS), the Federation of German Industries (BDI), the Hanns Seidel Foundation and the Megatrends Afrika consortium, comprising the German Institute for International and Security Affairs (SWP), the German Institute of Development and Sustainability (IDOS) and the Kiel Institute for the World Economy. Drawing on the expertise, research and analytical frameworks of the participating institutions, the project explores how different global futures could shape trade, investment, development cooperation and shared prosperity between Africa and Europe - and it aims to develop policy recommendations for different stakeholders.
Disclaimer: Opinions expressed reflect the views of authors, not necessarily those of the organisations partnering in the project, The Future of African-European Relations.